
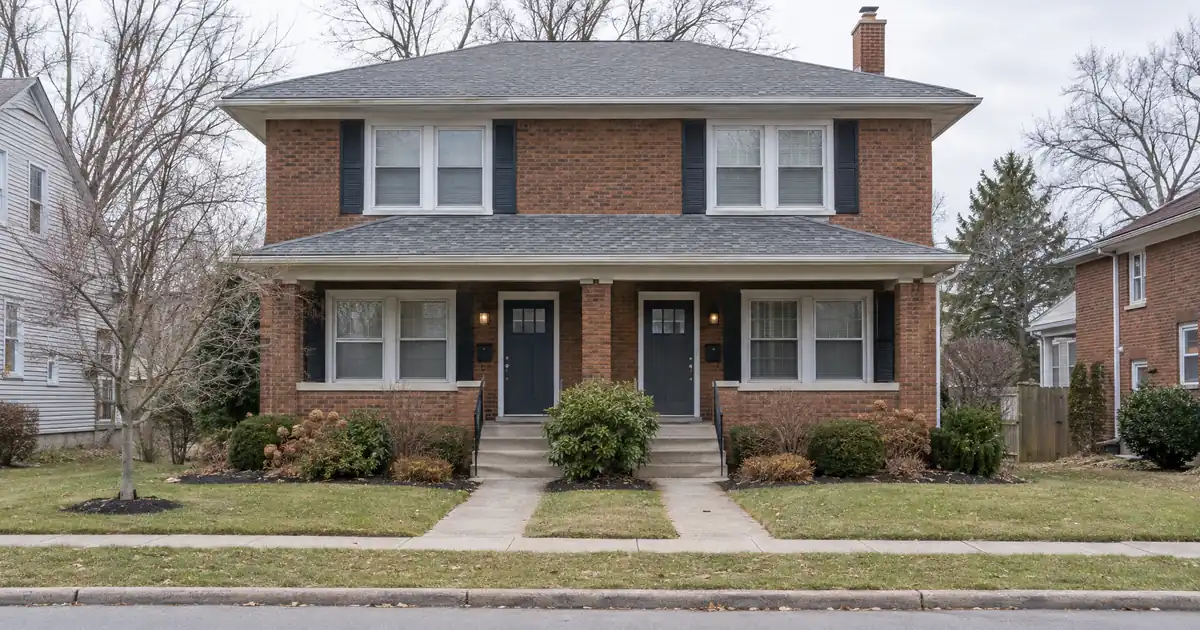
Most cash-out advice assumes rent and value rise together, so the more equity you have, the more you can pull. Powell breaks that logic. The equity is often large, but the rent behind it is not, and the 75 percent loan-to-value ceiling is rarely the number that limits the deal. Coverage is. Only about 11 percent of Powell households rent, so this is a market where owners hold a lot of value and tenants are scarce.
Lendmire (NMLS# 2371349), a DSCR-focused mortgage broker offering DSCR financing in 40 states plus D.C., arranges cash-out refinances through wholesale lending channels. The Powell file it sees most often is a long-held single-family rental or townhome with strong equity and coverage that needs work.
DSCR Cash-Out Calculator
Run the cash-out numbers in Powell, OH
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
At a Glance: A Powell cash-out refinance on an investment property is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the rent has to carry taxes, insurance and the new loan together. With Redfin’s median sale price at $576K, the loan balance is what drives coverage here.
- Powell rent-to-value runs near 0.5 percent monthly, so full-PITIA coverage usually needs low leverage.
- Cash-out caps at 75 percent LTV, and seasoning runs about six months from title recording.
- Powell has almost no 2-4 unit stock, so equity often deploys elsewhere.
- Renter-occupied households are roughly 11 percent, which means thin rent comps.
Powell Market Snapshot
A quick read on the Powell investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $576K median (Redfin Powell Housing Market) |
| Typical rents | $3,499 house (Trulia Powell rent) |
The Equity Is Real. The Rent Isn’t Keeping Up.
Powell is an executive commuter suburb 14 miles north of Columbus, in Delaware County. Census Bureau QuickFacts lists about 14,451 residents, and 78.1 percent of adults hold a bachelor’s degree or higher. Ohio-Demographics.com puts median household income at $195,495. That is an owner-occupier town by design, and the values reflect it. City-data.com estimates the median house or condo value at $598,177, up from $260,300 in 2000.
For an investor who bought a rental years ago, that history is the whole thesis. The equity accumulated regardless of what the rent did. Rents are high in absolute terms. Homes.com puts the median single-family rent at $2,800, and 3-bedroom houses at $2,650. Those figures sit against a $576K median price, so the ratio is thin.
The sources also disagree on rents, so underwrite to a range. Zumper shows an average of $2,600, while Zillow’s all-property-type average is $2,326. Trulia shows houses at $3,499. And direction is contested: Zumper shows a 2 percent rise, while Rentcast’s ZIP-level series shows a 9.1 percent decline. Nobody should build a coverage model on the top of that range.
What Does 0.5 Percent Rent-to-Value Do to the Coverage Number?
It caps how much of the equity you can extract. Using the $2,800 median single-family rent against the $576K median price gives a gross monthly rent-to-value of roughly 0.5 percent (a modeled figure, not a sourced one). DSCR divides monthly rent by the full monthly obligation: principal, interest, taxes, insurance and any HOA dues. At that ratio the taxes and insurance alone take a real bite before the loan payment starts.
Run the numbers on a hypothetical. Say you own a 3-bedroom house valued near the $576K median and the rent schedule supports $2,800. These are modeled inputs, not a specific property, and coverage includes taxes and insurance at Ohio-average assumptions.
- At 75 percent LTV: coverage lands around 0.7x, well below the 1.00 baseline most standard programs are built around.
- At roughly half of value: the number sits just under or right around 1.00.
- Somewhat below half: coverage moves modestly above 1.00, which is where standard lender review starts to look clean.
The 75 percent ceiling is a maximum, not a target. Proceeds also depend on rent used for lender review, reserves and the property review, so the cash figure is never guaranteed.
What if the number falls short of 1.00? Some lenders review sub-1.00 structures, interest-only options or reduced-leverage tweaks, but these typically come with stronger credit, more reserves or a smaller loan. Qualification remains subject to lender guidelines, credit approval and property review. Before pushing for sub-1.00 on a Powell house, ask whether a smaller cash-out solves the problem more cleanly. In this market it usually does.
This one is a genuine judgment call. A longtime owner with a low existing balance can hit a workable ratio and still pull meaningful capital, because the payoff is small relative to value. An owner with a recent, highly leveraged purchase cannot. That difference matters more than the rent.
The parameters worth knowing typically run like this, subject to lender guidelines and varying by borrower and property: a credit floor of 620 with better tiers at 660, 680 and 700, reserves of about six months of PITIA, and loan sizes up to $3,000,000 on standard programs. For the mechanics behind those, the DSCR fundamentals cover the basics.
What a Typical File Looks Like
DSCR files in markets like this one typically look like a single asset with a strong appraisal story and a modest rent story. The cleanest file has complete leases, entity documents where applicable, title and property details ready for lender review, and a rent schedule the appraiser can defend. Where rental comps are sparse, that schedule matters more, because the appraiser may lean on a handful of listings and land below the rent the owner expects. Investors who plan for a range rather than a single hoped-for number have far fewer surprises.
If the property is titled in an LLC, eligibility is subject to lender program requirements, so sort out the entity structure before the file goes out.
Where the Files Actually Pencil
No source gave neighborhood-level rents or prices, so the differences below are about product type and tenant profile, not numbers. Everything here uses the citywide figures above.
Historic Downtown and Village Green. This is the walkable core, with locally owned restaurants, boutiques and a weekend outdoor refreshment area. Per Ludwig Real Estate Group, it draws professionals and downsizers who want walkability. Housing runs from downtown homes and condos to established subdivisions. Condos and townhomes here are the closest thing Powell has to a DSCR-friendly product, since the lower entry price improves the rent-to-value picture, though the citywide numbers are all the research supports.
Golf Village and Wedgewood. Golf Village is an established subdivision, and Wedgewood pairs mature trees with a golf and country club. These are owner-occupier enclaves. A rental there is a niche product, which helps scarcity but limits comps. New apartments have also opened nearby: Homes.com lists The Residences at Golf Village as brand new. RentCafe shows apartment rents down 1.89 percent over the past year, from $1,842 to $1,807. That competition is aimed at condo and townhome renters more than at single-family houses, so the pressure lands unevenly across property types.
The Liberty Township zoo corridor. The Columbus Zoo and Aquarium and Zoombezi Bay sit in the township’s southwestern corner, and homes there average about 33 days on market per Homes.com. The zoo is a seasonal employer and local anchor, though no verified headcount exists. Treat it as demand support, not a coverage driver.
Wider employment anchors. Columbus Region lists JP Morgan, McGraw Hill, Showa and Anthem BlueCross BlueShield as county employers, with Delaware County home to 234,832 residents. Directory sources also name OhioHealth and Nationwide Children’s Hospital as regional employers, without headcounts. And Homes.com reports that Ohio State’s $183 million Outpatient Care Powell is set to open, the first named healthcare investment inside the city. It supports demand qualitatively, and nothing more.
Skip the Appreciation Bet.
Powell is appreciation- and commute-led, not cash-flow-led, and the appreciation has stalled. Redfin shows the median sale price down 5.2 percent year over year, with homes averaging 106 days on market against 90 the year before. That is a January reading on 12 sales, so it is a thin sample. Prop-Metrics is less dramatic: a 0.4 percent year-over-year decline, 31 median days on market and 26 percent of listings with price reductions.
Both point the same way. A cash-out can’t count on future appreciation to lift the appraised value, so size proceeds to today’s value with a cushion. Pricing dispersion adds to the problem. Resideline tracked 214 closings with a median of $642,500, and the middle half closed between $490,000 and $830,000. That median reflects a different window and sample than Redfin’s $576K, so the appraised value depends heavily on which comps the appraiser picks. Owners below the median should expect a different rent-to-value ratio than the citywide figure.
Take the Proceeds Somewhere Else
Here is the practical problem with reinvesting inside Powell: there is almost nothing to buy. Point2Homes shows no multi-family listings in the city. Only 1.0 percent of local mortgages were investor loans per HUD data via Prop-Metrics. Duplex, triplex and fourplex stacking, which is how investors usually rescue thin coverage, isn’t realistically available here.
Investors who want multi-unit coverage generally have to look in Delaware city, the county seat, where a duplex listing showed a unit rented at $1,500. Rent per unit is lower, but the price per door is far lower too. That is the classic play for Powell equity: pull capital from a high-value, low-yield asset and redeploy into higher-yield stock nearby. For how the refinance side fits, Lendmire’s guide to pulling equity with a DSCR cash-out walks through the structure.
The thesis holds only if the target market clears its own coverage test. Pulling equity to buy somewhere the numbers also don’t work just moves the problem. And if the goal is a stable single property with modest leverage, the guide “Where DSCR and Conventional Diverge” is worth reading first. A high-income W-2 owner with one Powell rental may find conventional financing cleaner, while DSCR becomes the practical lane for entity-held portfolios or files where personal income doesn’t tell the story. More on the state picture sits with Ohio DSCR financing, and investors who want to model a specific Powell property can talk through the numbers or call 828-256-2183.
Frequently Asked Questions
How much equity can I realistically pull from a Powell rental?
Less than the 75 percent cap implies. Coverage on a typical Powell house runs well below 1.00 at maximum leverage once taxes and insurance are counted, so the practical limit is usually the loan size at which rent covers the full obligation. Owners with a small existing balance keep the most flexibility. Final proceeds depend on rent used for program review, reserves and eligibility review.
Does the six-month seasoning rule matter for a Powell purchase?
Yes, if you bought recently. Seasoning typically runs about six months from title recording, and cash-out proceeds are generally sized to the appraised value rather than to what you paid. In a market where median prices have softened, a recent buyer can find the appraisal lands at or below the purchase price, leaving little to extract.
DSCR vs. conventional financing
Two common ways to finance an investment property in Powell, OH. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Will thin rental comps hurt my appraisal?
They can. With roughly 11 percent of households renting, the appraiser’s rent schedule may rest on a small set of listings, and published rent figures for Powell range from about $2,326 to $3,499. Plan for a conservative rent figure and check that the coverage still works.
Can I use Powell cash-out proceeds to buy a duplex nearby?
Yes, but not inside Powell, where multi-family listings are essentially absent. Delaware city is the nearest realistic source of 2-4 unit stock. Proceeds are your capital to deploy, and the new property will be underwritten on its own rent and obligation.
Is Powell a good fit for a sub-1.00 coverage structure?
It may come up more here than in most Ohio markets, since coverage is thin at higher leverage. Some lenders review sub-1.00 programs, typically with reduced leverage, stronger credit or more reserves. Reduce the loan first, and treat sub-1.00 as a fallback rather than a plan.
The Blind Spot Worth Naming
The biggest risk for DSCR-financed investors in Powell is treating a large appraisal as proof of a workable deal. Value here is driven by owner-occupier demand, while the rent side is a small, contested pool. Prices are softening, new apartment supply is opening at the edges, and the coverage math punishes leverage. Investors who size the loan to rent instead of to value, keep a cushion for a lower appraisal and verify current local rental rules, taxes and insurance with qualified local professionals will be fine. Those who pull to the cap and assume the market will catch up may find that in Powell, a high-priced owner suburb, it doesn’t.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a mortgage brokerage focused on investor financing, arranging DSCR loans in 40 states plus Washington, D.C. — 41 markets total. Qualification is based on the property’s income rather than personal income documentation, subject to lender guidelines, making it a fit for LLC-held rentals and scaling portfolios.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. RentCafe, Powell rent trends
2. a 2026 Scotsman Guide Top Mortgage Workplace
3. a 2025 Scotsman Guide Top Workplace
4. Redfin, Powell housing market
6. Census Reporter, Powell profile
7. Ohio-Demographics.com, Powell demographics
9. Homes.com
10. Zumper, Powell rent research
12. Homes.com
14. Homes.com
15. Columbus Region, Delaware County
16. OhioHealth
17. Nationwide Children’s Hospital
19. Resideline, Powell housing market
20. Point2Homes
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance Powell Ohio · Cash Out Refinance Investment Property in Columbus OH · Cash Out Refinance Investment Property in Westerville OH
Guides: Investment Property Cash-Out Refinance in Ohio
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.