
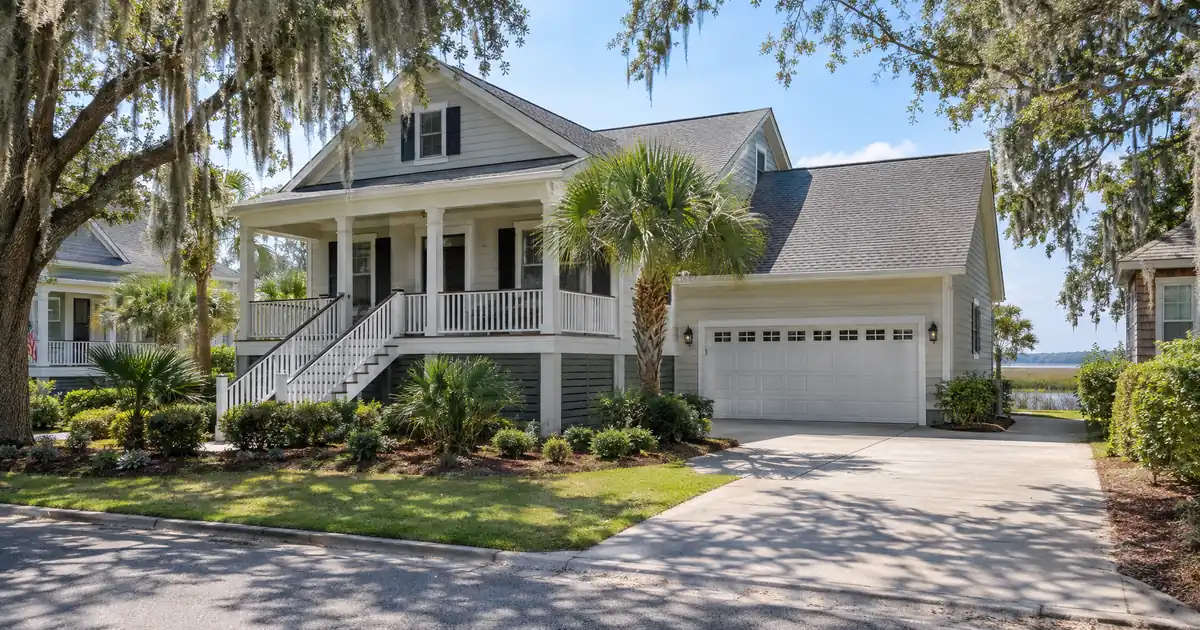
Picture two Edisto Beach owners. One bought a house on the oceanfront strip with a large down payment and carries a balance well under half of today’s value. The other bought a smaller attached unit near the marsh with a thin cushion and is counting on appreciation to build the equity. Cash out refinance investment property math here favors the first owner by a wide margin. Proceeds are sized off a 75% LTV ceiling and an appraisal that may not keep rising. Data USA puts the Census-based median value at $719,200, up 17.8% in a year. Zillow’s home value index shows values down 2.1% over the past year. Coverage is the harder half of the problem, and most of what follows deals with it. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
At a Glance: A cash-out refinance in Edisto Beach, South Carolina is underwritten primarily on the property’s rental income measured against its full monthly obligation, so a small renter pool and high home values make the appraiser’s market-rent schedule and the 75% LTV ceiling the two inputs that decide how much equity actually comes out. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
DSCR Cash-Out Calculator
Run the cash-out numbers in Edisto Beach, SC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 1, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 1, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Only 11.7% of occupied units are renter-occupied, per Point2Homes.
- Median gross rent sits far below the median home value, which is high relative to local rents.
- Modeled coverage on island-wide asking rents, including full principal, interest, taxes, and insurance, lands well below 1.00, so many Edisto Beach properties would struggle to qualify on long-term rent alone.
- Proceeds depend on about 6 months of seasoning and a 75% LTV ceiling, not on past appreciation.
- Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Edisto Beach Market Snapshot
A quick read on the Edisto Beach investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $719K median (Redfin Edisto Beach Housing) |
| Typical rents | $1,170 (Point2Homes) |
The Oceanfront Strip: Big Equity, Dispersed Comps
The oceanfront and beachfront strip is where Edisto Beach’s equity sits, and where cash-out proceeds are easiest to size on paper. It is also where comparable sales spread the widest, which is the main appraisal risk on a refinance in a town this small.
The scarcity story is real. Vacasa calls the beach one of the last uncommercialized stretches in South Carolina. The Town of Edisto Beach describes itself as one of the few remaining family-oriented, gently developed beaches on the state’s eastern coastline. The Edisto River, one of North America’s longest free-flowing blackwater rivers, ends its 206-mile run to the Atlantic here. That scarcity supports land value. It does not automatically support rent.
Comps are the catch. Redfin’s market data lists a recent oceanfront-area sale at $1.1M and an interior sale at $600K, inside one tiny town and on a small number of transactions. The average home sells about 4% below list and goes pending in roughly 58 days. An appraiser handed that spread may pull older or off-street comparables. That adds valuation risk to a cash-out, because proceeds are a percentage of whatever number the appraisal returns.
The oceanfront owner with a low balance can absorb that risk. The one who bought near the top of the range and leveraged heavily cannot. Not ideal.
There is also a flip point. If the thesis for a beachfront house is long-term hold, family use and eventual sale, pulling cash out at all may be the wrong move. Coverage will not carry the debt, and the equity is doing its job where it sits.
Wyndham Ocean Ridge and the Attached-Unit Lane
Attached product is the closest thing Edisto Beach has to small-multifamily inventory, and it is not much. Duplexes and townhomes make up only a sliver of stock, so a conventional “2-4 unit” cash-out strategy is not realistic here.
Point2Homes counts 2,219 housing units in town. Of those, 73.2% are detached single-family homes and 7.1% are attached options such as duplexes and townhouses. By simple arithmetic, that is roughly 150 attached units. Most of the duplex-style inventory sits inside the Wyndham Ocean Ridge resort community, which also has cabins and condos and a golf course. Wyndham Vacation Ownership appears on the SC Department of Employment & Workforce Colleton County profile as one of the county’s largest employers. That makes the resort both a source of housing and a source of hospitality jobs.
For a cash-out, attached units pencil differently from detached houses. Census-derived data shows attached and two-unit structures trading well below detached houses, so the same 75% LTV ceiling produces a smaller absolute pool of equity. Coverage can look better because the price base is lower. Lenders also tend to add property-level review on condo and attached projects, and that review varies by program. Investors holding resort units should expect that extra layer and plan around it.
Smaller pool, cleaner coverage. Whether that trade works depends on what the proceeds are for.
Marsh Side and Interior Streets (The Closest Thing to Workable)
Off the beach, the coverage math gets closer to workable, though it still does not clear 1.00 on most single-family structures. The interior residential streets and the marsh side along Big Bay Creek and the South Edisto River are the quieter, walkable-to-the-beach parts of town, and they carry the lower end of the price range.
The best directional rent evidence is island-wide, not town-only. Zillow’s rental listings show about ten 3-4 bedroom houses asking between $1,800 and $4,100 a month, with several clustered at $2,400, $2,800 and $3,500. Those listings mostly sit beyond the beach town limits, so treat them as a directional read, not comps. Against a purchase or appraised value of $700K to $790K, even $3,000 to $3,500 of rent is only about 0.4% to 0.5% a month. The Census-based gross rent medians, $1,170 at Point2Homes and $1,136 at Niche, imply roughly 0.16% a month on a $719,200 value. That ratio is Lendmire Research’s own arithmetic. The Census numbers reflect older leases and a very small renter base, not what a newly acquired house would rent for.
Price depends on which area gets counted. Movoto shows a beach-only median listing price of $789K with 16 homes for sale. A Locating Charleston market report covering Edisto Island and Edisto Beach together shows a $475,000 median across 16 active listings, 94% of them single-family. These are broker and portal snapshots, and the gap between them shows how much a refinance appraisal depends on where the appraiser draws comps.
Honestly, the older off-beach house is probably the better cash-flow candidate than the oceanfront one. Exit liquidity is lower. Coverage is meaningfully better. Investors buying for scarcity-driven appreciation could argue the other way, and they would not be wrong.
Who Actually Rents in a Town of 1,080?
A very small group does, and that is the single biggest underwriting fact in this market. Edisto Beach is overwhelmingly owner-held and seasonally occupied, so the long-term renter pool is a few dozen households, not a market with depth.
World Population Review puts the population at 1,080, up 4.96% from 1,029 at the last Census count. Point2Homes reports that 88.3% of 562 occupied units are owner-occupied and 11.7% are renter-occupied, which works out to roughly 66 renter households. It also reports that 74.7% of all housing units are vacant. That is seasonal and second-home use, not long-term rental vacancy.
Demand is not employer-driven or student-driven, and there is no university or hospital in town. Data USA shows 452 employed residents, led by Professional/Scientific/Technical Services (56), Accommodation & Food Services (49) and Real Estate & Rental & Leasing (44). The average commute is 27.5 minutes. Charleston is about 28.7 miles away per City-Data, and the airport is about 42 miles from the center of the island according to SCIWAY. The nearest hospital is Colleton Medical Center in Walterboro. Long-term tenants here are mostly hospitality and service workers, resort staff and households tied to the Charleston metro.
An appraiser’s rent schedule in a pool this small is built on very few data points. That makes rent documentation, and the lease behind it, matter more than it would in a metro with thousands of comps.
Three Valuation Signals That Disagree
Every cash-out starts with an appraisal, and the public value signals for Edisto Beach point in different directions. The investor should assume the lower reading, not the higher one, when sizing proceeds.
| Source | Figure | Direction |
|---|---|---|
| Data USA (Census-based) | $719,200 median value | Up 17.8% in a year |
| Zillow index | $734,201 average | Down 2.1% |
| Redfin sales data | $719K median sale | Down 4.1% |
The survey-based Census figure and the transaction-based portal data measure different things. Redfin also reports a median price per square foot around $500, down 2.2%, which fits a flat-to-soft market. I treat the portal readings as closer to what an appraiser will see, because appraisers work from closed sales.
Run the numbers on an investor who bought with 30% down and still carries a balance near 70% of the original purchase price (modeled assumption, ignoring paydown). If the appraisal comes in flat, the 75% ceiling leaves room of about 5% of value before closing costs and reserves. If value matches the Census jump of 17.8%, room expands to roughly 18% of the original purchase price. If the appraisal lands 4.1% lower, as Redfin shows, room shrinks to about 2%. Same house, same borrower, and a sliver of equity left. Stress-test at the low end. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Seasoning matters too. Cash-out programs typically look for about 6 months of ownership measured from title recording, and a freshly bought house does not qualify as a refinance candidate until that clock runs. An investor who bought recently and relies on the purchase price as proof of value is exposed to a thin appraisal. Subject to lender guidelines, the appraised value governs, not the contract price.
Rent Is $3,000. Value Is $719,200. Now What?
Coverage below 1.00 is the default on most detached houses in Edisto Beach, not the exception. Using a modeled rent of $3,000 to $3,500 against a $719,200 value at the 75% ceiling, and counting full taxes and insurance, coverage lands roughly 0.7 to 0.8. Those are modeled inputs, not market comps. On a lower-priced off-beach house near the $475,000 island-wide listing median, with rent around $2,400, the number improves to the low-to-mid 0.8s. Still short.
DSCR is rent divided by the full monthly obligation: principal, interest, taxes and insurance. A ratio of 1.00 is the point where rent just covers that obligation, and it is the floor only on select programs. Some lenders review lower ratios, but those usually come with stronger compensating factors, lower leverage, different pricing or more cash. Below 1.00, a few paths exist that a lender would review:
- A sub-1.00 program. Select lenders in the network allow it, typically with reduced leverage and stronger credit.
- Lower leverage. Pull the cash-out LTV toward 50% and coverage on the same rents moves toward 1.00, though the taxes-and-insurance component does not shrink.
- Interest-only structuring. This can lift the ratio on paper at the cost of no principal paydown.
- A stronger appraisal rent schedule. If the appraiser supports a materially higher market rent for a renovated or better-positioned house, the ratio moves with it.
All of these depend on the borrower, the property and the lender, and none is an approval. Before reaching for sub-1.00, ask whether it should be used at all. If the property has a scarcity-driven appreciation story and the borrower has strong credit and reserves, a sub-1.00 structure is defensible. If it is the only way a standard-leverage deal pencils, that is a signal to rethink the asset, not the loan type.
DSCR files in markets like this one typically look like a high-value asset with a short rental history and a thin comp set. The coverage number is usually the second question. The first is whether the appraiser can support a rent figure at all. Files tend to go better when the borrower has a signed lease or a documented rental history, a recent insurance quote in hand, and an appraisal order that specifies the rent schedule up front. Surprises usually come from a valuation that comes in lower than the owner’s mental number.
Conventional financing may win outright for some borrowers. A W-2 borrower with strong income and one or two financed properties often does better on a conventional versus DSCR comparison, because personal income can carry a debt that the property’s rent cannot. DSCR becomes the practical lane when the borrower is self-employed, holds property in an LLC (subject to lender program eligibility), or has scaled past conventional financed-property limits. For anyone new to the structure, the guide “What Is a DSCR Loan” covers the mechanics.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Edisto Beach, SC, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Where the Proceeds Go
The cash-out thesis depends on what the money does next. Pulling equity from an Edisto Beach house to buy a property where rent clears the payment is an easy argument. Pulling it to hold more low-coverage coastal assets is a different decision, and it should be stress-tested before committing.
Inland Colleton County has the stronger long-term-renter story. The SC Department of Employment & Workforce lists the county’s largest employers alphabetically, without rankings or headcounts. They include Walterboro Community Hospital, Wal-Mart Associates, Food Lion, Gehl Foods Southeast, Cracker Barrel and PruittHealth Walterboro. That is a workforce base of healthcare, retail and food production, a more conventional foundation for small rental stock than a resort town. Walterboro sits roughly 30 miles inland. Lendmire Research did not underwrite its prices or rents, so any move there needs its own coverage test.
Reserves are the other constraint. Programs typically look for about 6 months of PITIA in reserves, and about 9 months on balances above $1,500,000. On a high-value edisto house that is a meaningful cash requirement, and it comes out of the same equity the investor is trying to pull. Credit tiers start at a 620 floor, and loan amounts run up to $3,000,000 on standard programs, subject to lender guidelines. Details on the mechanics are in “The Refi Options” and the investor refinance breakdown. The DSCR loan options for South Carolina investors page covers statewide program detail. Investors with questions on a specific file can reach Lendmire at 828-256-2183.
One reminder specific to coastal property: verify current local rental rules, taxes, flood exposure and insurance with qualified local professionals before underwriting. Edisto Beach has all of them.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance on an Edisto Beach rental?
Qualification centers on the property’s rental income against its full monthly obligation, not the borrower’s W-2s. Because the renter pool is so small, the appraiser’s market-rent schedule and any lease documentation carry unusual weight. Credit, reserves, seasoning and the 75% LTV ceiling all apply, subject to lender guidelines and property review.
What are the requirements for an investment property cash-out refinance in Edisto Beach, South Carolina?
Typical guidance is a 75% maximum LTV on cash-out, about 6 months of ownership from title recording, a 1.00 DSCR benchmark, a 620 credit floor and about 6 months of PITIA in reserves. Loan amounts run up to $3,000,000 on standard programs. Manufactured homes, log homes and barndominiums fall outside these programs. Exact eligibility varies by borrower, property and lender.
Does falling value in Edisto Beach reduce my cash-out proceeds?
Yes, directly. Proceeds are a percentage of appraised value minus the existing payoff, so a lower appraisal shrinks the cushion first. With Zillow showing values down 2.1% and Redfin down 4.1%, an investor should model a flat-to-lower appraisal, not a Census-style jump.
Is a duplex or fourplex strategy realistic in Edisto Beach?
Not really. Attached units are only about 7.1% of the housing stock, and most duplex inventory sits inside the Wyndham resort. Single-family houses, townhomes and condos are the realistic property types. Small multifamily is better sought inland.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
One Last Comparison
Against inland Walterboro, where hospital and retail employers point to steadier workforce renters, Edisto Beach is the better store of equity and the weaker engine of coverage. The math favors pulling cash out of Edisto only when the balance is low, and putting it to work where rent carries the payment.
About Lendmire
Lendmire is a DSCR-focused mortgage brokerage, NMLS# 2371349, placing investor loans across 41 markets, including Washington, D.C. Lenders in the network generally review eligibility around a property’s rental income rather than personal income documentation, which suits LLC-held rentals, self-employed investors and portfolios past conventional financed-property limits. Lendmire is recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2025.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Data USA
3. Point2Homes
5. Vacasa
7. SC Department of Employment & Workforce Colleton County profile
9. Niche
10. Movoto
11. Locating Charleston market report
13. City-Data
14. SCIWAY
15. a 2026 Scotsman Guide Top Mortgage Workplace
16. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Edisto Beach, South Carolina: How the Rent Math Clears at 75% LTV · Cash Out Refinance Investment Property in Surfside Beach, South Carolina: The 2026 DSCR Guide to Ocean Blvd · Cash Out Refinance Investment Property in Murrells Inlet, South Carolina: 2026 DSCR Guide to Marsh Walk Equity
Guides: Investment Property Cash-Out Refinance in South Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.