
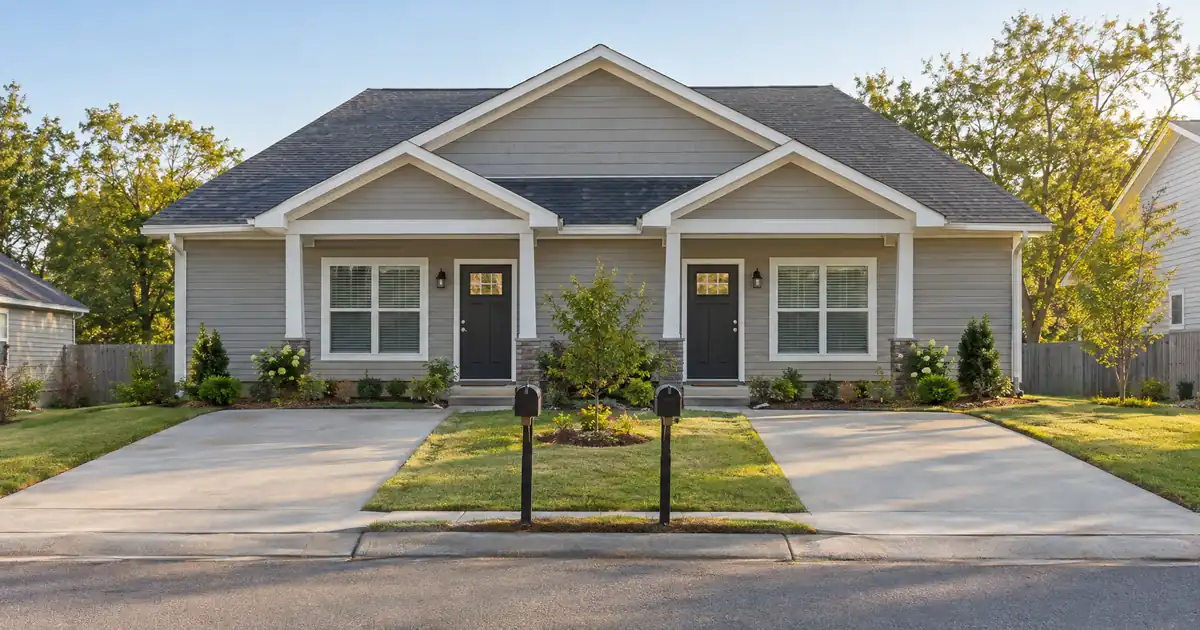
The Quick Read: A duplex loan is jumbo only when the loan amount passes the county’s limit for two-unit homes. That limit is higher than the one for a single-family house. Once a loan is jumbo, the lender sets its own rules. Verified traditional employment income, a clean credit file, cash reserves, a solid down payment and an appraisal that supports the price decide the outcome. Every figure here is subject to lender guidelines and full file review, and nothing is a commitment to lend.
Key Takeaways
- Jumbo status depends on the loan amount, not the price. It also depends on the county and the number of units.
- Across the wholesale programs Lendmire places files with, the headline lane starts at a 660 decision score. Leverage reaches 90% on some lanes, and loans reach $5,000,000 on the largest.
- Rent from the unit you do not live in rarely offsets the payment dollar for dollar. Many high earners qualify on traditional employment income alone.
- Reserves and appraisals scale with the loan amount. A two-unit purchase asks more of the file than a one-unit home.
- Occupancy matters. Living in one unit puts you in a different lane than renting out both.
Is Your Duplex Loan Actually Jumbo?
Start with the loan amount, not the price. A jumbo loan begins one dollar above the conforming limit for your county. Above it, the lender keeps the loan or sells it to a private investor.
Jumbo payment estimate
The starting figures are an example price in the jumbo range with ten percent down on a thirty-year fixed. Replace them with yours.
Editable benchmark: 7.40% as of October 15, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not a jumbo loan quote.
Illustrative starting assumptions: a $1,000,000 price in the jumbo range, ten percent down on the top-leverage lane, a thirty-year fixed structure at the current Freddie Mac conforming benchmark, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conforming benchmark, a market reference and not a jumbo loan quote; jumbo rates are set by the lender and the lane at lock and differ from the conforming benchmark. An adjustable-rate scenario is shown at the benchmark for the whole term; the rate after the initial period is unknown. Reserve months and appraisal counts follow the lane sheet for the amount band; the automated finding may require more. Taxes, insurance and dues are editable estimates; closing costs are not included. On most lanes the conforming limit for the county decides whether a loan is jumbo at all; two lanes start at a stated dollar floor instead. Licensed in sixteen states for consumer mortgages.
Duplexes get a break here. Two-unit properties carry a higher limit than one-unit homes, and the limit is set county by county. The same duplex price can be conforming in one county and jumbo in the next. This is why a buyer in a pricey metro sometimes stays under the line while a buyer in a mid-priced county does not.
The lookup takes three steps:
1. Find the county where the duplex sits.
2. Pull the two-unit limit from the county table.
3. Compare it to your loan amount after your down payment.
The limit resets every year, so check the current figure rather than relying on a number in an article. The Federal Housing Finance Agency publishes the county table.
One more wrinkle: a loan between the standard and high-cost limits can be “conforming high-balance” rather than jumbo. A larger down payment can also pull a loan under the line. If you are close, the difference between the two paths is worth a real comparison. More on that below.
If you want to see the program options side by side, Lendmire’s jumbo loan programs page lays out the lanes. Those include fixed, adjustable and interest-only structures.
How a Jumbo Duplex Loan Gets Underwritten, Step by Step
Underwriting is the lender’s check that you can repay the loan and that the property backs it up. Here is the sequence on a two-unit purchase.
Step 1: Occupancy and property type
You live in one unit. That makes the property a two-unit primary residence. Lenders treat it differently from a one-unit home and from a full rental. Occupancy also sets leverage. Primary, second-home and investment use each carry their own leverage on a given lane.
Step 2: Income
For a W-2 buyer, the file starts with pay stubs, W-2 forms and an employment verification. Base salary is the easy part. Bonus, commission and stock-based pay take more work. Lenders usually want a history of that income and often average it over a stretch of time. A recent job change is not an automatic problem, but expect more questions.
High earners get a boost here, but income alone does not carry the file. The lender checks the whole picture.
Step 3: The other unit’s rent
This is where buyers get tripped up. Under Fannie Mae’s guide, rental income from the unit you occupy generally cannot be used. The full payment on the home counts as a debt. Fannie Mae separately lets lenders consider rent from the subject property on a two- to four-unit primary residence.
Jumbo loans are not bought by Fannie or Freddie, so each lender chooses. In practice a lender may count part of the rent, cap it, ask for a lease, or ignore it. When it counts, it counts only a portion of the gross rent. Agency guidance builds in a haircut for vacancy and expenses.
Fannie Mae also says rental income can only be used if the borrower owns a principal residence or has a current housing expense. A buyer coming from a family home rent-free may find the rent removed.
My honest read: for a high-earning W-2 buyer, treat the rent as a bonus. Qualify on your income and let the other unit be cash flow you earn after closing.
Step 4: Appraisal
A two-unit purchase uses an appraisal form built for small income properties, which includes comparable rents. Duplex comparables are scarcer than single-family ones. That can narrow the value range the appraiser has to work with. Above a lane’s threshold amount, the program calls for two appraisals. A larger duplex loan can trigger that.
Step 5: Reserves
Reserves are the cash you keep after closing. On jumbo lanes they are measured in months of the full payment, and the count rises with the loan amount. Agency loans already ask for reserves on a two- to four-unit primary residence that a one-unit home does not need. Jumbo lanes layer their own requirement on top.
Step 6: Credit, leverage and ratios
Across the wholesale lanes Lendmire works with, the headline lane starts at a 660 decision score. A higher score tends to help with leverage and flexibility. Leverage reaches 90% on the strongest lanes. Several lanes stop at 89.99% combined loan-to-value, and the rest stop at 80%.
The ratio ceiling is the debt-to-income limit, meaning your monthly debts divided by gross monthly income. It sits at 50% on the fixed lanes, 45% on the adjustable lanes and 43% on the interest-only lanes.
| Factor | What it means on a duplex |
|---|---|
| Credit | 660 decision score on the headline lane |
| Leverage | Up to 90% on some lanes; 80% on others |
| Ratio ceiling | 50% fixed; 45% adjustable. Pricing and available terms vary by lender, borrower profile, property type, and full underwriting review. |
| Reserves | Months of full payment, rising with amount |
| Appraisal | Two above a lane’s threshold amount |
Structures and Variations
Fixed, adjustable and interest-only structures all exist in the jumbo space. Each lane has its own leverage and ratio ceiling, as shown above. The tradeoff is simple. A lane that allows more leverage usually asks more from credit, reserves or both. A lane with a lower ceiling may suit a buyer with large monthly debts.
Condominium duplexes are a separate question. Two lanes accept non-warrantable condominiums, meaning projects that fall outside standard agency project rules. That matters if your two-unit property sits inside an association with unusual features.
Where the General Rule Breaks
Rules of thumb fail at the edges. These are the ones I see most.
- A loan just above the line. A bigger down payment can make the loan conforming. Compare that path before choosing jumbo. A loan above the standard limit but below the high-cost one may be high-balance conforming.
- Special-limit areas. Alaska, Hawaii, Guam and the U.S. Virgin Islands have their own, higher limits, set by statute.
- No current housing expense. As noted, rent may not be usable if you have no existing housing cost.
- Short-term rental of the other unit. Fannie Mae has created a separate topic for short-term rental income from the subject property. Jumbo lenders often treat it more cautiously than a standard lease.
- Occupancy shifts. If you plan to move out in a year, tell the lender up front. Occupancy rules decide leverage.
- FHA as a stepping stone. FHA allows two-unit purchases up to its own limits tied to the conforming limit. A jumbo buyer sits above those.
A jumbo loan can be a qualified mortgage or a non-qualified one. Higher-priced loans can lose a legal safe harbor. A first-lien jumbo crosses the higher-priced threshold at a larger spread than a conforming loan. Either way, the lender must document that you can repay. That duty is why high income does not guarantee approval.
A Worked Example
Picture a salaried buyer with a base salary plus a yearly bonus. She plans to live in one side of a duplex and rent the other. She puts 20% down. Her other monthly debts are modest. Terms depend on the lender’s guidelines, the property type, the leverage, and a full review of the credit profile.
Step by step, the lender:
1. Averages the bonus over its history and adds it to base pay.
2. Counts the full payment on the duplex as her housing debt.
3. Credits little or none of the rent from the second unit.
4. Divides her total debts by her gross income and compares the result to the lane’s ceiling.
5. Checks her reserves against the lane’s month requirement.
6. Orders the appraisal, with a second one if the amount is above the lane’s threshold.
If her ratio lands under the ceiling and the reserves cover the months required, the deal works forward. Suppose it lands over. She has three levers: pay down a debt, add cash to the down payment, or move to a lane with a higher ceiling. Each has a cost. A bigger down payment cuts reserves, for example.
Stay Conforming or Go Jumbo?
This one is close to a toss-up for many buyers. A conforming loan has fewer overlays and a broader lender pool. A jumbo loan can cost more, as the CFPB notes, but it can also let you keep more cash in hand with a smaller down payment.
Ask three questions:
- How far above the limit am I?
- Would a larger down payment drop me under it, and what would that do to my reserves?
- Do I want the cash for the renovation, the other unit’s turnover or an emergency fund?
If you sit just over the line, run both paths. If you are well over it, jumbo is the only road.
Pre-Application Checklist
Gather these before you apply:
- Two years of W-2 forms and recent pay stubs.
- Bonus, commission or stock-pay history, with vesting statements.
- Bank and brokerage statements for your down payment and reserves.
- A list of current debts and your housing history.
- Leases for the second unit, if it is already rented.
- The gift-fund documentation, if a relative is helping. Eligible gifts can count toward reserves, but gifts of equity cannot.
Tax treatment can depend on your situation; borrowers should speak with a qualified tax professional before relying on any deduction or credit.
Key Terms Defined
Final terms depend on the lender’s guidelines, the property type, and the borrower’s complete credit picture.
Jumbo loan: A mortgage above the conforming limit for that county and property type.
Debt-to-income ratio: Your monthly debts divided by your gross monthly income.
Reserves: Cash you hold after closing, measured in months of the full mortgage payment.
Combined loan-to-value: All loans on the property divided by its appraised value.
Non-warrantable condominium: A condominium project that falls outside standard agency project rules.
What to Do Next
If you are buying a home and want to see whether a jumbo loan fits your file, Lendmire can help you compare the options and what each one asks of the file.
Frequently Asked Questions
Is a duplex loan automatically jumbo?
No. Two-unit properties carry a higher limit than one-unit homes, and the limit varies by county. A loan becomes jumbo when the total loan amount is above that limit, so a loan at or below it is not jumbo.
Can the rent from the other unit help me qualify?
Sometimes. Jumbo lenders choose how much rent to count, and many count a portion or none. A high-earning W-2 buyer often is reviewed on salary alone.
What credit score do I need?
The headline lane starts at a 660 decision score. A higher score tends to open more leverage and flexibility. Other lanes may ask for more. All of this is subject to lender guidelines and full file review.
How much can I borrow, and how much down is typical?
Loans reach $5,000,000 on the largest lanes. Leverage reaches 90% on some lanes, while several stop at 89.99% and the rest at 80%. Occupancy and loan size change what a given lane allows.
Do I need reserves for a duplex?
Yes. Reserves are measured in months of the full payment and rise with the loan amount. A two-unit home asks for more than a one-unit home.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
Lendmire — NMLS# 2371349 — is a mortgage broker that arranges FHA, VA, conventional and jumbo home purchase and refinance financing in 16 states through wholesale lenders. Every option is subject to the lender’s guidelines and full underwriting. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. FHFA – Conforming Loan Limit Values
2. Fannie Mae Selling Guide – Rental Income
3. Fannie Mae Selling Guide B3-3.8-02
4. Fannie Mae Quality Insider – rental income
5. Fannie Mae Selling Guide – Minimum Reserve Requirements
6. FHFA – 2026 Conforming Loan Limit Announcement
8. CFPB – What is a jumbo loan?
This article is part of Lendmire’s jumbo loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How Many Weeks a Jumbo Loan Takes for a High-Earning W-2 Buyer · Should a High-Earning W-2 Buyer Pass on Jumbo to Stay Conforming? · Should a High-Earning W-2 Buyer Put More Down on a Jumbo Loan?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.