
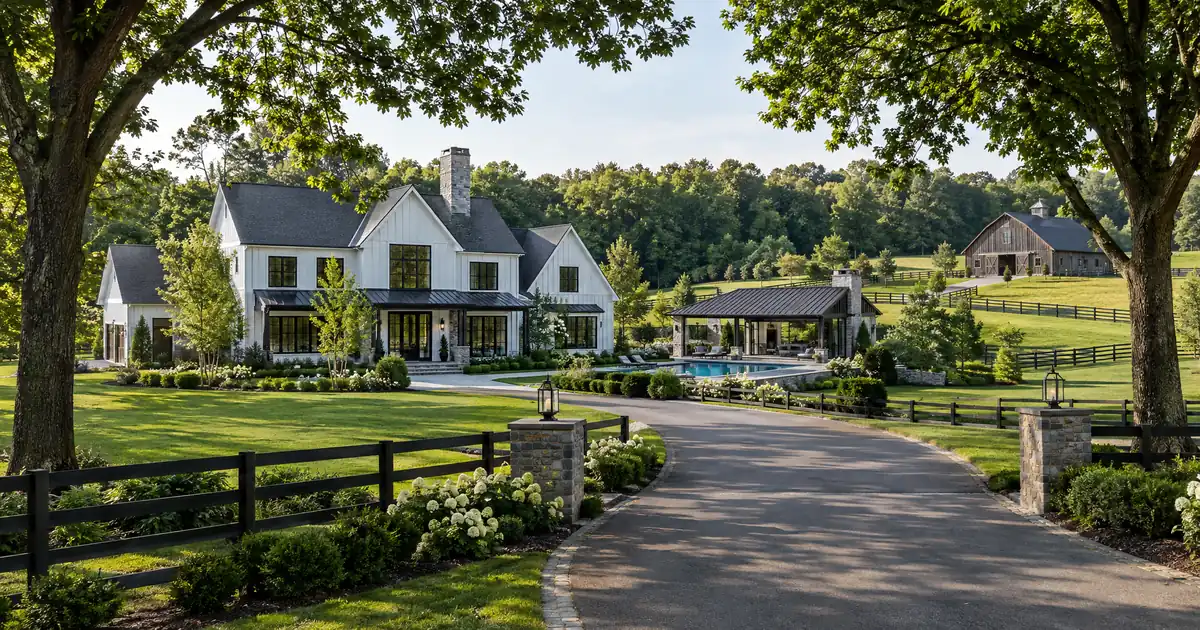
The Quick Read: Often, yes. A jumbo loan can finance a high-value home on large acreage when the property still reads as a residence and not a farm or a land investment. Loan size and property character are tested separately. A loan can be jumbo and still fail on the land, and a big parcel can pass when the home is clearly the point of the property. Eligibility depends on lender guidelines and full file review, and nothing here is a commitment to lend.
What Makes a Loan “Jumbo” When Acreage Is Involved?
A loan is jumbo when the amount sits above the conforming limit for the county. That is all the word means. Acreage does not change the label.
Jumbo payment estimate
The starting figures are an example price in the jumbo range with ten percent down on a thirty-year fixed. Replace them with yours.
Editable benchmark: 7.40% as of October 15, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not a jumbo loan quote.
Illustrative starting assumptions: a $1,000,000 price in the jumbo range, ten percent down on the top-leverage lane, a thirty-year fixed structure at the current Freddie Mac conforming benchmark, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conforming benchmark, a market reference and not a jumbo loan quote; jumbo rates are set by the lender and the lane at lock and differ from the conforming benchmark. An adjustable-rate scenario is shown at the benchmark for the whole term; the rate after the initial period is unknown. Reserve months and appraisal counts follow the lane sheet for the amount band; the automated finding may require more. Taxes, insurance and dues are editable estimates; closing costs are not included. On most lanes the conforming limit for the county decides whether a loan is jumbo at all; two lanes start at a stated dollar floor instead. Licensed in sixteen states for consumer mortgages.
FHFA sets the limit each year, and it differs by county and by unit count. FHFA’s 2026 conforming loan limit release shows a baseline for most of the country and a higher ceiling in high-cost areas, set at 150% of the baseline. Alaska, Hawaii, Guam and the U.S. Virgin Islands follow special provisions. County lookups are on FHFA’s conforming loan limit page.
Check the county first. A rural, high-value property can sit in a county whose limit is at the baseline, so the same house is jumbo there and conforming somewhere else. A jumbo loan begins one dollar above the county limit, so on Lendmire’s jumbo loan programs the loan amount, not the lot size, decides whether this lane applies.
Jumbo also does not mean non-QM. Jumbo describes size. Qualified Mortgage status describes how the loan is underwritten. Plenty of jumbo loans are fully documented with standard income and asset review.
Is There a Maximum Acreage?
There is no agency acreage cap, and that matters because jumbo lenders borrow the framework. Fannie Mae frames the question as use and typicality. Its Selling Guide site section requires a legal conforming use and warns that a site much larger than the comparables may not be a typical residential property.
Jumbo loans are not sold to the agencies. The wholesale lender sets its own property rules. Across the wholesale programs Lendmire places files with, many mirror the agency test of residential versus agricultural, and some add their own acreage or land-value overlays. Those overlays are the real variable. Ask about them before you pay for an appraisal.
The Three Gates a Land-Heavy File Must Pass
A land-heavy file passes three separate tests, and failing any one stops the file.
1. Loan size. Is the amount above the county limit? If yes, it is a jumbo loan.
2. Property character. Does the property read as a residence? Zoning, land use and the characteristics of the improvements decide this.
3. Collateral support. Does the appraisal support the price, and how much of the land counts toward value?
Income does not rescue a file that fails gate two or three. Strong deposits, high income and a clean credit profile address repayment. They do not change what the property is. Repayment-capacity review looks at your income or assets, debts, and property-related obligations like taxes and insurance, but acreage is not one of its factors, per the federal consumer-finance regulator’s repayment-capacity and Qualified Mortgage compliance guide. Acreage lives in the collateral test.
Here’s the catch on the second gate. A modest parcel in a remote area can fail where a larger parcel in a suburban area passes. Typicality for the area matters more than the acre count.
How Does the Appraiser Treat the Land?
The appraiser separates the home site from any excess land and picks comparable sales that match the property. The lender then decides eligibility from those facts.
Fannie Mae makes the appraiser responsible for choosing the best comparables, with similar physical and legal characteristics, in its comparable sales guidance. Thin comps are normal on acreage. They are also a common reason value support gets hard.
Land beyond what is typical for the area may be valued at little or nothing. Price per acre is not how the appraisal works. If you pay for 40 acres and the appraiser credits the home and a typical site, the lender uses the lower of price and appraised value for leverage. The gap becomes your cash.
That is the mechanical point. A low land value does not just shave the appraisal. It shrinks the maximum loan and raises the cash you bring to the table.
Where Does Each Situation Usually Land?
Directional outcomes only. Each depends on the lender’s overlays and the file.
| Situation | Likely outcome | Main obstacle | Usual fix |
|---|---|---|---|
| Suburban estate, large lot | Usually fits | Comps for the lot | Strong appraisal packet |
| Remote home, modest acreage | Can stall | Rural area, thin comps | Lender with rural comfort |
| Ranch-style, large acreage | Depends | Land value, overlays | Ask thresholds first |
| Working farm or ranch | Rarely fits | Agricultural use | Different loan type |
Worked Scenarios
Scenario one: it fits. A buyer purchases a home in a high-cost county on a lot larger than the neighbors but within what comparables show. The home is the dominant value. Zoning is residential. The appraisal lands at the price. The deal works on income, assets and reserves like any other jumbo file.
Scenario two: too much land. A buyer pays for a home on acreage far above anything nearby. The appraiser finds few like sales. Some lenders will not take the file at all. Others count only the home site. The buyer’s choices are a smaller loan, a lender with higher acreage tolerance, or splitting the parcel.
Scenario three: low appraisal on a large loan. The contract price is above appraised value because the land was bid up. Say the buyer planned on 80% leverage on price. If value comes in lower, 80% applies to the lower figure. The loan shrinks and the buyer funds the difference. Leverage on the wholesale jumbo lanes reaches 90% on the headline lane and stops at 80% on others, always subject to lender guidelines. A shortfall hits harder at higher leverage, so ask what the file needs before the appraisal is ordered.
Does Income Documentation Fix an Acreage Problem?
No. The tests run separately. Documentation proves you can repay. It says nothing about whether the collateral qualifies. A 660 decision score on the headline lane, leverage to 90% and loans to $5,000,000 on the largest lanes describe the borrower side of the envelope. A 50% ratio ceiling applies on the fixed lanes, with lower ceilings on the adjustable and interest-only lanes. Reserves scale with the amount, and two appraisals apply above a lane’s threshold. Those are borrower and loan tests. The acreage test sits next to them, not inside them.
For very high balances the cash picture grows too. Lendmire’s piece How Much Cash a Very High-Value Home Needs to Close on a Jumbo Loan covers the cash side of a jumbo purchase, which matters when land value comes in short of the price and you fund the gap.
If the Property Is Over the Line: Your Options
Treat an acreage problem as a collateral problem, not a credit problem. That changes the fix.
| Option | What it does | Trade-off |
|---|---|---|
| Shrink the loan | Lowers amount to supported value | More cash from you |
| Split the land | Removes excess acreage from collateral | Needs a legal split |
| Buy the home site only | Matches loan to residence | Seller must agree |
| Seller carryback on excess | Funds land separately | Needs seller cooperation |
| Different lender | Different overlays | Terms may differ |
No single option is best. A split is clean when local rules allow it. A smaller loan is simplest when you have the cash. Which one fits depends on how much of the price sits in land.
Primary Residence, Second Home or Investment: Does It Matter?
Yes. Occupancy changes leverage. The wholesale jumbo lanes handle primary, second-home and investment occupancy at lane-specific leverage, and a second home or investment property gets tighter terms than a primary residence. This article covers a primary residence. If your plan differs, say so up front because it changes the file.
Residential Estate or Working Farm?
The line is use. Large barns, silos and animal facilities can signal a farm. Small outbuildings do not disqualify a property when the residential character is clear. Freddie Mac’s Rural Properties FAQ sets no acreage limit, but treats farming or ranching use as ineligible.
Hobby farms and horse properties can be acceptable when the home is the main character of the property. A commercial operation changes eligibility. Guest houses and extra dwellings can raise questions, so list every structure before you start.
Pre-Offer Checklist
Do this before the offer or the appraisal order.
- Confirm the county loan limit and whether your loan clears it.
- Ask the loan officer for acreage thresholds and outbuilding limits.
- Ask which appraiser requirements apply, including rural experience.
- Pull the survey or parcel map and the zoning designation.
- List every outbuilding and secondary dwelling.
- Gather recent in-area sales that resemble the property.
- Confirm your reserves, since they scale with the loan amount.
Asking first costs nothing. An appraisal ordered on a file that fails an overlay costs real money.
Key Terms Defined
Jumbo loan: A mortgage above the county’s conforming limit.
Excess land: Acreage beyond what the home site needs, which an appraiser may value at little or nothing.
Residential site: The land that supports the home and is typical for the area.
Reserves: Liquid assets, measured in months of the full payment, held after closing.
Qualified Mortgage: A loan type defined by how it is underwritten, separate from loan size.
Frequently Asked Questions
Does a bigger lot make the home worth more to a lender?
Only up to what is typical for the area. Land beyond that may be valued at little or nothing, so the lender may count the home site and a reasonable lot and discount the rest.
Can I finance only the house?
Sometimes, if the land can be separated or the lender will count only the home site. A legal parcel split or a purchase of just the home site are the usual routes. Both depend on local rules and the seller.
What happens if the appraisal comes in low?
The loan is based on the lower of price and appraised value, so the maximum loan drops. You fund the gap or renegotiate. On a large loan the difference can be significant.
Do hobby farms qualify?
They can when the property still reads as a residence. A commercial farming or ranching operation changes eligibility. The lender decides, using its own overlays.
Can a conventional loan work if I’m only slightly over the limit?
If your loan amount sits at or below the county limit, it is not jumbo. If you are only slightly over, a larger down payment may bring the loan amount back under the limit. Check the county limit first.
If You’re Buying a Large-Acreage Home
If you are buying a home and want to see whether a jumbo loan fits your file, Lendmire can help you compare the options and what each one asks of the file. Tax treatment can depend on your situation; borrowers should speak with a qualified tax professional before relying on any deduction or credit.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
Lendmire, NMLS# 2371349, is a mortgage brokerage with consumer lending licenses in 16 states. FHA, VA, conventional and jumbo purchase and refinance loans are arranged through wholesale lending partners, and each application is reviewed individually by the lender. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. FHFA – 2026 Conforming Loan Limit Values
2. FHFA – Conforming Loan Limit data
4. Fannie Mae Selling Guide – Site Section
5. CFPB – ATR/QM Compliance Guide
6. Fannie Mae Selling Guide B4-1.3-08 Comparable Sales
7. Freddie Mac Rural Properties FAQ
This article is part of Lendmire’s jumbo loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Can You Get a Jumbo Loan on a Second Home With Little Income? · Can a High-Earning W-2 Buyer Get a Jumbo Loan on Acreage? · How to Qualify for a Jumbo Loan as a High Earner on W-2 Income
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.