
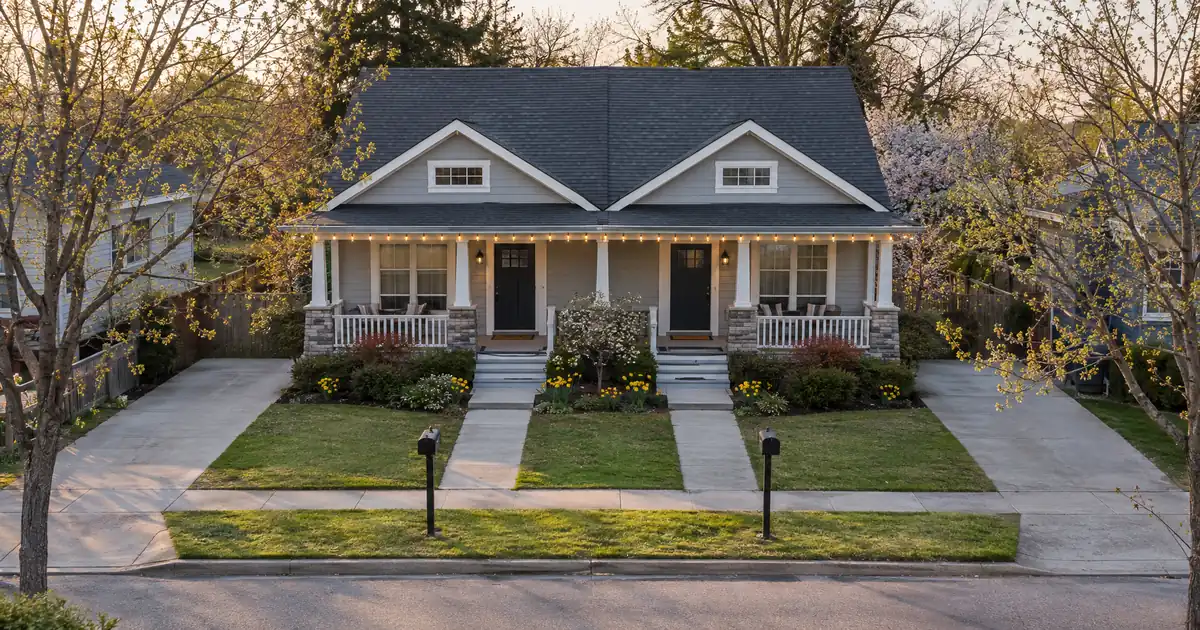
The Quick Read: FHA will finance a duplex, triplex or fourplex only if you buy it as your own home. You live in one unit, and the others can be rented to tenants. The low down payment is the reward for that promise. Break the promise and the loan stops being the product you applied for.
Key Takeaways
- The home must be your principal residence. You can have only one at a time.
- You move in shortly after signing and intend to stay at least a year. These are two separate clocks.
- On a 2-4 unit, you live in one unit and rent the rest. Rent from the other units can help you qualify, but only part of it counts.
- Triplexes and fourplexes face an extra test. The building’s rent, after a vacancy allowance, must cover the full housing payment.
- A non-occupying co-borrower is allowed, but it helps less on a 2-4 unit than on a single-family home.
- Misstating your plans is the one mistake that can unwind the whole deal.
What Counts as “Living There”?
You live there if the home is where you sleep, keep your belongings and spend most of the year. That is the plain meaning of a principal residence. A vacation home does not qualify. A place you buy to rent out entirely does not qualify either.
FHA payment estimate
Starting assumptions reflect an example price and the FHA minimum investment. Replace them with your own figures.
Editable benchmark: 7.32% as of October 22, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not an FHA loan quote.
Illustrative starting assumptions: a $350,000 price, the FHA minimum investment as the down payment, a thirty-year term at the current Freddie Mac benchmark, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conventional benchmark, a market reference and not an FHA loan quote; your rate is set by the lender at lock. FHA mortgage insurance follows HUD’s published schedule for the term, leverage and loan size entered; taxes, insurance and dues are editable estimates; closing costs are not included; county loan limits are not checked here. Licensed in sixteen states for consumer mortgages. Lendmire is not affiliated with or acting on behalf of FHA, HUD, or the federal government.
If you do not plan to live in the building, FHA is the wrong product. Occupancy decides how much financing a lender can offer. Across the wholesale programs Lendmire places FHA files with, owner-occupied purchases can reach 96.5% financing with a 3.5% minimum investment at a decision score of 580 or higher. These are FHA loan programs working as designed for people who live in what they buy. Lenders set their own credit floors and review each file, so confirm yours.
Think of the rule as a trade. You get strong financing. In return, the building becomes your address.
Three labels come up constantly, so keep them straight:
- Principal residence: your main home.
- Second home: a place you use part of the year.
- Investment property: a building you do not occupy.
FHA only fits the first.
The Two Clocks: Move-In and Stay
Two timing rules apply, and borrowers blur them constantly. One says when you must move in. The other says how long you must intend to stay.
| Item | Move-in clock | Stay clock |
|---|---|---|
| What it asks | Occupy the home after signing | Intend to remain for at least a year |
| When it starts | When you sign the security instrument | When you move in |
| What it tests | That you really are moving in | That this is a real home, not a flip |
Under the handbook, at least one borrower must move in within about two months of signing the mortgage documents. That borrower must also intend to stay for at least a year. The move-in window is short. The stay period is longer.
Occupancy is not tested at the closing table. You sign a statement of intent, and the clock starts then. Intent is the point. A job transfer in month five is life. Buying with a plan to move out in month five is a problem.
How the Rule Works on a Duplex, Triplex or Fourplex
On a 2-4 unit property, you live in one unit and may rent the rest, starting at closing if you like. Each added unit adds a rule. The financing is the same program, but the file gets more to prove.
| Item | Duplex | Triplex | Fourplex |
|---|---|---|---|
| You occupy | One unit | One unit | One unit |
| Other units | Rentable | Rentable | Rentable |
| Rent counts toward income | Yes, part of it | Yes, part of it | Yes, part of it |
| Extra rent test | No | Yes | Yes |
| Loan ceiling | Set by county | Higher | Higher still |
The lender uses the appraiser’s market rent, not the seller’s asking rent and not your hopes. Only a reduced share of that rent counts toward qualifying. A vacancy and upkeep allowance comes off first. Lenders treat that haircut as normal.
Triplexes and fourplexes add the self-sufficiency test. The appraiser’s rent from every unit, including yours, less a vacancy allowance, must cover the full housing payment. Rent from other people’s units is not enough on its own. The test caps how big a payment the building can carry. You must still qualify on your own income and ratios.
FHA’s county loan limits rise with each added unit. HUD’s published mortgage limits show a higher ceiling for a fourplex than for a duplex, and each county sits somewhere between a floor and a ceiling. Check your county before you shop.
Step by Step: How the File Is Underwritten
Here is how a 2-4 unit owner-occupant file moves from application to closing, as the Lendmire team sees it week to week.
1. You state your intent. The application says this will be your principal residence. The lender asks which unit you will take.
2. The appraisal. A 2-4 unit gets a different report form than a single-family home. It includes a rent schedule, and the appraiser’s rent figures drive the rest of the file.
3. Leases and rent documentation. Existing tenants mean existing leases. The lender wants to see them.
4. Qualifying income. Your own income comes first. Part of the rent can be added when ratios are calculated. The base ratio pair is 31/43 (housing to total income) with no compensating factors. Documented strengths can reach 40/50 at the top tier, and the automated finding governs most files.
5. The self-sufficiency test (3-4 units). Rent after a vacancy allowance must cover the full payment.
6. Loan limit check. The loan must fit the county limit for that unit count.
7. Closing. You sign the occupancy certification. The move-in clock starts.
8. After closing. Lenders can check occupancy, mostly when a loan goes into default servicing. It is not a routine drive-by on every loan.
This follows the structure of HUD Handbook 4000.1, the rulebook for FHA lenders. HUD updates the handbook often, so a lender should confirm current wording against it.
Key Terms Defined
Principal residence: the home where you keep your permanent address and spend most of the year. HUD’s glossary adds that a person may have only one at a time.
Owner-occupant borrower: a borrower who lives in the property that secures the FHA loan as their principal residence.
Security instrument: the mortgage or deed of trust you sign at closing. It starts the move-in clock.
Non-occupying borrower: a co-borrower who signs the loan but will not live in the home.
Self-sufficiency test: the extra check on triplexes and fourplexes. Their rent, less a vacancy allowance, must cover the full housing payment.
Boarder: someone who rents a room inside your own unit. A boarder is different from a tenant who rents a separate unit.
Investment property: a building that no borrower occupies as a principal or secondary residence. FHA does not finance it.
Four Scenarios, No Dollar Signs
The duplex buyer. Picture a buyer who puts 3.5% down on a duplex and moves into the downstairs unit. A tenant already holds a lease upstairs. The lender uses the appraiser’s rent for that unit, applies the haircut and adds the result to the buyer’s qualifying income. This is the standard house-hack, and it fits the rule. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
The tenant in your future unit. Say you pick a fourplex where the unit you want is occupied. The seller must deliver it empty, or you must wait out the lease and move in during the window. Check this before you write an offer. Lenders also ask where you live now and why you are moving.
The co-borrower who never moves in. A parent co-signs to help a child qualify. The parent never lives there. The loan is allowed, but on a 2-4 unit the financing drops well below the usual maximum. The full-financing exception for family members covers single-family homes, not 2-4 units. Confirm the current handbook language with the lender.
The relocation in year one. An employer transfers a borrower soon after closing. That is a life event, not a plan from day one. Lenders weigh the intent you had when you signed. Keep the transfer letter and talk to your servicer before you act.
Where the General Rule Bends
Non-occupying co-borrower. One borrower lives there and the other does not. The occupying borrower satisfies the occupancy rule. On a 2-4 unit, expect tighter limits on how much can be financed.
Active-duty military. A service member stationed away can still count as an owner-occupant. A family member must occupy the property, or the borrower must intend to occupy it on discharge. Lenders ask for orders showing the duty station is well away from the property.
A second FHA loan. The usual limit is one FHA loan at a time. HUD’s FHA FAQ lists exceptions. One applies when a borrower moves out of a principal residence that stays occupied by an existing co-borrower. Another applies when the loan-to-value on the current home is 75% or less after the household grows. Relocation exceptions exist too. All are rule-specific, so do not assume one applies to you.
Boarders and room rentals. A roommate in your own unit is a boarder. That differs from renting a separate unit. Tell the lender about either arrangement up front.
Short-term rentals of the other units. Treat this as a conversation to have with the lender before you sign, not an assumption. How the appraiser and lender count that income can vary.
The edge cases look like loopholes. They are not. Each exists for a specific life situation, and each has paperwork.
What Happens if Occupancy Is Misstated?
Misstating occupancy is the costliest mistake on this loan. Consequences usually escalate in steps:
1. A lender inquiry about where you actually live.
2. A request for proof, such as utility bills, a driver’s license or tax records.
3. A demand for the loan to be repaid in full.
4. Possible legal referral when the misstatement looks intentional.
Researchers have studied this. A Federal Deposit Insurance Corporation-hosted paper found that borrowers who misrepresented occupancy defaulted at nearly twice the rate of others. Those results rest on bank and Fannie Mae and Freddie Mac loans, not FHA specifically. The lesson holds anyway: lenders watch this closely.
Myths Versus Rules
| Myth | What actually applies |
|---|---|
| I can buy a fourplex with FHA as a landlord | You must live in one unit |
| Occupancy is only checked at closing | You sign an intent that carries a one-year expectation |
| All the rent counts | Only a reduced share counts |
| The rent test applies to duplexes | It applies to 3-4 units |
| Passing the rent test means I qualify | You still must meet income and ratio guidelines |
| A parent can co-sign my duplex at full financing | The family exception excludes 2-4 units |
| I can hold two FHA loans | Only under named exceptions |
FHA Versus Conventional on Occupancy
Conventional loans also allow 2-4 unit primary residences. They have no FHA-style self-sufficiency test, and their down-payment and credit rules differ. The stronger play depends on credit, savings and the building. Some borrowers with strong credit and cash do better conventionally. FHA tends to win when the down payment is thin or the score is middling. That is a real toss-up, and the comparison is worth running before you pick.
After the First Year
After the minimum stay, life opens up. You can move out and rent every unit, subject to your loan terms and the one-FHA-loan rule above. If you later want equity out, the FHA cash-out program reaches 80% LTV on a home owned and occupied for 12 months before the case number. Lendmire’s piece Can a 2-4 Unit Primary Home With a High DTI Get an FHA Cash-Out? walks through that path. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Keep proof of your occupancy anyway. A short checklist helps:
- Keep your lease or mortgage statements showing the property address.
- Update your driver’s license and voter registration.
- Have bills and tax mail sent to the property.
- Save a copy of your signed occupancy certification.
- Keep records of the unit you live in and the leases for the others.
Frequently Asked Questions
Can I buy a fourplex with an FHA loan if I rent all four units?
No. FHA requires you to live in one unit as your principal residence. Renting all four means the building is an investment property, which FHA does not finance. You can live in one unit and rent the other three.
Do I have to move in on closing day?
No. The rule gives you a short window after signing, about two months, to occupy the home. You must also intend to stay at least a year. Planning for a longer gap is the risk. Lenders look at your intent when you signed.
Can a relative co-sign if they will not live in the home?
Yes, a non-occupying co-borrower is allowed. On a 2-4 unit, the family-member exception that allows higher financing does not apply, so the amount that can be financed is lower. At least one borrower must still occupy the property.
Does my tenant’s rent count toward qualifying?
Part of it does. The lender uses the appraiser’s market rent, takes off a vacancy allowance, and counts only a reduced share. On a triplex or fourplex, rent must also pass the self-sufficiency test. Rental income does not replace meeting your own ratios.
What if I need to move after a few months?
A genuine change, such as a job transfer, is treated differently from a plan to move out from the start. Gather documentation and speak to your servicer before you rent out your unit. Whether you can use FHA again depends on the exceptions in the one-FHA-loan rule.
Next Step
If you are buying a home and want to see whether an FHA loan fits your file, Lendmire can help you compare the options and what each one asks of the file. Reach out at 828-256-2183 or request a quote. Program details are subject to lender guidelines and full file review, and nothing here is a commitment to lend.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage serving homeowners and home buyers in 16 states. FHA, VA, conventional and jumbo purchase and refinance loans are arranged through wholesale lending channels; Lendmire brokers the financing and the lender underwrites each application. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. HUD Mortgagee Letter 2025-23
2. HUD Handbook 4000.1 information page
3. HUD Handbook 4000.1 glossary
4. HUD FHA FAQ: more than one FHA loan
5. FDIC-hosted occupancy misrepresentation paper
This article is part of Lendmire’s FHA loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Conventional vs FHA Cash-Out Requirements on a 2–4 Unit Primary Home · How to Document Occupancy as an Heir for an FHA Cash-Out · VA Cash-Out Requirements for a Veteran Leaving FHA or Conventional
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.