
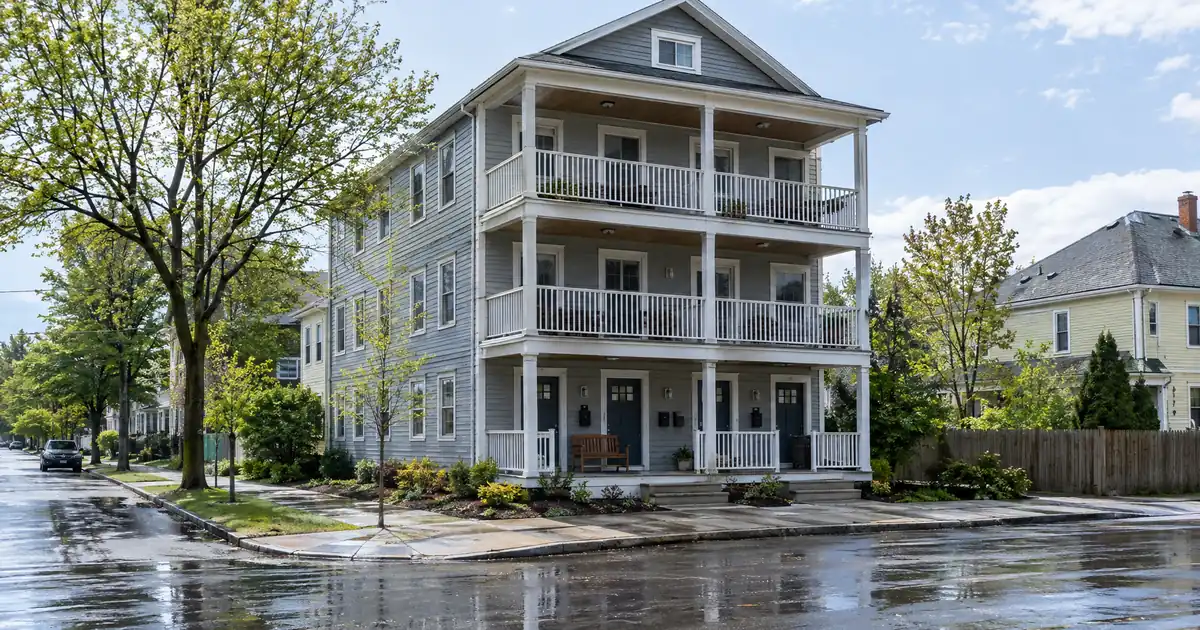
The Quick Read: A VA loan lets you buy a two- to four-unit property, move into one unit, and rent out the others. The catch is that you must live there. The lender may also count part of the rent toward your income, but only if you show you can handle being a landlord and hold cash reserves. This is not a way to buy a pure rental.
Most borrowers hear “VA loan” and picture a single-family house. The program is wider than that. This guide walks through the mechanics from start to finish: what the occupancy rule demands, how a lender treats the rent, what the appraisal checks, where the general rule breaks, and what the decision looks like in practice.
VA payment estimate
Starting assumptions reflect an example price with no down payment and a first-use funding fee. Replace them with your own figures.
Editable benchmark: 7.32% as of October 22, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not a VA loan quote.
Illustrative starting assumptions: a $350,000 price, no down payment with full entitlement, a first-use funding fee financed into the loan, a thirty-year term at the current Freddie Mac benchmark, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conventional benchmark, a market reference and not a VA loan quote; your rate is set by the lender at lock. The funding fee follows VA’s published table for the use and down payment entered; the residual-income figure is VA’s guideline for the region and family size, and the rough residual shown subtracts only the housing payment and the debts entered, while VA also deducts taxes, maintenance and utilities. Taxes, insurance and dues are editable estimates; closing costs are not included. Licensed in sixteen states for consumer mortgages. Lendmire is not affiliated with or acting on behalf of the Department of Veterans Affairs.
What Does “Live in One Unit and Rent the Rest” Mean With a VA Loan?
You buy a building with up to four residential units. One unit becomes your home. The others go to tenants. The VA Lenders Handbook says the veteran or borrower must occupy one unit as a residence when buying a multi-unit property.
That one sentence explains why this is a home loan and not an investment loan. The loan is built around where you sleep. Tenants in the other units are a feature of the property, not the purpose of the purchase.
Across the wholesale programs Lendmire places VA files with, the core terms are the same as for any VA purchase. You can finance 100% of the price with no down payment, as long as the price does not exceed the appraised value. There is no mortgage insurance of any kind. Everything here is subject to lender guidelines and full file review, and none of it is a commitment to lend. Lendmire is a mortgage broker, so it arranges these loans through wholesale lenders rather than lending directly. You can see how it fits together on the VA loan programs page.
Key Terms Defined
Entitlement: the amount of VA backing you have available. Your Certificate of Eligibility shows it.
Certificate of Eligibility (COE): the VA document confirming you qualify for the benefit. VA decides this, and service requirements are VA’s rules.
Residual income: what is left of your monthly income after taxes, debts, and a set allowance for living costs. For VA loans, it is the controlling test.
Minimum property requirements: VA’s condition standards. The home must be safe, sound, and sanitary.
PITI: principal, interest, taxes, and insurance. It is the full monthly housing payment.
Reserves: verified cash left in your accounts after closing.
Funding fee: a one-time VA fee, which can be financed into the loan. It is waived for veterans receiving compensation for a service-connected disability and for other exempt groups.
Which Properties Qualify?
Up to four residential units qualify: a duplex, triplex, or fourplex. Think of it as a short checklist:
- The property has no more than four residential units.
- You will live in one of them.
- Every unit meets VA’s minimum property requirements.
- You have the entitlement available for the loan.
Some lenders also allow a small business space in the building. The limits on that vary, so ask the loan officer instead of assuming.
Here is a detail that surprises people. For guaranty purposes, the handbook says lenders look only at the one-unit column of the FHFA conforming loan limit table, even on a four-unit building. For a borrower with full entitlement, that does not cap the purchase. It matters only when you have partial entitlement, and then you should speak with a loan officer about where you stand.
How Does the Occupancy Rule Work in Practice?
You certify at the start that you will live in the property as your home. You should move in within a reasonable time after closing. You can rent the other units, but you cannot rent all of them and live elsewhere. That would make it an investment property, which this program does not finance.
Picture a buyer who closes on a fourplex, then keeps working and living two towns away “until the tenants settle in.” That buyer has broken the certification.
Do not assume nobody checks. A Federal Reserve Bank of Philadelphia working paper finds occupancy misrepresentation persisted not just during the housing bubble but through more recent times. Lenders and investors know the pattern. Treat the occupancy promise as a real commitment.
How Does a Lender Count the Rent?
Short answer: the lender counts some of it, not all of it, and only when you meet two tests. The handbook says rental income from the subject property can go into effective income only if you have a reasonable likelihood of success as a landlord and verified cash reserves.
Those two tests do the heavy lifting:
1. Landlord capability. You show prior experience managing rentals, or you hire a property management company. No experience does not mean no rental income. A manager is a documented fallback.
2. Reserves. The handbook calls for at least six months of PITI in verified reserves when rent is counted. Confirm the exact reserve rule for your property with the lender. Lenders can add their own requirements on top of VA’s.
The lender then needs a rent figure. That comes from a signed lease or from the appraiser’s opinion of market rent. The handbook tells underwriters to build a working knowledge of the local rental market, so a rent number with no support behind it will not carry weight.
One more point. The rent for your own unit never counts. You are not paying yourself.
Counted rent also is not collected rent. Lenders generally count only a discounted share of the rent, because vacancies and repairs are real. The exact percentage comes from the rule and the lender, so ask for it up front. Then do your own budget. Vacancy, maintenance, and a broken water heater all hit you whether the underwriter counted them or not.
Lender View vs. Your Real Budget
| Question | Lender’s qualifying view | Your real budget |
|---|---|---|
| Whose rent counts? | Other units only | Other units only |
| How much rent? | A discounted share | What tenants actually pay |
| Vacancy | Built into the discount | Plan for empty months |
| Repairs | Not itemized | Your cost, every time |
| Reserves | Verified cash required | Cash that stays untouched |
How Is the Loan Underwritten, Step by Step?
1. Eligibility. You get your Certificate of Eligibility and confirm available entitlement. The occupancy certification joins the file.
2. Contract and appraisal. The appraiser values the property and checks minimum property requirements on every unit, including vacant ones. A unit that fails usually needs repairs before closing. The appraiser also gives an opinion of market rent.
3. Rent and landlord evidence. The lender collects leases or uses the appraiser’s rent opinion. You document landlord experience or a management company.
4. Reserves. The lender verifies your cash, including its source.
5. Underwriting. Counted rent goes into the loan analysis alongside your debt-to-income ratio and residual income. The 41% debt-to-income figure is a guideline, not a cap. A higher ratio needs residual income well above the table. The score floor on the wholesale programs Lendmire works with is a 580 decision score, and some lenders set it higher.
6. Decision. The outcome turns on five things: landlord capability, verified reserves, whether the appraisal supports the rent, whether every unit passes MPRs, and how much entitlement you have.
Plan on more paperwork than a single-family purchase. More units mean more documents and more exposure to repair requests.
What Cash Do You Need Up Front?
You may not need a down payment, but you still need cash. Think of the categories:
| Cost category | Why it matters |
|---|---|
| Reserves | Verified cash the lender wants left after closing |
| Closing costs | Itemized on your Loan Estimate and Closing Disclosure |
| Funding fee | A one-time cash cost that can be financed; waived for exempt borrowers |
| Repairs | Any unit failing MPRs needs fixing |
| Vacancy cushion | Months before the first rent check arrives |
The funding fee follows the program tiers. On a first-use purchase it is 2.15% with less than five percent down, 1.5% with five to under ten percent down, and 1.25% with ten percent or more down. On subsequent use it is 3.3% with less than five percent down, with the same 1.5% and 1.25% tiers above that. It is waived for exempt veterans.
The appraisal is not a home inspection. It checks value and minimum standards. A separate inspection tells you what the building really needs, and with several units, that is money well spent.
Which Building Fits You?
| Building | Privacy | Complexity | Best fit |
|---|---|---|---|
| Duplex | Moderate | Lowest of the multi-unit options | First-time landlords |
| Triplex | Moderate | More leases, more repairs | Buyers who want more rent |
| Fourplex | Lower | Most paperwork and maintenance | Buyers ready to manage |
A duplex is the gentle on-ramp. It has one tenant to manage and one set of repairs to watch. A fourplex produces more rent against the payment, but it adds more units to maintain and more room for repair surprises. Honestly, it is a genuine toss-up for many buyers. The fourplex wins on income and the duplex wins on sleep.
If you would rather rent out rooms inside a single-family house, that is a different property type from the two- to four-unit buildings covered here. Ask a loan officer how a lender would treat it.
Where Does the General Rule Break?
Several situations look similar but follow different rules.
Renting out the home you are leaving. This is a different path. When you buy a new home and keep the old one as a rental, the handbook uses a rental offset: the rent only offsets the payment on that rental property and may not go into your effective income. Reserves are three months of PITI per property, and cash-out refinance proceeds and gift funds cannot count as reserves. The older VA handbook chapter lays out the mechanics and the loan analysis form. Do not mix this up with the owner-occupied multi-unit rule.
Established rental properties. If you are buying a property with a rental history, that older chapter calls for a two-year history on the tax return. Depreciation claimed on the return can be added back to income. Tax treatment can depend on your situation; borrowers should speak with a qualified tax professional before relying on any deduction or credit.
Boarders. The handbook treats boarder income as its own category with its own documentation and reserve rules. Ask the lender how it handles it.
Three- and four-unit self-sufficiency tests. Some other programs apply one. VA does not appear to have an equivalent at the program level, but individual lenders may add their own overlay. This varies, so ask early.
Other loan types. Investor products do not allow owner occupancy. Conventional and FHA loans also allow you to occupy one unit of a two- to four-unit property, but their terms differ from VA’s.
Moving out later. If you leave, you may be able to convert the home to a rental and use remaining entitlement on another purchase. That is a separate path from the one-unit rule. Whether remaining entitlement is enough is a determination for VA and the lender, so confirm it before you plan around it. Lendmire’s piece Can You Get a VA Cash-Out on a Duplex If You Live in One Unit? covers the refinance side of that question.
What Does the Decision Look Like?
Say you are a veteran with full entitlement and steady income, eyeing a duplex. You would live in one side and rent the other. The lender counts a discounted share of the other unit’s rent. You hold reserves and either have landlord experience or hire a manager. Both units pass MPRs. If all that holds, the file is reviewable on its merits.
Now flip it. You have no reserves and a fourplex with a failing roof. Counted rent will not rescue that file, and repairs come before closing.
The honest test is simple. Could you carry the payment if a unit sat empty for a few months? If yes, the strategy gives you a home with tenants helping pay for it. If no, buy smaller.
Common Mistakes
- Renting every unit and living elsewhere.
- Treating counted rent as guaranteed income.
- Skipping the inspection because the appraisal passed.
- Ignoring unit-level repairs until the appraisal flags them.
- Forgetting that reserves must stay in the account.
- Assuming a lender overlay is a VA rule, or the reverse.
Frequently Asked Questions
Can I rent out the other units right away?
Yes, once you occupy your unit as your home. The lender can use a lease or the appraiser’s market-rent opinion. You cannot be an absentee landlord from day one, because the occupancy certification requires you to live there.
Do I need landlord experience?
Not necessarily. The handbook route for first-timers is hiring a property management company, which documents your ability to run the rental. Prior experience managing rentals also works. Lenders may ask for either.
Is there a VA loan limit on a fourplex?
With full entitlement, there is no VA loan limit. The one-unit conforming column is used for guaranty math, which matters mainly when you have partial entitlement. In that case, speak with a loan officer.
Does all the rent count toward qualifying?
No. Only a discounted share of the rent from the other units counts, and only when you show landlord capability and verified reserves. Your own unit’s rent never counts.
What if I move out later?
You may be able to keep the property as a rental and use remaining entitlement elsewhere. That is a separate path from the one-unit rule, and VA and the lender decide what entitlement remains.
Your Next Step
If you are buying a home and want to see whether a VA loan fits your file, Lendmire can help you compare the options and what each one asks of the file.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage broker licensed for consumer lending in 16 states. Lendmire arranges FHA, VA, conventional and jumbo purchase and refinance loans through wholesale lenders; every file is underwritten by the lender under the applicable program guidelines. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. VA Lenders Handbook, Chapter 4
2. FHFA conforming loan limits
3. Federal Reserve Bank of Philadelphia, Working Paper 23-01
4. VA Handbook Chapter 4 PDF (older)
This article is part of Lendmire’s VA loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How to Qualify for a VA Loan on a 2-4 Unit Above the DTI Guideline · How to Remove an Ex-Spouse or Co-Borrower From a VA Loan · 15-Year vs. 30-Year VA Loan for a Veteran Retiring or Separating
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.