
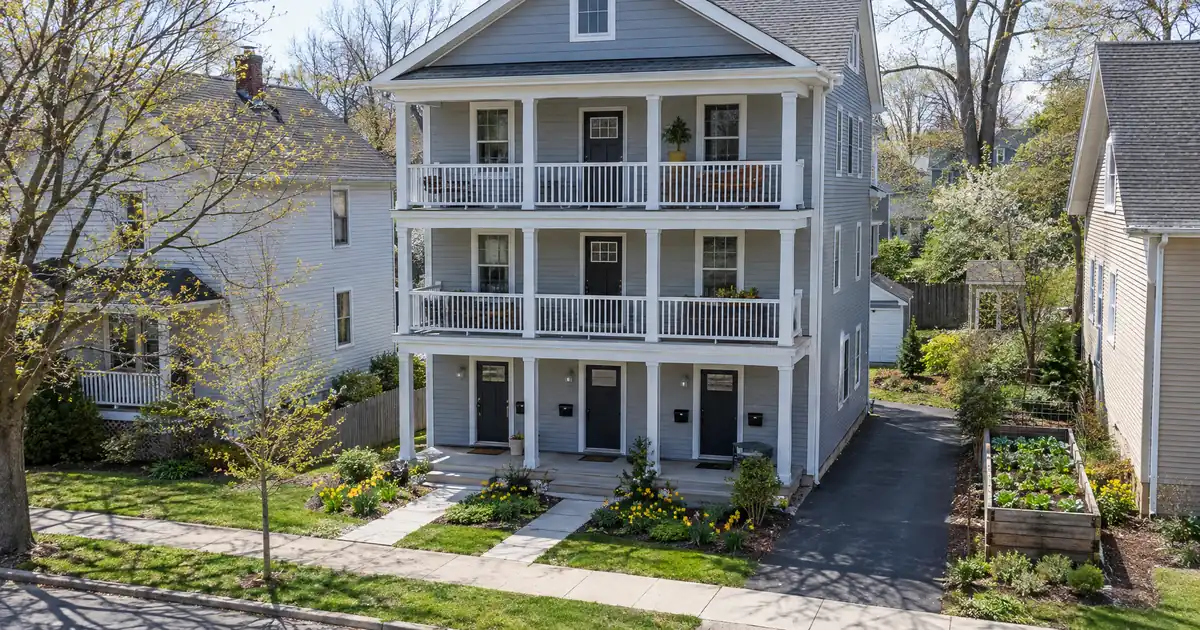
The Quick Read: Owning two to four units does not change how FHA mortgage insurance ends. The annual premium follows your loan’s origination date, your starting loan-to-value (LTV), and your loan term. It does not follow the number of doors. Some loans drop the premium on a schedule. Most others keep it until the loan is gone, and the practical exit is a refinance into a non-FHA loan.
That is the whole map. The rest of this piece shows how to place your own loan on it, what a refinance asks of a 2-4 unit, and how to decide whether leaving FHA is worth the cost.
Key Takeaways
- Unit count does not set the insurance clock. Origination date, starting LTV, and term do.
- Extra principal payments and a higher home value do not shorten the premium on newer FHA loans.
- A thirty-year FHA loan that started above 90% LTV keeps its annual premium for the term. At or below 90%, it ends after eleven years.
- A refinance is a new loan with new underwriting, a new appraisal, and new closing costs. The savings must outlast them.
- A 2-4 unit refinance into conventional is stricter than the same refinance on a single-family home. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
FHA payment estimate
Starting assumptions reflect an example price and the FHA minimum investment. Replace them with your own figures.
Editable benchmark: 7.32% as of October 22, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not an FHA loan quote.
Illustrative starting assumptions: a $350,000 price, the FHA minimum investment as the down payment, a thirty-year term at the current Freddie Mac benchmark, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conventional benchmark, a market reference and not an FHA loan quote; your rate is set by the lender at lock. FHA mortgage insurance follows HUD’s published schedule for the term, leverage and loan size entered; taxes, insurance and dues are editable estimates; closing costs are not included; county loan limits are not checked here. Licensed in sixteen states for consumer mortgages. Lendmire is not affiliated with or acting on behalf of FHA, HUD, or the federal government.
Does a 2-4 Unit Change How FHA Mortgage Insurance Works?
No. The insurance rules key to the loan, not the building. A duplex and a single-family home with the same origination date, starting LTV, and term follow the same premium schedule. Unit count matters earlier, at purchase underwriting, and later, when you refinance.
Two premiums exist on an FHA loan. The upfront premium is 1.75% of the base loan, and most borrowers finance it into the balance. It is paid once. Removing the monthly premium later does not refund or reverse it. The annual premium is charged as a percentage of the balance and collected monthly with the payment. Across the wholesale programs Lendmire places files with, that annual premium runs between 0.15% and 0.75% of the balance, depending on term, loan amount, and LTV.
That second premium is the one people want gone. On a 2-4 unit the balance is usually larger than on a single-family home, so a premium that lasts for the loan term is a bigger recurring cost. That is the reason this question comes up so often with owner-occupants of small multi-unit buildings.
A quick word on the starting point. The FHA minimum investment is 3.5% from a 580 decision score, which means maximum financing of 96.5%. A borrower who started there is in the “above 90% LTV” bucket described below, and that bucket drives most of the stories here. To see how the loan is built from the start, review Lendmire’s FHA loan programs page. Terms depend on the lender’s guidelines, the property type, the leverage, and a full review of the credit profile.
When Does FHA Mortgage Insurance End on Its Own?
It ends on its own only in a few cases, and your loan’s origination date and starting LTV decide which one you are in. The case number, which FHA assigns at the start of the loan, sets the date that counts.
| Loan situation | What happens to the annual premium |
|---|---|
| Case number before June 3, 2013, term over 15 years | Cancels at 78% of original value, after at least five years of premiums |
| Case number before June 3, 2013, term of 15 years or less | Cancels at 78% of original value, no minimum premium period |
| On or after June 3, 2013, starting LTV 90% or lower | Ends after 11 years |
| On or after June 3, 2013, starting LTV above 90% | Lasts for the loan term |
The 2013 break comes from HUD Mortgagee Letter 2013-04, which directed FHA to collect annual premiums for the maximum duration the statute allows on loans with case numbers on or after June 3, 2013. It rescinded the earlier automatic-cancellation letters. The Congressional Research Service summarizes the result: loans at or below 90% LTV at origination can stop paying annual premiums after 11 years, and most other newer loans pay for life. The exact numbers vary by lender and program and follow a full review of property, leverage, and credit.
If you bought with the minimum investment on a thirty-year loan, you are in the bottom row. The premium stays. If you put down more than 10% from the start, you are in the 11-year row. If your loan is older than June 2013, you may not need a refinance at all. Ask your servicer to confirm the cancellation status in writing.
One honest caution. HUD policy is now carried in its handbook, which supersedes the 2013 letter. The handbook is the live rule, so check it or ask your servicer before relying on a date.
Why Equity Alone Doesn’t Remove It
FHA cancellation uses your loan’s starting numbers, not today’s. HUD Handbook 4000.1 says HUD does not use new appraised values when deciding whether a borrower has reached the LTV needed for cancellation. It bases cancellation on the initial amortization schedule.
In plain terms, three things do not help on a newer FHA loan:
- Home appreciation, however strong your market is.
- Extra principal payments, which build equity but do not move the premium schedule.
- Renovations that raise the value of one or more units.
This is the biggest difference from private mortgage insurance (PMI) on a conventional loan. PMI follows federal homeowner-protection rules. You can request cancellation in writing when the balance is first scheduled to reach 80% of the original value, and the servicer must act at that point if you are current on payments. FHA mortgage insurance follows HUD’s schedule instead. A cancellation letter to an FHA servicer on a newer loan goes nowhere.
| Feature | FHA annual premium | Conventional PMI |
|---|---|---|
| Rule set | HUD policy | Federal homeowner-protection law |
| Trigger | Origination date, LTV, term | Balance reaching 80% of original value |
| Does new appraisal help? | No | Sometimes, by servicer or investor policy |
| Does a written request work? | Not on newer loans | Yes, when conditions are met |
Appraisal-based cancellation on conventional loans is a servicer and investor matter, and the details vary by property type. Ask before assuming it applies to a multi-unit.
Refinancing Out of FHA on a 2-4 Unit
A refinance is the lever you control. You replace the FHA loan with a conventional one, and if the new loan sits at roughly 80% LTV or lower, it generally carries no mortgage insurance at all. Above 80%, the conventional loan carries PMI, which at least has a defined cancellation path.
The key difference is that this is a new loan, so a new appraisal counts. The rule that ignores new values applies only to canceling the premium on your existing FHA loan. A strong appraisal can lift you under the line that removes the insurance entirely.
Here is what the 2-4 unit changes. Fannie Mae’s eligibility matrix sets lower maximum LTVs for 2-4 unit principal residences than for single-family homes, and the gap is widest on cash-out refinances. In everyday terms, a duplex owner has less room than a single-family owner with the same equity, and a cash-out on a fourplex has the least room. If the building is no longer your primary residence, the ceilings drop further.
Across the wholesale programs Lendmire places files with, a few other things matter in practice:
- Equity. You need enough of it, measured on the new appraisal, to meet the LTV ceiling for the unit count.
- Credit and ratios. The new loan is fully underwritten. A solid credit profile helps most when you are close to the line.
- Rent from the other units. How it counts differs by program, so ask how the lender treats it in qualifying.
- Reserves. Multi-unit files can ask for more cash left after closing.
Eligibility review depends on the lender’s guidelines and a full review of your file. Nothing here is a commitment to lend.
Is the Refinance Worth It?
Often, but not always. The decision comes down to a break-even: total costs of the new loan against the premium you stop paying. The shape of the math is simple even without dollar figures.
Picture a homeowner with a fourplex bought with the minimum investment, a thirty-year loan, and a case number after June 2013. Their premium runs for the full term. After several years of payments and some appreciation, an appraisal supports a new loan at about 75% of the building’s value. The savings are the whole annual premium, and the costs are the appraisal and closing. If the homeowner plans to hold the building for many more years, the premium saved can outlast those costs by a wide margin.
Now flip it. Take a duplex owner whose loan is five years old, with equity that gets the new loan to only about 88% LTV. A conventional refinance there carries PMI, and the new loan resets the amortization schedule. If that owner might sell within a couple of years, the refinance probably costs more than it saves. Waiting and monitoring is the stronger move. Final terms depend on the lender’s guidelines, the property type, and the borrower’s complete credit picture.
A few variables decide most of these cases:
1. How many years you expect to keep the property.
2. How far under the 80% line the new appraisal puts you.
3. What the new loan’s total costs are on the Loan Estimate, compared with the premium saved.
4. Whether your credit and ratios are stronger or weaker than when you bought.
5. Whether the new term is shorter or longer than the time left on the old loan.
The break-even is a broker calculation. Ask for the comparison in writing before you commit to either path.
Moving Out of One Unit: What Changes?
Occupancy is the quiet swing factor. FHA requires the borrower to live in the property as a principal residence, and that is how the loan was approved. Nothing in the premium schedule changes when you move out. The premium follows the same date, LTV, and term rules.
What changes is your refinance menu. A conventional refinance on a building you no longer occupy is treated as a non-owner-occupied loan, with lower LTV ceilings and stricter terms. That narrows your path out of FHA mortgage insurance at exactly the moment you might want it. A homeowner who plans to move out of the building in the next year or two should ask about a refinance before moving, while the owner-occupied rules still apply.
Occupancy rules differ by program and lender, so ask how a move would affect your options.
Refinancing FHA to FHA: Why It Doesn’t Remove the Premium
An FHA Streamline refinances an existing FHA loan with no appraisal, a limited credit review, and a net tangible benefit to the borrower. It can be the right move for some files, but it does not remove the premium. The premium continues. A new FHA loan also gets a new case number, so the premium schedule for the newer era applies again.
The FHA rate-and-term refinance with an appraisal reaches 97.75% on a principal residence occupied for the previous twelve months. The FHA cash-out reaches 80% LTV on a home owned and occupied for twelve months before the case number. Both are FHA loans, which means both carry FHA mortgage insurance. Choose them for other reasons, not to escape the premium. Each figure is subject to lender guidelines and a complete review of property type, leverage, and credit.
A 3-4 unit FHA loan can also face a rent-coverage test at purchase, which asks whether projected rents cover the housing payment. A new FHA loan may bring that test back. Confirm the details with your lender.
Step by Step: From Checking Your Loan to Confirming the Premium Is Gone
1. Find your case-number date and starting LTV. They are in your original closing documents and loan paperwork. The LTV was measured against the lesser of the price or the appraised value.
2. Place the loan in its bucket. Use the table above: pre-June 2013, post-June 2013 at 90% or lower, or post-June 2013 above 90%.
3. If your loan cancels on schedule, ask your servicer. Request written confirmation of the date the premium should end and check your monthly statement after that date.
4. If it does not, estimate your equity. A rough value against your balance tells you whether a conventional refinance could reach the line. The appraisal will settle it.
5. Gather documents for a full refinance. Expect income and asset documents, current leases for rented units, and your mortgage statement.
6. Compare Loan Estimates. Look at total costs, the new term, and whether mortgage insurance remains.
7. Check the result. After closing, confirm the old FHA loan is paid off and the new loan shows no FHA premium. Keep the payoff letter.
If the servicer does not drop a premium that should have ended, ask for a written explanation citing your case-number date. Keep every record.
Mistakes to Avoid
- Assuming 20% equity cancels the premium. On newer loans it does not.
- Confusing a Streamline with an exit. The premium continues.
- Ignoring the occupancy window. Moving out first narrows your refinance options.
- Forgetting the upfront premium. It is paid and gone. Only the annual premium is in play.
- Refinancing without a break-even. A lower payment today can cost more over the time you hold the property.
- Stretching the term. A new thirty-year clock can raise total interest even when the monthly premium is gone.
Some lenders set stricter rules on multi-unit refinances than the programs described here, so compare more than one set of terms. Tax treatment can depend on your situation. Borrowers should speak with a qualified tax professional before relying on any deduction or credit.
Key Terms Defined
Case number: The number FHA assigns to a loan file, whose date decides which premium rules apply.
Annual mortgage insurance premium (MIP): The monthly charge, set as a percentage of your balance, that protects the FHA program and the lender.
Upfront premium: A one-time charge of 1.75% of the base loan, usually financed into the balance.
Loan-to-value (LTV): The loan amount divided by the lesser of the price or the appraised value.
Private mortgage insurance (PMI): Insurance on a conventional loan with less than 20% equity, which has defined cancellation rights.
Amortization schedule: The planned month-by-month paydown of the balance, which FHA uses to measure cancellation.
Frequently Asked Questions
Does having two to four units make the premium last longer?
No. The premium duration depends on the loan’s case-number date, starting LTV, and term. A fourplex and a single-family home with the same numbers follow the same schedule. The difference is that a multi-unit loan tends to be larger, so the same premium costs more over time.
Can I remove the premium by renting out the other units?
No. Rental income has no effect on the premium schedule. It matters when you qualify for a refinance, where lenders may count rent from the other units, subject to their guidelines. How much of that rent counts differs by program.
Do extra principal payments end FHA mortgage insurance sooner?
Not on newer loans. Cancellation follows the initial amortization schedule, so paying faster builds equity without moving the end date. Extra payments still reduce your balance and the interest you pay, which is a real benefit even though the premium schedule stays put.
Does an FHA Streamline get rid of the premium?
No. A Streamline refinances one FHA loan into another and the premium continues. It carries a net tangible benefit test and skips the appraisal, which suits some borrowers, but it is not a route out of FHA mortgage insurance.
Can I take cash out when I leave FHA?
Sometimes. A conventional cash-out on a 2-4 unit principal residence has a lower LTV ceiling than a single-family cash-out, and it generally leaves you with less room to also drop mortgage insurance. Ask your lender to show both options side by side.
Next Steps
If you are buying a home and want to see whether an FHA loan fits your file, Lendmire can help you compare the options and what each one asks of the file. If you already hold an FHA loan on a small multi-unit, start with your case-number date. Then decide whether holding or refinancing makes the better trade for the years you plan to own the building.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
Lendmire — NMLS# 2371349 — is a mortgage broker that arranges FHA, VA, conventional and jumbo home purchase and refinance financing in 16 states through wholesale lenders. Every option is subject to the lender’s guidelines and full underwriting. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. HUD Mortgagee Letter 2013-04 (FHFA-hosted copy)
2. Congressional Research Service
3. HUD Handbook 4000.1 servicing excerpt
4. Fannie Mae Eligibility Matrix
This article is part of Lendmire’s FHA loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How to Show the Benefit on a Refinance That Drops FHA Mortgage Insurance · How to Close an FHA Streamline on a 2-4 Unit Primary Home · Refinance Requirements by Program for Leaving FHA Insurance Behind
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.