
The Quick Read: Yes, when the home is a true personal-use second home and your eligible assets either cover the whole loan or convert into enough qualifying income, subject to underwriting. Asset-based programs work on second homes, but a home bought mainly to rent out belongs in a DSCR loan instead, and the two cannot be blended.
- Qualifier path: eligible assets must equal or exceed the entire loan, and no income is documented.
- Depletion path: usable assets divided by 60 months become qualifying income that runs through the debt-to-income test.
- Leverage on a second home reaches 80% on a purchase on either path, through select programs.
- Short-term rental plans in northern New Mexico depend on local permits that may not transfer with the house.
Lendmire is a mortgage broker. It arranges asset-based mortgages through select lenders in its network, and consumer mortgage lending is available in New Mexico, among 16 states. The figures below are ceilings and floors, not offers. Every file is underwritten individually.
Which Path Fits a Santa Fe or Taos Buyer?
The right path depends on how your wealth is held and how much of it there is. Across Lendmire’s wholesale network, asset-based borrowers tend to be retirees, people who sold a business, heirs, and households living off a portfolio. Their balances are large and their documented income is not.
Think of the two paths as two different questions.
The asset qualifier path asks whether your eligible assets can cover the entire loan. If they can, no employment or income is documented. The asset depletion path asks whether your assets, converted into a monthly figure, can carry the housing payment and your other debts. A borrower is qualified on one path at a time. The figures never blend.
Some people call this an “asset depletion” or “asset utilization” loan. The label varies by lender. What matters is that it changes how income is measured, not whether the lender checks your repayment capacity.
How Does the Asset Qualifier Path Work?
On the qualifier path, your usable assets must equal or exceed the whole loan amount. Loans reach $4,000,000 through select programs, with up to 80% loan-to-value on a purchase and 75% on a refinance, subject to underwriting.
Here is how much of each balance counts:
- Brokerage accounts, certificates of deposit, money market and savings count at 100%.
- 401(k) and IRA balances count at 90% under age 59½ and 100% at 59½ or older.
- Accounts combine.
Credit starts at a 600 minimum score. Seasoning is 60 days, with two months of statements for each qualifying account. Reserves are not required at or below 75% loan-to-value. Above that, the lender sets them.
Run an illustrative case. An $800,000 loan is backed by $330,000 in brokerage accounts (100% counts, so $330,000), $300,000 in a 401(k) under 59½ (90% counts, so $270,000) and $200,000 in savings (100% counts, so $200,000). That totals $800,000 of usable assets, and the file is reviewed on assets alone. The lender’s own calculation governs the real result.
How Does the Asset Depletion Path Work?
On the depletion path, eligible assets become monthly income. You take usable assets after the haircuts and divide by 60 months. That figure must carry the full housing payment and your other debts through the debt-to-income test.
The haircuts differ from the qualifier table:
- Cash accounts and certificates of deposit count at 100%.
- Securities count at 80%.
- Retirement accounts count at 70% at any age.
- Real-estate equity counts at 60%.
Not eligible on this path: custodial accounts, deferred compensation, escrow accounts, foreign funds, cash on hand, privately held stock, stock options, non-vested restricted stock units, and funds from non-regulated financial companies.
Run the second illustrative case. $1,500,000 in securities (80% counts, so $1,200,000) plus $300,000 in cash (100%) gives $1,500,000 usable. Divide by 60 months and you get $25,000 of monthly qualifying income. That income then carries the housing payment and other debts through the debt-to-income test.
Loans run from $125,000 to $3,500,000 on this path. Leverage on a second home reaches 80% on a purchase or rate-and-term refinance and 60% on a cash-out refinance. Cash-out proceeds never count as qualifying assets. The minimums matter too: qualified assets of at least the lesser of $1,000,000 or 1.25 times the loan balance, and never below $250,000 liquid when assets are the only income source. Asset income can also supplement documented income up to a 45% debt-to-income ratio, and the minimum-assets rule is waived in that case.
On statements, the depletion path wants one set at least 120 days old at application, showing the assets have been in place, plus the most recent statement dated within 45 days. Funds from the sale of a business, an inheritance or a legal settlement are excused from that older-statement seasoning. Credit follows the lender’s matrix.
Assets stay in your accounts. Nothing is sold or pledged. The 60-month divisor is a qualifying convention, not a liquidation plan.
Santa Fe or Taos: Which Buyer Profile Fits Which Path?
Both markets share one financing logic, so the choice between them is mostly about use. Match the path to how your balances are held.
| Buyer profile | Likely fit | Why |
|---|---|---|
| Retiree with large IRA | Depletion or qualifier | Age 59½ and older counts retirement at 100% on the qualifier path |
| Sold a business, cash-heavy | Qualifier or depletion | Cash covers the loan; on depletion, sale proceeds skip older-statement seasoning |
| Portfolio household, mixed assets | Depletion | Securities at 80% convert to monthly income |
| Retiree under 59½ | Either | Retirement counts at 90% on one path, 70% on the other |
| Salaried with modest savings | Neither | Standard documentation likely fits better |
If your balances are mostly crypto, precious metals, collectibles, or borrowed funds, neither path lists them as eligible. The documented route is converting them to a seasoned cash balance in a regulated account, with the source reviewed by the lender.
What Counts as a Second Home, and Where Does the Line Sit?
A second home is a place you will personally use. Asset-based mortgages treat that as consumer credit. DSCR loans treat a property as business-purpose investment housing. The occupancy you certify at purchase decides which product applies.
DSCR loans are designed for non-owner-occupied investment properties. Because they are business-purpose investor loans, they are reviewed differently from a standard owner-occupied mortgage. Under CFPB Regulation Z, credit to buy rental property is business purpose, but that treatment stops applying if you expect to occupy the home for more than 14 days in the coming year. The Federal Reserve’s archived commentary repeats the same threshold.
Here is the practical consequence. If you plan weeks of use each season in Santa Fe or Taos, you are a consumer-purpose borrower, and asset-based qualifying is the fit. If you plan to rent it out and stay away, DSCR is the lane. Claiming a getaway as an investment to reach DSCR creates misrepresentation risk, and moving in later creates default risk. An LLC title does not change this. Actual use decides, not the label.
Can You Rent It Out If It Is a Second Home?
Light, occasional rental can sit alongside a second-home structure. Heavy rental pushes the file toward investment classification. On a true second-home file, rental income generally cannot be used to qualify. That is the sharp contrast with DSCR, where the property’s rent against its payment decides the file.
Short-term rental rules in northern New Mexico deserve a hard look before you count on any rent. They vary by city, county, HOA, and property type, so confirm local rules before relying on projected rental income. Three examples show why the jurisdiction matters:
- City of Santa Fe. The City of Santa Fe short-term rental FAQ describes a citywide cap of 1,000 residential permits, one per person, with no transfer on sale. That document is dated, so check the current rules with the city.
- Taos County, unincorporated. The county adopted an ordinance that caps non-owner-occupied permits at 400, as reported by the Taos News and the Santa Fe New Mexican. Reporting also describes a two-rental limit per owner.
- Town of Taos, Taos Ski Valley, Santa Fe County. Each is a separate jurisdiction with its own regime. A ski-village condo sits outside county rules and answers to its HOA and village.
The takeaway for underwriting is simple. In the City of Santa Fe, the permit does not pass with the house, and the other jurisdictions may have similar limits, so confirm each one locally. Any rent projection that assumes you will get a permit is a guess.
What Property Types Draw Extra Scrutiny?
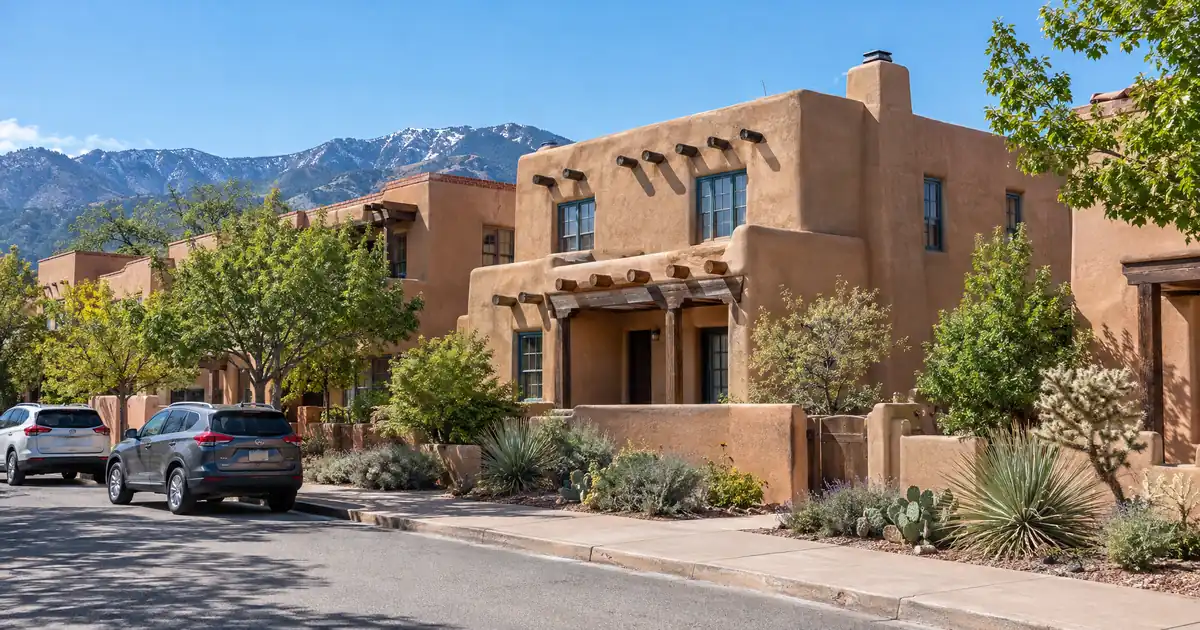
Property type matters as much as the borrower in both markets. Northern New Mexico has plenty of homes that are charming and unusual, and unusual can mean slower reviews.
| Property type | What reviewers tend to look at |
|---|---|
| Adobe home | Condition, comparable sales, insurability |
| Ski-area condo | HOA documents, rental restrictions, project review |
| Mountain or log cabin | Access, winter use, program eligibility |
| Rural parcel with well and septic | Utilities, access road, appraisal support |
Appraisals can be harder in resort and mountain areas because comparable sales are thin. Ask your broker early whether the specific property fits program rules. Eligibility is set by the lender’s guidelines, not by the borrower’s wishes.
Is Asset Qualifying Cheaper Than Other Routes?
Not necessarily, and the trade-off is worth stating plainly. For a salaried buyer with clean paperwork, a conventional loan underwritten on traditional employment income may fit better. Asset-based programs earn their place when income documents understate real wealth.
A few flip points:
- If your traditional personal-income documentation shows low income because of business write-offs or retirement, assets may tell the truer story.
- If you hold a large retirement balance and want to avoid selling investments, depletion lets you keep them in place.
- If you plan to rent it out regularly and hold several financed properties, DSCR is the better structure.
- Sub-1.00 DSCR programs are available through select lenders in the network, but leverage and terms adjust.
Key Terms Defined
Asset qualifier path: A path where eligible assets must cover the entire loan amount and no income is documented.
Asset depletion path: A path where usable assets divided by 60 months become qualifying monthly income.
Haircut: The share of an account balance that does not count toward qualifying.
Seasoning: The period an asset must sit in your account before it counts.
Occupancy certification: Your signed statement of how you will use the property.
Frequently Asked Questions
Do I need a job to buy a second home on assets?
No, not on the qualifier path, where no employment or income is documented and the review rests on your assets. The depletion path turns assets into income, which can stand alone or supplement documented income. The assets themselves are fully documented either way.
Can I use retirement accounts?
Yes, through select programs. On the qualifier path, 401(k) and IRA balances count at 90% under age 59½ and 100% at 59½ or older. On the depletion path, retirement accounts count at 70% at any age. Eligibility remains subject to underwriting.
Can I buy from out of state?
Generally yes, since the asset method does not depend on local income. Consumer lending through Lendmire’s network covers New Mexico.
Does a second-home loan allow cash-out?
The published figure is on the depletion path, where a second home reaches up to 60% on a cash-out refinance. The qualifier path’s cash-out terms are set by the lender and not published, so ask before assuming either way.
Can I rent a Santa Fe or Taos home short term to offset costs?
Possibly, but rental income generally cannot qualify the loan on a second-home file. Permits are capped, and in the City of Santa Fe they do not transfer on sale, so treat rent as upside rather than a plan.
If you are qualifying on assets rather than income and want to see how the numbers work, Lendmire can help you compare asset-based mortgage options based on your statements, the property, credit profile, leverage, and your goals. Reach the team at 828-256-2183 or request a quote.
Northern New Mexico rewards buyers who decide first how they will use the house, because that one choice sets the loan, the paperwork, and every rental option that follows.
About Lendmire
Lendmire, NMLS# 2371349, is a mortgage brokerage with consumer lending licenses in 16 states. Bank statement, P&L-only, 1099-only and asset-based mortgages are arranged through wholesale lending partners for borrowers whose traditional personal-income documentation understates their income, and each application is reviewed individually by the lender. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. CFPB Regulation Z, Section 1026.3
2. Federal Reserve archive of Regulation Z commentary
3. Taos News on the Taos County ordinance
4. Santa Fe New Mexican on the Taos County rule
This article is part of Lendmire’s asset-based mortgage program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Margin Loan vs Asset-Based Mortgage for a Home Purchase · Can You Buy a Second Home in Alabama on Assets Instead of Income? · How to Buy Before You Sell in Colorado Using an Asset Qualifier Mortgage
Guides: Asset-Based Mortgage in Santa Fe, NM · Asset-Based Mortgage in New Mexico
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.