
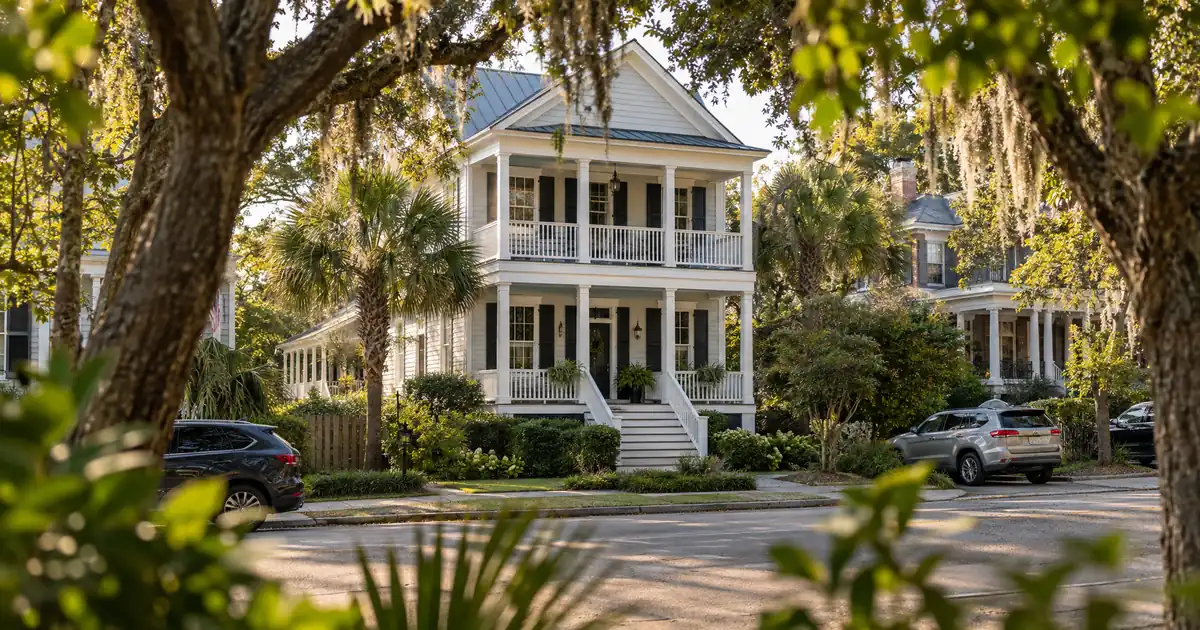
How much cash can a Sullivans Island rental actually release? Less than the home’s value suggests. Zillow puts the average home value at $4,537,108, up 6.3 percent year over year, but a DSCR cash-out is sized by rent against the full monthly obligation, and rent on this island does not scale with price. The equity is real. The coverage is the constraint.
For real estate investors in Sullivans Island, South Carolina, Lendmire helps structure and place DSCR financing through wholesale lenders operating in 41 markets, including D.C. Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker, so it arranges these loans and lenders do the review and approval. This article is about pulling equity out of a house you already own. It is not about buying one.
DSCR Cash-Out Calculator
Run the cash-out numbers in Sullivans Island, SC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
At a Glance: A Sullivans Island cash-out refinance is underwritten primarily on the property’s rental income measured against its full monthly obligation, with the appraisal, a long-term rent schedule, and roughly six months of seasoning deciding how much equity the 75 percent ceiling can release.
- Average house rent is $8,200 per HotPads, against values in the millions.
- Redfin shows 112 days to sell and a Compete Score of 21 out of 100.
- Interior homes sit at $2.5 million to $3.5 million, oceanfront at $5 million to $15 million or more, per Katherine Cox Homes.
- Cash-out LTV tops out at 75 percent, and this market will usually need less.
Sullivans Island Market Snapshot
A quick read on the Sullivans Island investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $4.2M median (Southern Bell Living) |
| Typical rents | $2,419 average apartment (Zumper rent research) |
The Market Reporter’s Read: Big Equity, Thin Rent
Sullivans Island is an ultra-luxury barrier-island town. Census Reporter counts 2,087 residents and a median household income of $192,813, against $85,254 for the metro. Jobs are off-island. Mean commute is 17.6 minutes, mostly over the Ben Sawyer Bridge toward Mount Pleasant and the Charleston peninsula.
Prices are volatile because the sample is small. Southern Bell Living cites a year-end median sale price of $4.2 million from Charleston Trident Association of Realtors data, down 15.7 percent from the prior year, and warns that small samples make medians swing. Homes.com lists homes from $899K to $22.35M, with 25 active listings and about 119 days on market. Sources that disagree this widely tell you something: the appraisal is the biggest variable on the file.
Rent data is thinner still. Listing-based figures and local property manager estimates point to high rents for island houses, and Palmetto Street, a local property manager, puts island single-family rents well above the listing-based median. Census-derived gross rent in City-Data comes in far lower, which points to a small pocket of older, lower-rent stock next to the luxury houses. Treat that as a data-mix caveat, not a rent comp for a multimillion-dollar house.
Why the Coverage Number Runs Low
Rent divided by full PITIA, meaning principal, interest, taxes, and insurance, is the number that matters. On Sullivans Island it runs well under 1.00 at high leverage.
Run the numbers on a modeled case. Assume an interior house valued near $3,000,000, inside the $2.5 million to $3.5 million band, and an in-place lease at the $8,200 HotPads median. At 75 percent LTV, coverage including taxes and insurance comes out below 0.50x. Assume instead a rent of $12,000, and it still sits under 0.75x. These are modeled inputs, not a quote.
An oceanfront house at a value in the mid-$4 million range is worse. Rent does not climb in step with a $5 million-plus price tag, and 75 percent of that value runs into the standard-program loan ceiling of up to $3,000,000 before coverage even enters the picture. The LTV at which $8,200 of rent clears 1.00 on a $4.2 million value lands in the teens, percent-wise.
Sub-1.00 files have paths, and a lender would review each one on its merits:
- A sub-1.00 DSCR program, typically with stronger compensating factors, lower leverage, or different pricing.
- An interest-only structure that lowers the monthly obligation in the ratio.
- A much lower LTV, sized so the rent carries the balance.
- A different collateral property in the portfolio, where the rent-to-value ratio is stronger.
Eligibility is subject to lender guidelines, credit approval, and property review. Most standard programs are built around a 1.00x baseline because rent covers the obligation at that level. How the qualification works is laid out on the pillar page.
Interior, Oceanfront, and the Condo Sliver
The island splits into three rough tiers, and the DSCR math differs by each.
Interior homes are the best fit. Katherine Cox Homes puts them at $2.5 million to $3.5 million, and fewer than 30 listings were active at last check. The price is lower, so the same lease covers more of the obligation. Zillow examples of recent island rentals include a 3-bed/2-bath listed at $7,500 a month and a 4-bed at $9,800. Those are single listings, not medians, but they show the range a lender will look at.
Oceanfront is appreciation-led and the weakest for coverage. Values run $5 million to $15 million or more, per the same agent page. The rent schedule will not get close to supporting a large cash-out, and the appraisal range is wide enough that one oceanfront sale can reset the comp set.
Condos start near $899K on the Homes.com low listing. They are the closest thing to a DSCR-friendly price point on the island. The catch: no sourced condo rent figure exists here, and condo files carry the HOA questionnaire and condo certification steps. Incomplete questionnaires are a preventable reason files stall, so request them early.
No source documents duplex, triplex, or fourplex inventory on the island. Do not build a cash-out thesis on stacking units here. The market is single-family houses and a few condos, and the town’s own Long-Term Residential Rental Agreement form says each rental unit needs its own lease.
Skip the Short-Stay Income Assumption
DSCR income on this island comes from long-term leases. Short stays are not a path here, and investors should confirm current rental rules with the Town of Sullivan’s Island along with taxes and insurance through qualified local professionals. That is the whole reminder, and it needs saying once. Every neighboring barrier island is built around vacation rentals, so a lot of DSCR marketing you will see for this coast does not apply to a Sullivans Island file.
What applies is a clean long-term lease and a rent schedule from the appraiser. Expect a lender to ask for the executed lease, proof of deposit and first-month rent on recent leases, and a market rent opinion. A thin tenant pool is a real feature of the island: rent is high in dollars, but the pool of households who can pay it is narrow.
The Appraisal Is the File
Working DSCR brokers see a recurring pattern in thin, high-value markets like this one: the value opinion, not the borrower, decides the outcome. With few recent comps and big spreads between oceanfront and interior sales, an appraiser has to reach for adjustments, and the result tends to be conservative. The files that hold together are the ones where the investor sized leverage below the program ceiling before the appraisal came back, not after.
Redfin reports about 112 days to sell and a Compete Score of 21. Slow, thin turnover means fewer closed comps in the lookback window. A well-built appraisal reconsideration packet can recover value, using recent in-neighborhood sales and condition adjustments. Still, plan for the first number to land conservative.
The appraisal also feeds reserves. Program guidance runs about 6 months of PITIA in reserves, and about 9 months on larger balances above $1,500,000. On a house with a high monthly obligation, that is a serious documented balance. Reserves documentation, meaning statements that show the funds and their seasoning, is one of the quiet file-killers on high-balance loans.
Seasoning, LTV, and What Comes Out
Seasoning before a cash-out is about 6 months of ownership, measured from title recording. The settlement statement documents it. Files that assume seasoning away are the ones that get kicked back. If you bought in the last half year, wait, or ask whether a delayed-financing structure is available, which depends on the lender.
The LTV ceiling for cash-out is 75 percent. It is a ceiling, not a target. In this market it almost never is the binding constraint. Coverage is. Credit tiers in the network run 620, 660, 680, and 700, with 620 the floor, and better tiers generally help leverage and pricing. Program details are subject to change, so confirm current guidelines with the brokerage before building a plan around a specific figure. The cash-out qualification details cover the mechanics, and a rate-and-term refinance remains an alternative if pulling cash out does not pencil.
Here is the thing investors miss on Sullivans Island. A conservative appraisal, a low LTV to hit 1.00, and six-plus months of reserves can shrink the released cash to a fraction of what a 75 percent headline implies. Equity available depends on rent used for lender review, PITIA, reserves, and the ceiling. It is never a guaranteed cash figure.
Where the Equity Redeploys (Mount Pleasant and Charleston)
The natural use of island proceeds is buying in markets where rent-to-value is stronger. Palmetto Street puts Mount Pleasant single-family rent at about $3,300 a month, with 3-bedrooms at $4,025 to $4,030, downtown Charleston at about $4,395, and Daniel Island at $4,400 to $6,000. Zillow’s area page shows average home values of $875,306 in Mount Pleasant and $590,308 in Charleston. Island rent is higher in dollars, but those markets hold a clearly stronger ratio of rent to price.
Demand there has a deep anchor. The Charleston Regional Development Alliance lists Boeing South Carolina with more than 9,000 employees, MUSC at about 17,000, and Joint Base Charleston at nearly 25,000 military and civilian jobs. Healthcare workers, military families, and relocating professionals are the tenant groups Palmetto Street names.
Caution on rent trends. RentCafe shows Mount Pleasant average apartment rent down about 1 percent year over year, and RentHop shows 2- and 3-bedroom rents down 14.12 and 9.65 percent. Underwrite on in-place leases, not projected growth. Nothing in the research shows a reliable vacancy or rent-growth figure for the island itself.
Picture an investor who holds an interior island house, refinances at a conservative LTV, and uses the proceeds as the down payment on a Mount Pleasant rental priced well under the island’s values. The second property has to cover its own obligation on its own rent. The cash-out on the first is capital, not income. If the island refinance does not pencil, leaving the house unleveraged and using a different owned property for the cash-out may be the stronger play, though an investor who wants to keep every asset in one LLC could argue the other way. How DSCR stacks up against conventional financing is worth reading if income documentation is the obstacle.
A Practical File Sequence
1. Pull title and confirm recording date. Seasoning runs from title recording, so get the settlement statement in hand first.
2. Get the lease and a market rent opinion. Long-term lease only, executed, with deposit evidence. The appraiser’s rent schedule sets the rent used for lender review.
3. Stress the coverage at three leverage levels. Run 75 percent, 60 percent, and lower, with taxes and insurance in the obligation. Find where the ratio clears 1.00.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Sullivans Island, SC, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
4. Line up reserves documentation. Statements showing seasoned funds for the required months, with higher reserves on larger balances.
5. Confirm entity documents. For LLC-titled rentals, the operating agreement, EIN letter, and good standing certificate go in early, subject to lender program eligibility.
6. Request the appraisal with a reconsideration plan. Gather recent in-neighborhood sales ahead of time so a low value can be challenged on evidence.
For investors who want to see the structure before committing, start your quote or call Lendmire at 828-256-2183. The hub page on South Carolina DSCR financing covers the statewide program picture.
The investors who size leverage to the rent, not the value, will be the ones whose Sullivans Island equity actually turns into the next deal.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Sullivans Island?
Qualification centers on the property’s rent used for lender review against its full PITIA, with a 1.00 minimum DSCR on most standard programs, credit at or above a 620 floor, about 6 months of seasoning from title recording, and a cash-out LTV at or below 75 percent. Reserves run about 6 months of PITIA, more on larger balances. On this island, the rent-to-value gap usually makes the coverage ratio the binding test, not the LTV ceiling. All of it is subject to lender guidelines and property review.
What are the requirements for an investment property loan in Sullivans Island, South Carolina?
Expect an appraisal with a rent schedule, an executed long-term lease, proof of reserves, entity documents if the property sits in an LLC, and title information. Loan amounts run up to $3,000,000 on standard programs, and smaller balances route through select lenders. Properties like manufactured homes, log homes, and barndominiums fall outside these programs. Confirm local rental rules with the Town, and confirm taxes and insurance with local professionals.
Why does the DSCR math run so low on Sullivans Island houses?
Values sit in the millions while rent sits in the thousands. With average house rent near $8,200 and Zillow’s average value above $4.5 million, rent covers only a fraction of the obligation at high leverage. The fix is lower leverage, a different collateral property, or a sub-1.00 structure a lender would review, such as an interest-only option.
Is the interior or oceanfront better for a cash-out refinance?
Interior homes generally fit better. Katherine Cox Homes puts interior values at $2.5 million to $3.5 million versus $5 million to $15 million or more on the oceanfront, and rent does not rise in proportion. Oceanfront is the most appreciation-led and the weakest for coverage, and its appraisal range is wide because there are few comparable sales.
Can an LLC-owned Sullivans Island rental be reviewed for DSCR financing?
Yes, subject to lender program eligibility. Lendmire arranges DSCR investor loans, and qualification is generally reviewed around the property’s rental income rather than personal income documents. Entity paperwork should be ready before the file goes in.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income, not the borrower’s W-2 history, which suits LLC-titled portfolios and self-employed investors. Every scenario remains subject to program review and program guidelines. The brokerage has been named both a 2026 Scotsman Guide Top Workplace and a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Home Values, Sullivans Island
2. HotPads
3. Redfin, Sullivan’s Island housing market
5. Southernbellliving.com — Sullivans Island
7. Homes.com, Sullivan’s Island listings
8. Palmetto Street, Charleston rental market trends
9. Long-Term Residential Rental Agreement form
11. Zillow — Sullivans Island SC
12. Charleston Regional Development Alliance, major employers
13. MUSC
14. RentCafe
15. RentHop
16. a 2026 Scotsman Guide Top Workplace
17. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Sullivans Island, South Carolina: How Rent Math Clears at 75% LTV · DSCR Cash Out Refinance in Mount Pleasant, South Carolina: How Rent Math Clears at 75% LTV · Cash Out Refinance Investment Property in Mount Pleasant SC
Guides: Investment Property Cash-Out Refinance in South Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.