Asset Depletion Loans In Key Largo: Qualifying On Assets Alone
It’s a non-QM tool built for retirees, business owners, and investors whose tax returns understate their real financial strength.

It’s a non-QM tool built for retirees, business owners, and investors whose tax returns understate their real financial strength.
That path uses 12 or 24 months of statements, not W-2s, and it works whether the home sits on the water or three states inland.
Business owners who plan even occasional personal stays need a different loan structure than those buying a pure rental.
Through select wholesale programs, subject to full underwriting, files run from $300,000 to $30,000,000.
Bank Statement Loans In Rosemary Beach — A super jumbo bank statement loan lets a self-employed or high-net-worth buyer qualify on 12
Asset Depletion Mortgages In Rosemary Beach — This is an income-calculation method, not a separate loan product.
Tax returns built around legitimate deductions understate real cash flow, and a conventional lender only sees the smaller number.
This explainer walks through how the underwriting actually works, where it bends, and what a real file looks like from application to approval.
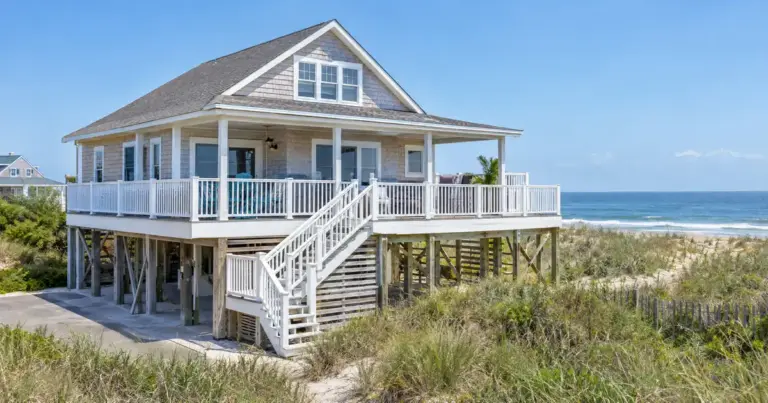
A lender converts liquid assets into an imputed monthly income figure, then runs that figure through normal underwriting.
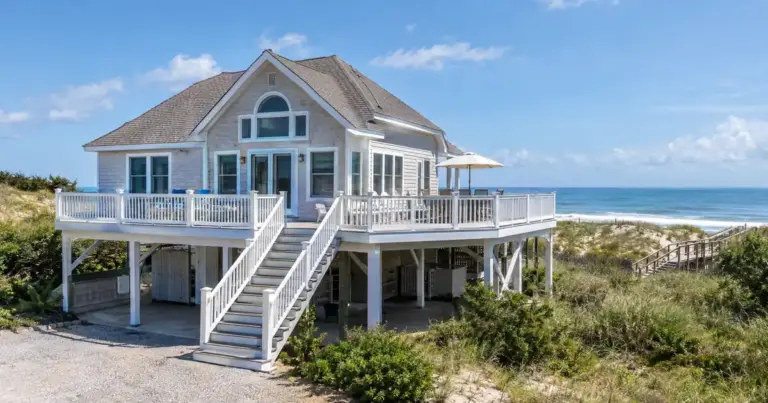
It works when you plan to use the property yourself and rent it only sometimes.
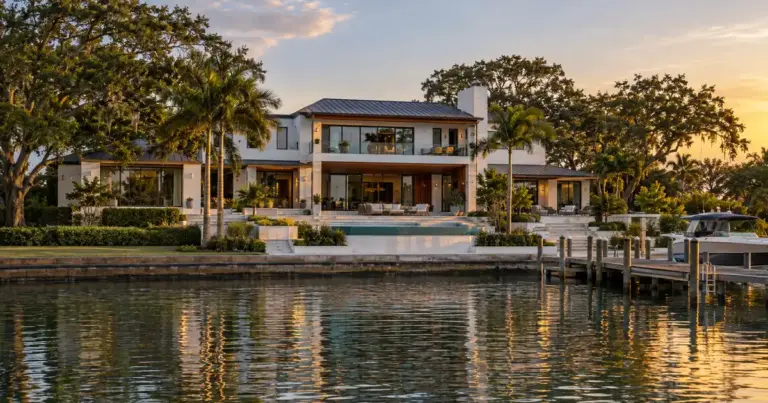
Asset Depletion Mortgages In Jupiter — These loans let a borrower qualify using verified liquid assets instead of pay stubs or tax returns.
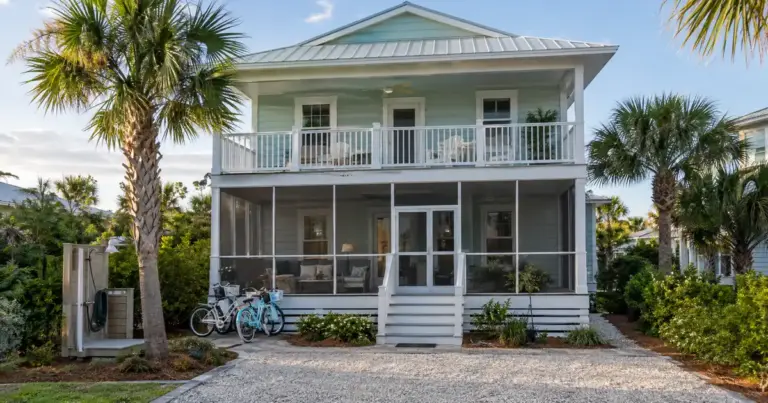
The portfolio does not get spent down or frozen — it stays invested and keeps growing while it does the underwriting work.
It’s different from an “appraisal review,” which is a lender’s staff re-checking the first report without a new inspection.
Nothing in this framework is location-specific.
It sits inside the same non-QM toolkit as bank statement lending but works off a balance sheet, not a deposit history.