Asset Depletion Mortgages In Portsmouth: Assets, Not Income
A lender takes verified account balances, applies discounts for volatility and access limits, then divides the result by a set number of months.

A lender takes verified account balances, applies discounts for volatility and access limits, then divides the result by a set number of months.
Asset Depletion Mortgages In Bar Harbor — This is a qualification method, not a specific loan product tied to any one place.
That shift changes the paperwork, the down payment, and the leverage available — but it does not shut business owners out.
Super jumbo is not a government category.
Above roughly $4 million, every file moves to case-by-case underwriting rather than an automatic grid.
Leverage steps down as the loan gets bigger, and every file above $4 million gets a case-by-case look before it’s even submitted.
Not every asset counts, and the ones that do often count at a discount.
Terms vary by lender guidelines, property type, leverage, credit profile, and full file review. Nothing here changes based on zip code.
Financing A Second Home In Camden On Bank Statements: what borrowers need to know about high-net-worth bank-statement financing, from Lendmire.
Bank Statement Loans In Bethesda — A super jumbo bank statement loan qualifies a self-employed borrower using 12 or 24 months of deposits
Above $4,000,000, every file gets reviewed case by case before it goes to a lender at all.
Above roughly $4,000,000, every file gets reviewed case by case before submission.
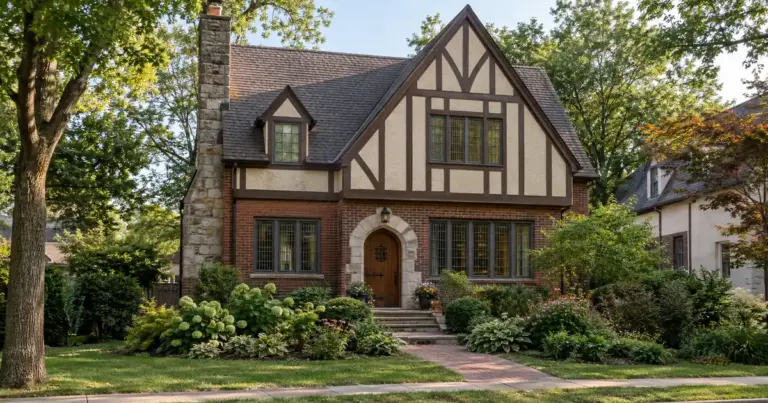
Lenders decide occupancy first — primary, second home, or investment property — and only then look at how income gets documented.
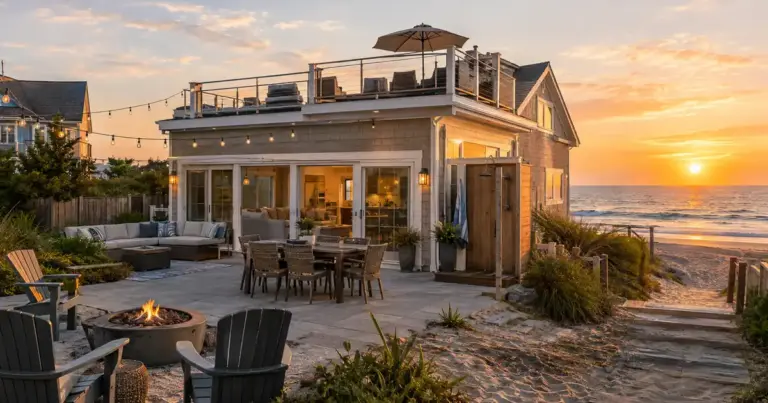
Asset Depletion Loans In Bethany Beach: Qualifying On Assets Alone — what borrowers need to know, from Lendmire.
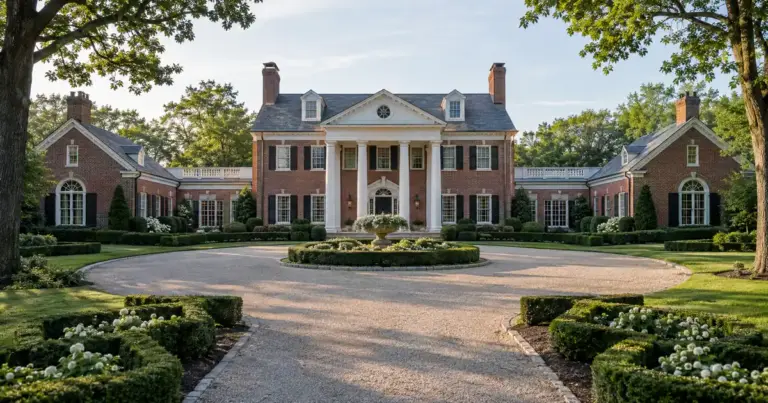
The mechanics work the same way for a retiree in Bethesda as anywhere else in the country — location doesn’t change the math.