Super Jumbo Bank Statement Loans In Bald Head Island
On a barrier island where most homes list above $1 million, this documentation path is often the only realistic route to financing.

On a barrier island where most homes list above $1 million, this documentation path is often the only realistic route to financing.
If personal use will exceed roughly two weeks a year, the file belongs in a bank statement program that qualifies on deposits instead of tax returns.
Everything else in the file — expense ratios, asset haircuts, interest-only structuring — exists to support those two numbers.
Second-Home Financing In Franklin — A second home is a property you personally use part of the year — not a rental.
A lender totals your eligible assets, applies haircuts by account type, then divides what’s left by a set number of months.
Asset Depletion Loans In Wrightsville Beach — An asset depletion loan lets a borrower qualify using liquid assets instead of a paycheck.
Retirement accounts get discounted before age 59½ because early withdrawals carry a tax penalty.
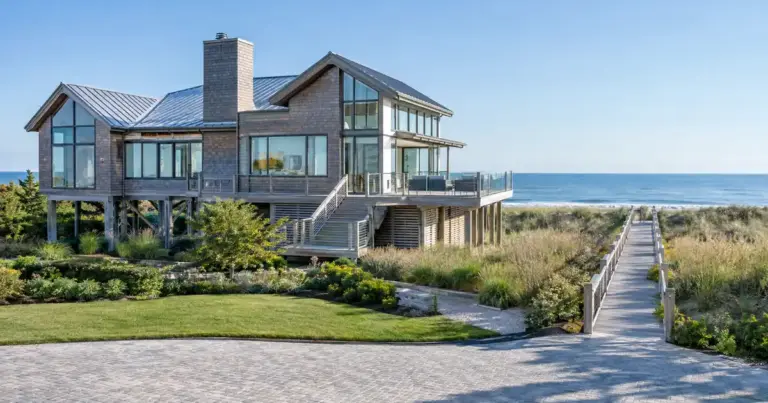
DSCR loans only work for properties the borrower never occupies.
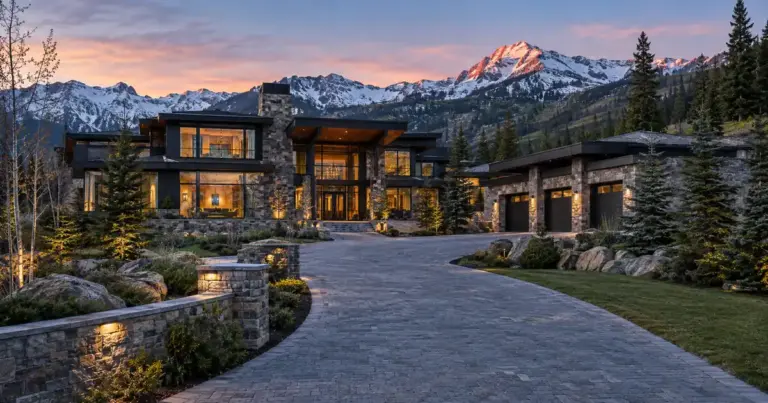
Leverage on a second home runs lower than on a primary residence and steps down as the loan size grows.
– Asset qualifier loans substitute verified liquid assets for pay stubs, W-2s, and tax returns.
A lender counts your eligible cash and investment accounts, applies a haircut to volatile holdings, and divides what’s left by a set number of months.
One road qualifies the borrower’s personal cash flow off 12 or 24 months of statements.
Underwriters take your eligible assets, subtract what you need for closing, and divide the rest by a set number of months.
Lendmire arranges these files through select wholesale lenders, subject to underwriting.