Bank Statement Loan Vs Full-doc Jumbo For A Practice Owner With K-1 Income
Full-doc tends to win when the K-1 shows strong, stable ordinary income and real distributions.

Full-doc tends to win when the K-1 shows strong, stable ordinary income and real distributions.
P&L-Only Vs 1099-Only Loan For A Consultant — Both are non-QM alternatives to tax-return underwriting, but they use different inputs.
If overhead runs low, business statements can actually beat personal ones.
Bank statement jumbo works when you still run an active business with recurring deposits.
If your write-offs are heavy but legitimate, P&L usually shows more usable income.
A DSCR loan qualifies the property itself, using its rental income to cover the payment, and it requires the home to be a non-owner-occupied rental.
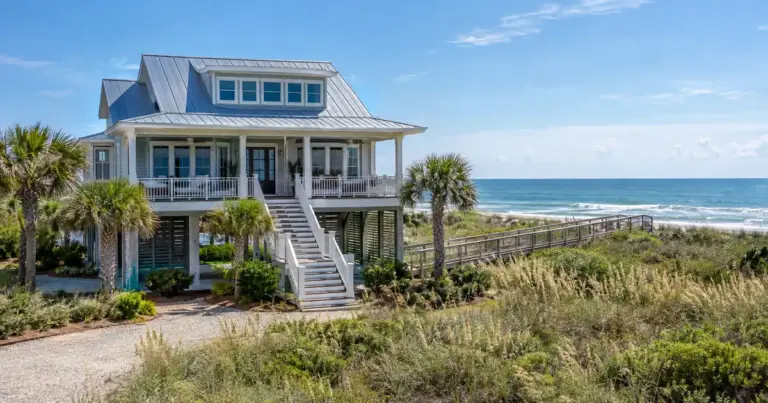
Isle of Palms is a barrier-island market where owners often want both.
Business assets, gift funds, crypto, unvested stock, and most trusts generally don’t count.
Get a Super Jumbo Loan the Year — Yes, you can get a super jumbo loan the year after your exit with no income.
A lender converts eligible savings, brokerage, and retirement balances into a monthly income figure by dividing them across a set number of months.
Answer that honestly, and the right loan structure follows.
Bank statement financing solves this by qualifying you on deposit history instead of tax returns.
Above roughly $3 million to $3.5 million, everything moves to case-by-case review before it’s even submitted.
Getting this classification wrong at application is a structural problem, not a paperwork fix.
Bigger loans mean lower leverage. Lighter documentation means tighter terms elsewhere. Get the tradeoff right before you shop, not after.