Buying A Vacation Home In Mammoth Lakes On Bank Statements
That single choice determines the documentation path, the leverage available, and whether rental income can even help you qualify.

That single choice determines the documentation path, the leverage available, and whether rental income can even help you qualify.
A property you’ll use yourself and rent fewer than 14 days a year can qualify as a second home.
None of what follows depends on where the property sits; the same occupancy test applies whether the second home is in wine country or anywhere else.
A lender divides eligible assets by a set number of months, and that result gets treated like monthly income.
Retirees keep showing up as a named driver of this loan category in trade coverage, and for good reason.
It’s a consumer, owner-occupied and second-home tool — not a rental-property financing product.
There is no federal definition of “super jumbo” — each lender in the network sets its own threshold, which is exactly why shopping matters here.
A lender divides eligible balances by a set number of months to produce a monthly income figure, then underwrites the file against that number.
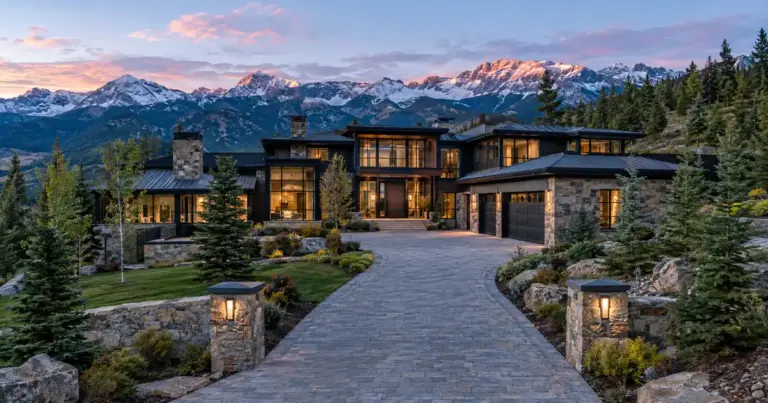
Underwriters take the eligible balance, apply account-specific discounts, and divide the result by a set number of months.
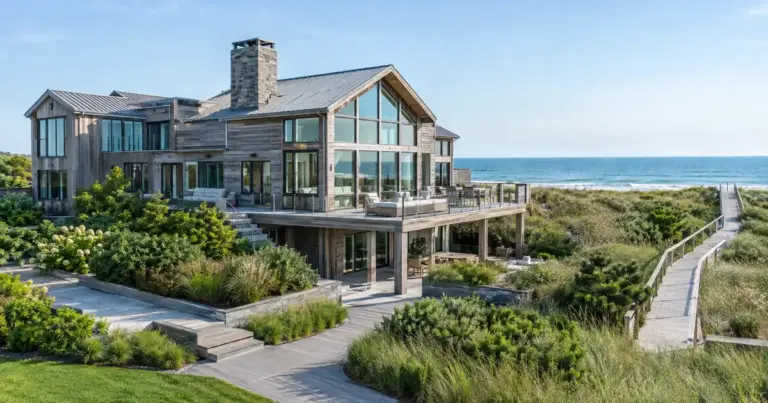
The two products solve different problems, and mixing them up creates real compliance risk.
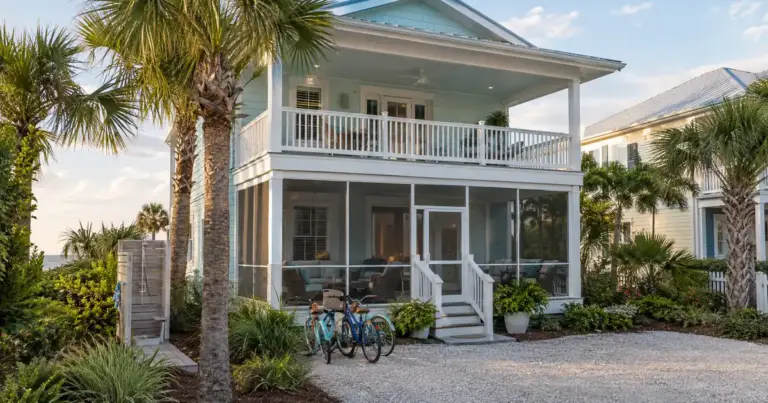
The lender takes eligible cash, investments, and retirement funds, applies a divisor, and treats the result as monthly income for underwriting.
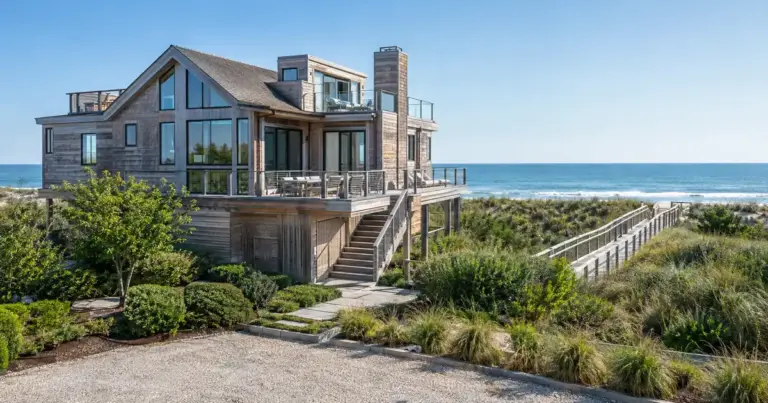
A lender divides the eligible asset pool by a set number of months to produce that figure, then underwrites the loan the normal way from there.
That’s the setup worth understanding before choosing how to finance the purchase.
Bank statement loan: a mortgage that qualifies income from 12 or 24 months of personal or business bank deposits instead of tax returns or W-2s.
Lenders divide the eligible balance by a set number of months to produce that figure.