
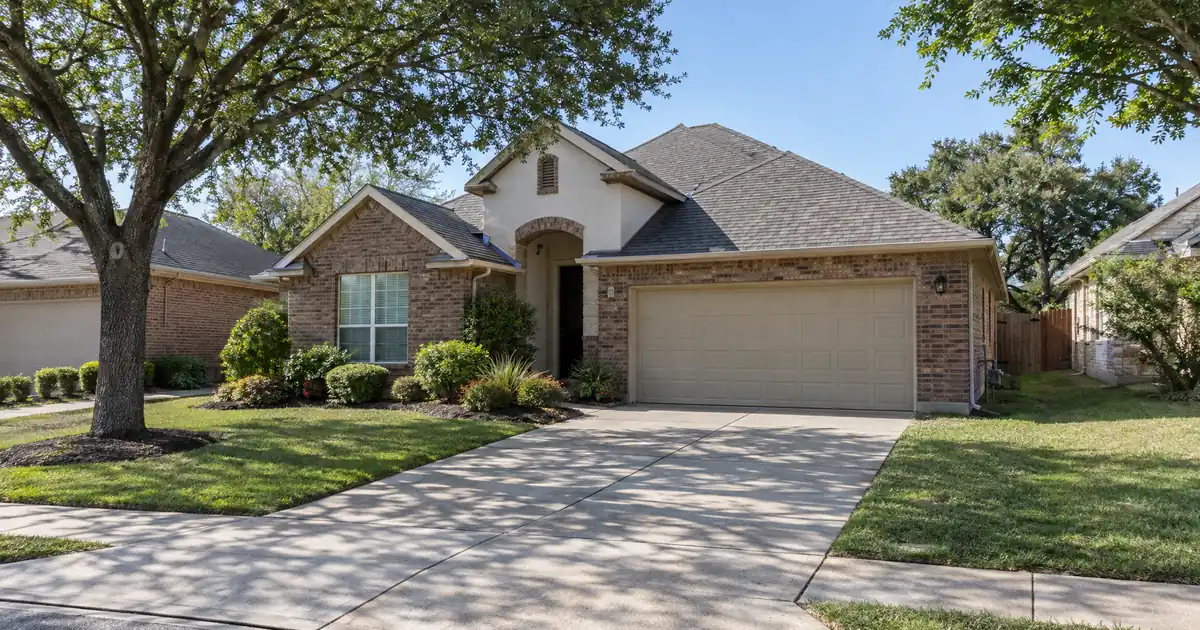
Picture an investor holding a three-bedroom house in north Denton’s 76209, bought at $359,000, the zip’s median price per Destination: North Texas, and rented near the $2,100 median house rent Zumper reports. The loan balance has barely moved and neither has the value. A DSCR cash out refinance sounds like the next step. Whether it actually produces any cash is the real question.
TL;DR: A DSCR cash out refinance in Denton, Texas is underwritten primarily on the property’s rental income measured against its full monthly obligation. It lets an investor draw equity from a rental already owned, up to a 75 percent loan-to-value ceiling and after roughly six months of seasoning, subject to lender guidelines.
DSCR Cash-Out Calculator
Run the cash-out numbers in Denton, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Houses rent near $2,100 against a $350,224 average value, so full-leverage coverage sits under 1.00.
- Stepping loan-to-value down toward 60 to 65 percent moves modeled coverage close to 1.00.
- Apartment concessions are pulling rents down, so underwrite in-place rents, not asking rents.
- Campus, downtown, and north zips have minimal new construction, which supports rent stability.
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker. Investors in Denton, Texas work with Lendmire to place DSCR financing through wholesale lenders reaching 41 markets, including D.C. The equity-extraction mechanics are covered on the cash-out refinance page. This article stays on what is specific to Denton: the price series, the rent series, and the gap between them.
Where Is the Equity in a Flat Market?
Denton’s equity story is about basis, not appreciation. Zillow puts the average value at $350,224, down 3.5 percent over the past year. Redfin’s Denton County data shows a median of $454K, up 0.8 percent on a three-month basis. The county includes pricier suburbs, so the two figures describe different markets, and the city sits at the lower end.
No source in the research gives a reliable multi-year appreciation figure for the city. That matters. An owner who bought recently at close to today’s value has little to extract. An owner who bought several cycles ago, or who has paid the balance down meaningfully, may have real room under the 75 percent ceiling. That ceiling is a hard cap for cash-out on these programs, lower than the purchase maximum, and the cash that comes out is whatever remains after the existing balance and reserves.
Seasoning adds a second gate. Programs in the network typically look for about six months of ownership, measured from title recording. Investors who recently closed a purchase can’t refinance into equity they haven’t had time to establish. A fresh purchase is also unlikely to have equity anyway.
The Coverage Math at Full Loan-to-Value (and at Less)
Run the numbers on the opening scenario. These are modeled assumptions, not sourced market data: a $359,000 value, $2,100 monthly rent, and a full obligation that includes principal, interest, taxes, and insurance. At 75 percent loan-to-value, coverage lands around 0.85. That is below the 1.00 level that some select programs use as a floor, because at that ratio rent falls short of covering the full payment.
Cut leverage and the picture shifts. At 65 percent, the same house models near 0.95. At 60 percent, it sits right around 1.00. Round those down if anything, since a different insurance quote can move the result.
Here is the catch. If the investor bought with 20 to 25 percent down, a 60 percent target leverage leaves essentially nothing to pull. The loan can work as a refinance, but not as an equity harvest. So the practical Denton cash-out candidate has either substantial paydown or an older basis.
A sub-1.00 file isn’t automatically dead. Select lenders may review sub-1.00 programs, and some borrowers restructure with interest-only terms. Both typically come with stronger credit, lower leverage, or larger reserves, and qualification stays subject to lender guidelines, credit approval, and property review. The better question is whether the number is telling you something. If the house only works at a 60 percent loan-to-value with no cash left over, the refinance may not be worth doing at all.
Typical guidance puts the minimum credit score at 620, with better pricing and leverage at 660, 680, and 700. Reserves run about six months of the full obligation, and about nine months on loans above $1,500,000. Exact terms depend on lender, borrower, and property. For the broader qualification mechanics, see the guide “What Is a DSCR Loan”.
Appraisal Risk in the Older Stock
The houses that look best on rent-to-price are the ones the appraiser may like least. A July commentary in the Denton Record-Chronicle says apartment oversupply is pushing down prices of smaller homes in the city, and that buyers are less eager to bid on small, aging properties with deferred maintenance. It puts Denton County at 4.8 months of home supply.
For a cash-out, that is a direct hit to the denominator. The loan amount comes from appraised value, so a conservative appraisal shrinks the proceeds, and the 75 percent cap applies to that number, not to what the owner thinks the house is worth. Underwrite below your own estimate.
North Denton, the Square, and Southridge
North Denton (76209) offers the lowest entry basis of the zips profiled, a median near $359,000 per Destination: North Texas, with housing stock mostly built in the 1960s and 1970s. The same guide says 76201, 76203, and 76209 have minimal new residential construction, and that 76203 and 76209 carry the highest rental concentration. No zip-level rent data was found, so the citywide house figure is the only anchor. Pull local comps before assuming a rent.
The downtown core and Square (76201) sit near UNT and include Rayzor Ranch. Rent.com shows one-bedroom apartments at $1,100 in the Oak Hickory Historic District and $1,145 downtown. That’s apartment data, not a house rent series. Tenants skew toward students and young professionals, which suits older duplexes and small multifamily more than a single-family cash-out.
Southridge and Forrestridge (76205) are a different problem. Destination: North Texas puts Southridge medians at about $456,000 to $534,000, and Forrestridge near $518,000 on Zillow’s typical value. RentCafe puts the Southridge apartment average at $1,179. High basis, modest rents, tight coverage. These have the most equity on paper and the thinnest cash flow.
South-southeast (76210), with a median near $413,000 and newer subdivisions along I-35E, sits in between. It has a higher price basis than 76209 and a weaker rent ratio.
Two Universities and a Hospital Corridor
Demand is the part of the Denton case that doesn’t wobble. UNT enrolled 42,016 students in the latest fall term, per Community Impact, down from 43,567 the prior fall, mostly from a loss of more than 1,300 international students. TWU enrolled 16,412, up 5.9 percent. Discover Denton puts combined enrollment above 55,000.
The renter base reflects it. The Denton Economic Development Partnership lists 35,377 rented units against 30,101 owner-occupied, in a city of roughly 150,000 to 160,000 people, per the city’s own trend report. Medical City Denton lists more than 1,100 employees, and Texas Health Presbyterian sits on I-35 as well. UNT’s enrollment dip is a small headwind, not a thesis-breaker.
Working DSCR brokers see a recurring pattern in college-anchored suburbs with a heavy apartment pipeline: the demand story is sound, but the file gets stuck on the rent figure. Lenders order a rent schedule or market rent opinion, and in a concession-heavy market the opinion often lands below what the owner collects from a long-term tenant. Showing a signed lease, rent history, and a conservative comp set up front tends to head off a surprise at appraisal.
Small Multifamily: A Different Basis
Duplexes, triplexes, and fourplexes near the campuses and the Square are the property type most worth a second look. Homes.com shows 20 multi-family listings in the city, priced from $330,000 to $1,500,000. No verified per-unit rent series exists for Denton multifamily, so any coverage figure here is a guess until the actual rent roll is in hand.
The structural argument holds anyway. Several doors on one loan spread vacancy across units, and the price per door is lower than a standalone house at the citywide value. An owner already holding a small multifamily with built-up equity has a better cash-out candidate than an owner of a recent single-family purchase. Conversely, if the property’s rent roll sits well below market and a unit is vacant at the time of appraisal, the refinance may be better deferred.
Hold or Refinance Now?
The supply cycle is the swing factor. Apartment List shows Denton’s median rent at $1,175, down 9.5 percent year over year, and 17.0 percent below the $1,416 Dallas-area median. Matthews, citing CoStar, expects DFW vacancy to peak before tightening, with rent recovery lagging, and notes that Collin and Denton Counties capture a large share of new residents. A secondary aggregator relaying Dallas Fed-linked forecasts says the under-construction pipeline has shrunk from about 42,700 units toward roughly 30,200. Verify that last figure against a primary source before leaning on it.
Rent sources disagree on direction, too. Zumper has the average at $1,650, up 3 percent, while RentCafe’s 50-plus-unit average is $1,529, down 4.57 percent. The gap partly reflects what each measures, since RentCafe’s figure covers only large apartment buildings.
This is a genuine toss-up. Refinancing into a soft-rent appraisal locks in a value and a rent opinion at or near the trough. Waiting risks missing equity if prices slide further, and flat prices mean there’s no appreciation to wait for. Investors who need the capital for a deal that pencils today have a reason to move. Investors who are only curious about equity may have a reason to wait.
New west-side supply also matters. Destination: North Texas says Landmark by Hillwood has 747 lots in its first phase with nine builders, and Remote Prop View reports Cole Ranch breaking ground on 3,100 acres and about 4,365 homes. What follows is an inference, not a sourced conclusion: builder incentives on the west side could cap prices and rents on older nearby houses. Campus, downtown, and north-side houses face less of that pressure.
What the Proceeds Do Next
Cash-out proceeds are only as good as their next use. Pulling equity to buy another Denton rental where the coverage math clears 1.00 at entry, perhaps a small multifamily near the Square, is straightforward. Pulling equity to chase a market where the numbers don’t pencil is a different decision, and one worth stress-testing before committing.
Compare the options. How the two loan types differ matters here: a W-2 investor with a single rental and clean traditional personal-income documentation may find conventional cash-out financing cheaper. DSCR tends to pencil better for entity-held portfolios and self-employed borrowers, or for anyone with more than four financed properties. While other platforms limit LLC eligibility to specific vesting structures, the brokerage works with lenders whose programs cover a broader range of entity setups, subject to lender program eligibility. For more on the refinance side, review the DSCR loan options for Texas investors.
Investors who want a coverage read before ordering anything can compare DSCR options or reach the team at 828-256-2183. Verify current local rental rules, taxes, and insurance with qualified local professionals before committing.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Denton, TX, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR loan in Denton?
Qualification centers on the property’s rent compared with its full monthly obligation, typically with a 1.00 benchmark and a 620 credit floor on most files. Lenders also review reserves of around six months and order a property appraisal and rent opinion. Because Denton’s apartment concessions can pull market-rent opinions below actual collections, a signed lease and rent history help the file. Everything remains subject to lender guidelines.
What are the requirements for a cash-out refinance on an investment property in Denton, Texas?
Expect a 75 percent loan-to-value ceiling, about six months of seasoning from title recording, a minimum 1.00 coverage benchmark, and reserves near six months. Standard programs go up to $3,000,000. Smaller balances route through select lenders. Manufactured homes, log homes, and barndominiums fall outside these programs.
Can a self-employed investor buying in Denton be reviewed for DSCR financing?
Yes. Lendmire arranges DSCR investor loans through wholesale lending channels. Because eligibility is generally reviewed around the property’s rental income rather than personal income documents, self-employed borrowers can be considered, subject to lender guidelines.
Why does Denton’s cash-out math look tighter than the rent-to-price ratio suggests?
The headline ratio is about 0.60 percent a month on citywide figures, but that ignores taxes and insurance in the full obligation, and it assumes a citywide price that doesn’t match many entry-level houses. The ratio also depends heavily on which price series is used: it drops to about 0.45 percent against the Redfin county median. Appraisal and rent-opinion conservatism then reduce proceeds further.
Are Denton’s apartment concessions a problem for single-family cash-out refinances?
They can be. Apartment concessions compete directly with single-family and small-plex rentals, so lenders may use flat or conservative rents. Underwrite on in-place leases rather than peak asking rents.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
The Choice in Front of a Denton Holder
Denton leaves an investor holding equity with two honest options. One is refinancing now at reduced leverage, accepting a smaller draw in exchange for coverage near 1.00 and capital that can go into the next deal immediately. The other is holding through the apartment supply peak, accepting idle equity while betting that a thinner pipeline and two campuses with more than 55,000 students bring rents back.
About Lendmire
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that helps arrange investor financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. DSCR eligibility is generally reviewed by the lender on the property’s rental income rather than personal income documentation, subject to lender guidelines. That works for self-employed investors, LLC operators, and portfolios above four financed properties. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. $2,100 median house rent Zumper reports
2. Zillow — Home Values Denton TX
3. Redfin’s Denton County data
5. Rent.com
6. RentCafe
7. UNT
10. Denton Economic Development Partnership
11. Cityofdenton.com — View Qtr FY Stand
13. Homes.com
14. Matthews
15. Remote Prop View
16. 2025
17. 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Haltom City, Texas: The 2026 DSCR Financing Guide to Denton Highway · DSCR Cash Out Refinance in Desoto, Texas: The 2026 DSCR Financing Guide to Pleasant Run Road · Cash Out Refinance Investment Property Denton Texas
Guides: Investment Property Cash-Out Refinance in Denton, TX · Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.