
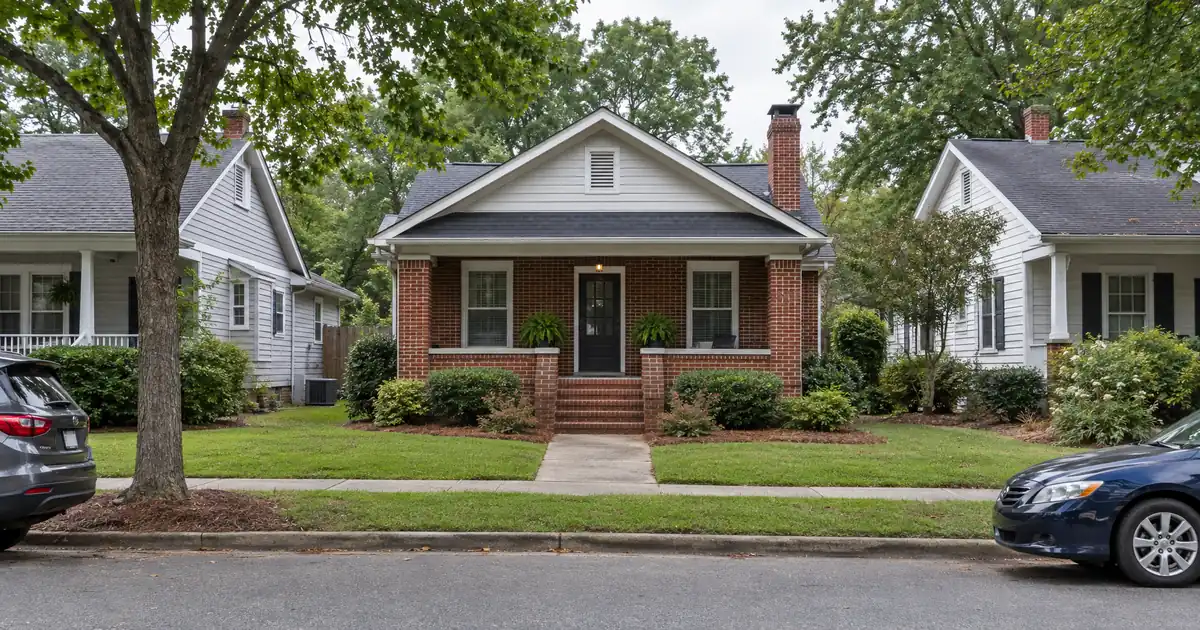
Redfin shows Matthews median sale price at $535K, up 7.0% year over year, while Zillow shows rent up just $6 over the prior year. Values climbed. Rents stood still. That gap is the whole story for anyone sitting on a Matthews rental and wondering how much equity can come out of it.
Lendmire, a DSCR-focused mortgage broker (NMLS# 2371349), sees this pattern often in appreciation-led suburbs. The equity is real, but the rent doesn’t always carry the new loan. For real estate investors in Matthews, North Carolina, Lendmire helps structure and place DSCR financing through wholesale lenders operating in 41 markets, including D.C. This piece is about the owner who already holds the property and wants the capital out.
DSCR Cash-Out Calculator
Run the cash-out numbers in Matthews, NC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 1, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 1, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A DSCR cash-out refinance in Matthews, North Carolina is underwritten primarily on the property’s rental income measured against its full monthly obligation. It is sized to a leverage ceiling rather than the borrower’s personal income, so an investor can convert equity in an already-owned rental into capital, subject to lender guidelines.
- Median-rent single-family homes model well under 1.00x at maximum leverage, taxes and insurance included.
- Townhomes are the lower-basis product, with a $405K median asking price on Redfin.
- Cash-out typically tops out at 75% LTV after about 6 months of ownership.
- Charlotte-area rents are soft, so size the loan on today’s rent, not a recovery.
- Duplexes are the best-supported small multi-unit type here. Triplex and fourplex stock looks thin.
Matthews Market Snapshot
A quick read on the Matthews investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $445,100 median value (Data USA, Matthews) |
| Typical rents | $1,516 asking (Matthews Real Estate Investment) |
| Cap rates | 5.0% cap rate (Matthews Real Estate Investment) |
| Employment | ~40,000 system employees (Business North Carolina, Novant) |
| Vacancy | 6.2% (Matthews Real Estate Investment) |
The Math Most Matthews Owners Skip
Single-family rent in Matthews does not cover a high-leverage cash-out. Using Homes.com’s $2,252 median home rent against the $535K median price gives roughly 0.42% monthly rent-to-value. That’s a back-of-envelope figure across two sources with different methods, but the direction is clear.
Run the numbers on a modeled example. Assume a home valued near the median and rent at $2,252. Model a standard 30-year structure with full taxes and insurance counted. At 75% LTV, coverage lands around 0.7x. At 60% LTV, it improves to the low 0.8s. At 50% LTV, it gets to just under 1.00x. Those are modeled assumptions, not quotes, and I rounded down on purpose. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Coverage depends on the new loan balance, not on how much equity you have. That’s the lever. An owner with a large cushion can take a modest cash-out, keep the balance small and still clear the standard 1.00x benchmark. An owner who wants every last dollar at the 75% ceiling on a median-priced house probably can’t, unless the rent is well above the median. The most any file can pull is also capped by reserves (typically about 6 months of PITIA) and whatever the lender’s review allows.
If a file lands under 1.00x, there are structures a lender may review. These include a sub-1.00 program with reduced leverage and stronger credit, an interest-only structure or a smaller draw. Each one comes with tradeoffs, and qualification stays subject to lender guidelines, credit approval and property review.
DSCR files in markets like this one typically show the same tension. Appraised values come in strong while market rent comes in flat or lower, so the lender’s rent figure, not the owner’s hoped-for number, drives the sizing. The cleaner files usually arrive with a signed lease, a recent rent comp pulled from the same submarket and a deliberately conservative ask. Reserves are the other pinch point. Where many non-QM platforms require reserves that don’t match the investor’s file, the broker’s job is to find a program whose reserve requirement fits what the borrower actually holds.
The guide “What Is a DSCR Loan” is simple: monthly rent divided by the full monthly obligation. The cash-out qualification details cover seasoning, credit tiers and reserves in more depth.
Where Matthews Equity Comes From
Matthews equity comes from price appreciation in a built-out commuter town, not from rent growth. Data USA shows about 30.6K residents, a 64.4% homeownership rate and a $445,100 median property value. That’s an owner-heavy town where rental supply is limited and the buyers who pay up for the location are the same ones who would otherwise rent.
Demand is anchored by healthcare and corporate Charlotte. Novant Health operates Matthews Medical Center, and Business North Carolina reports a four-story, 150,000-square-foot tower, framed as a $170M expansion. Harris Teeter is headquartered in town. Beyond that, residents commute 25 minutes on average to Uptown, SouthPark and Ballantyne, with Uptown roughly 12 miles away.
There’s a catch. No rail line serves Matthews, and the planned LYNX Silver Line extension has been slow to develop. Demand is by car along US-74 and I-485. That supports the rental base for commuters but leaves the town without the transit-driven rent premium some Charlotte corridors enjoy.
Matthews is also a market where sources disagree. Redfin’s $535K and a local agent’s roughly $481K (down about 5.7%) describe the same town in different months with different methods. Treat the level as roughly $480K to $535K. Apartment List adds that Matthews’ median rent runs 14.3% above the metro median, so the town is not cheap to rent, just not rent-rich relative to its price.
Honestly, this is an appreciation-led market. A cash-out here leans on equity already built, not on rent coverage doing the heavy lifting. Investors who bought a few years ago hold the strongest hand. Recent buyers at today’s prices have less cushion and thinner coverage.
Townhomes and Duplexes: The Lower-Basis Play
Townhomes and duplexes carry the best coverage odds in Matthews. Redfin lists 54 townhomes for sale at a median asking price of $405K, about $130K under the single-family median. To clear 1.00x at 75% LTV on that product, modeled rent would need to land near 0.6% of value per month, including taxes and insurance. I found no reliable townhome rent band for Matthews, so pull actual comps before assuming anything. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Listings in that Redfin snapshot sit on the market a long time. That gives buyers negotiating room, and it signals a slow exit if a refinance ever has to be unwound. Plan on holding.
Duplex is the best-supported multi-unit type. The town’s development ordinance defines the two-family duplex as a distinct building type, and a Planning Board packet describes duplexes alongside townhomes and cottages as part of mixed-residential planning. Stock exists. Inventory isn’t deep, and I found no count.
Skip the idea that Matthews is a fourplex market. Triplexes and fourplexes look scarce here, and the nearby Charlotte submarkets carry more of that stock. If small multifamily is your goal, Matthews is more likely the place you pull capital out of than the place you put it back in.
New supply is mostly small infill. A local property manager notes that new inventory arrives as townhome projects starting in the $300,000s rather than large subdivisions. That’s a manager’s marketing description, so treat it as qualitative. Still, limited new supply helps the comp base for existing rentals at refinance.
What Soft Charlotte Rents Mean for Your Appraisal
Charlotte-area rents are soft, and a Matthews cash-out should be sized as if they stay that way. Matthews Real Estate Investment Services (the brokerage, not the town) reports Charlotte multifamily vacancy of 6.2%, asking rent of $1,516 and a 3.2% year-over-year decline, with more than half of properties offering concessions. Its average cap rate sits at 5.0%. It forecasts a return to modest positive rent growth, around 1.8%, but that’s a forecast, not something to underwrite against.
Locally, Apartment List shows Matthews rents down 3.4% year over year, and Zillow describes the rental market as “cool.” An appraiser may set market rent below your asking rent, and that lower figure becomes the lender’s number. Underwrite on flat or slightly lower rent and treat any lift as upside.
The supply picture is improving. Northmarq reports about 4,800 net move-ins in a single quarter, a regional peak, and expects vacancy to hold steady as supply pressure eases. It also notes rents have trended lower over three years. Job growth is the support: Northmarq cites roughly 30,000 jobs added over two years. Rents haven’t recovered, but occupancy has a floor.
Neighborhoods: Where Cash-Out Files Look Best
Not every pocket of Matthews works equally for a refinance, and I found no reliable per-neighborhood price or rent data. What follows is tenant-base logic, not numbers.
Historic Downtown and Trade Street is the strongest story. Apartments.com describes loft-style homes around downtown and Trade Street, and older brick ranches in Pine Forest sit near the core. These are the closest thing to lower-price single-family entry points in town, and the walkable location draws young professionals. An agent page on Pine Forest is dated, so it’s directional only.
NC-51 and Sycamore Commons pairs retail employment with larger apartment communities. Renters here are service workers and commuters, and the product is more apartment than investor house. Good for a rent comp, less so for a cash-out target.
Idlewild Road and the CPCC Levine area is worth a look. Central Piedmont Community College has a campus there, and healthcare workers tied to the Novant footprint are an obvious tenant base. I found no enrollment figure, so I won’t give one. Mid-term furnished stays for traveling clinicians are plausible, but there’s no Matthews-specific data, so I wouldn’t underwrite it.
East John Street, the Sportsplex and the Four Mile Creek Greenway has newer apartments near parks. It’s competition for small-unit rentals more than a place to hold one.
Now the caution. Crestdale and Brightmoor are primarily owner-occupied single-family. Rental comps will be thin, and a thin comp set makes appraisers conservative. If you own a rental there, expect more scrutiny on the rent side of the file.
The stronger play might be a lower-basis townhome or duplex over a high-value single-family for coverage, though an owner with major equity in a premium house could argue for a smaller draw instead. It’s a genuine toss-up, and it depends on how much capital you need versus how much coverage you can tolerate.
Recycling the Proceeds
The point of a cash-out is the next deal, and Matthews is likelier to fund an acquisition elsewhere than to host one. Charlotte’s cheaper submarkets carry more small multifamily and better rent-to-value. A Henderson Property Management note makes the same point: Ballantyne, Matthews, Fort Mill, Mooresville and Monroe each need different pricing and marketing strategies. Draw only what the new property’s coverage and your reserves can support.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Matthews, NC, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Before sizing anything, check local rental rules, taxes and insurance with qualified local professionals. If you’re weighing structures, it’s also worth learning more about refinancing and about how conventional and DSCR financing compare for investor loans. When you’re ready, see what the numbers look like or call 828-256-2183.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Matthews, North Carolina?
Qualification is built on the property’s rent versus its full monthly obligation, with 1.00x as the common benchmark. Typical guidance also includes about 6 months of seasoning, credit minimums starting around 620 and reserves near 6 months of PITIA. Lenders review each file against their own guidelines, and some will look at sub-1.00 scenarios with lower leverage. See DSCR loans in North Carolina for the state overview.
What are the requirements for a cash-out refinance on a Matthews rental?
Expect a leverage ceiling of 75% LTV, a rent figure supported by appraisal or lease and a seasoning period of about 6 months from title recording. Credit tiers generally run 620, 660, 680 and 700, and higher scores may improve pricing options. Available proceeds depend on rent, PITIA, reserves and the LTV cap, so no cash figure is guaranteed.
Do townhomes or single-family homes work better for cash-out in Matthews?
Townhomes usually pencil better because the basis is lower. Redfin’s townhome median asking price runs well under the single-family median, so the same rent covers a smaller balance. Single-family homes near the $535K median model well under 1.00x at full leverage. Pull same-submarket rent comps before choosing.
Will soft Charlotte rents reduce what I can pull out?
They can. Appraisers may set market rent below asking, and that lower number drives coverage. With metro rents down year over year and concessions widespread, plan on flat rent. A smaller draw or lower LTV can keep the file above 1.00x.
What loan-amount ranges may DSCR lenders review for Matthews rental properties?
Lendmire arranges DSCR investor loans. Standard programs typically run up to $3,000,000, and smaller balances route through select lenders in the network. Eligibility depends on borrower, property and lender guidelines.
What the Next Two Years Probably Hold
Over the next 6-24 months, expect Matthews to stay appreciation-led with rent coverage improving slowly. Northmarq sees Charlotte vacancy holding steady as supply pressure fades, and the Matthews brokerage forecasts modest rent growth returning. Neither is a call for a rent surge. Owners who locked in equity during the run-up have time to refinance at a measured LTV, while those waiting for rents to rescue a 75% draw will probably wait longer than they’d like. The Novant tower and steady Charlotte job gains should keep tenant demand intact even as rent growth stays muted.
About Lendmire
Lendmire, NMLS# 2371349, is a mortgage brokerage focused on investor financing. It arranges DSCR loans in 40 states plus Washington, D.C., which makes 41 markets in total. Qualification centers on the property’s income rather than personal income documentation, subject to lender guidelines. That structure suits LLC-held rentals and growing portfolios, depending on program guidelines. Lendmire was recognized by Scotsman Guide as a 2026 Top Workplace and recognized by Scotsman Guide in 2025. See Lendmire’s 2026 Top Workplace announcement for details.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin, Matthews housing market
2. Zillow Rental Manager, Matthews
3. $405K median asking price on Redfin
5. Matthews Real Estate Investment Services, Charlotte multifamily report
6. Business North Carolina, Novant expansion
7. Homes.com, Matthews rentals
9. Apartment List — Rent Report Matthews
10. matthewsnc.gov — Development ordinance
13. Northmarq, Charlotte multifamily report
14. northmarq.com — Asking Rents Post Quarterly Increase Charlotte Multifamily Market 2026
15. Central Piedmont Community College
16. hendersonpropertymanagement.net — Charlotte Property Management Trends
17. recognized by Scotsman Guide as a 2026 Top Workplace
18. recognized by Scotsman Guide in 2025
19. Lendmire’s 2026 Top Workplace announcement
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Matthews, North Carolina: Thin Rents, Real Equity · Cash Out Refinance Investment Property Huntersville North Carolina · Cash Out Refinance Investment Property in Waxhaw, North Carolina: Equity Outruns Rent
Guides: Investment Property Cash-Out Refinance in North Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.