
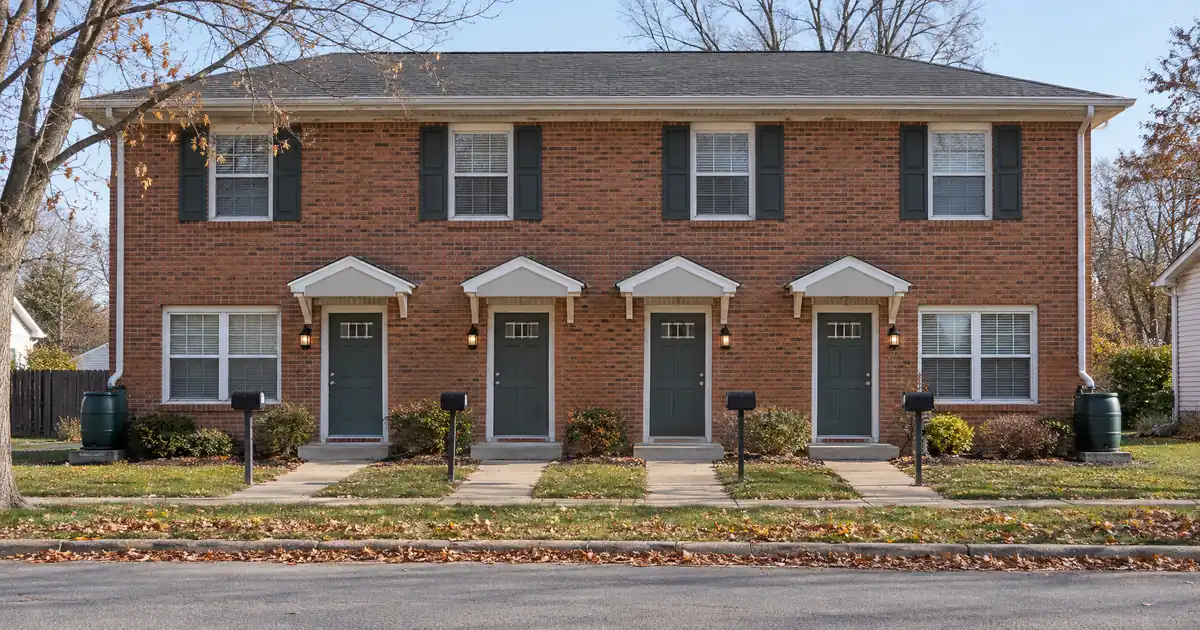
The Quick Read: A jumbo cash-out refinance on a fourplex you live in is a real option, but it is underwritten more tightly than the same loan on a single-family home. The lender looks hardest at the appraised value, your credit, your reserves, and how your debts compare to your income. Across the wholesale jumbo programs Lendmire works with, leverage on a cash-out sits below the purchase ceiling, and the exact limits depend on the lender, the loan amount, and a full file review.
What Makes a Fourplex Cash-Out “Jumbo”?
A cash-out refinance is jumbo when the new loan is larger than the conforming limit for your county and unit count. Jumbo starts one dollar above that limit. Because the limit rises with the number of units, many fourplex loans stay conforming at sizes that would be jumbo on a house.
Jumbo cash-out estimate
Enter the value, the balance, and the cash wanted; choose the occupancy and the structure; the lanes, the payment, and the reserves follow.
Editable benchmark: 7.24% as of October 29, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not a jumbo cash-out refinance quote.
Illustrative starting assumptions: a $2,000,000 home value in the jumbo range, a $1,000,000 current balance, a principal residence on a thirty-year fixed structure at the current Freddie Mac conforming benchmark, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conforming benchmark, a market reference and not a jumbo cash-out refinance quote; a jumbo loan is priced by the lender at lock. The lanes shown are the wholesale cash-out lanes behind this page as of the snapshot date; the calculator reads each lane’s leverage, loan maximum by occupancy, cash-in-hand cap, and reserves as the lane table states them, and a Lendmire loan officer confirms the lane on the file. The cash available is the loan the lane allows less the balances paid off, before closing costs, which are not included; on most lanes a jumbo cash-out begins one dollar above the conforming limit for the county, and two lanes start at a stated dollar floor instead. The HELOC line is the line program’s combined loan-to-value ceiling applied to the same value and balance. Taxes and insurance are editable estimates. Licensed in sixteen states for consumer mortgages.
The federal housing agency sets those limits each year. In high-cost areas, FHFA’s limit addendum calculates the two-, three-, and four-unit limits from 115 percent of the local one-unit median home value, then applies unit multipliers. The numbers change annually and vary by county, so look up yours in FHFA’s county table. Don’t trust a figure you saw in a blog post.
A cash-out refinance, in plain terms, means you take a bigger mortgage, use part of it to pay off the current loan, and keep the rest as cash. That cash is what pushes many fourplex owners over the line.
Key Terms Defined
Jumbo loan: a mortgage above the county’s conforming limit for that unit count.
Cash-out refinance: a new, larger loan that pays off the old one and hands you the difference.
LTV (loan-to-value): the loan balance divided by the appraised value of the property.
CLTV (combined loan-to-value): all loans on the property, including a second lien, divided by the appraised value.
Reserves: money left in the bank after closing, counted in months of your full housing payment.
DTI (debt-to-income): your monthly debts divided by your monthly income.
Is a Fourplex a Commercial Property?
No. One to four units is residential. If you live in one unit, the building is a 2–4 unit primary residence, and it is financed as a consumer mortgage. Five or more units is commercial and falls outside this kind of loan.
That matters for two reasons. Consumer rules and disclosures apply, including the Loan Estimate and Closing Disclosure. And the lender will ask you to prove you intend to live there. Occupancy is the first fork in the road, and lenders take misstatements seriously. If the building is not your home, the same programs use different leverage by occupancy. That is a separate conversation from this one.
How the Loan Is Underwritten, Step by Step
Here is the order a lender works through. Jumbo lenders often borrow the agency framework as a baseline and then tighten it.
1. Classify the property. The lender confirms the fourplex is your primary residence and that you occupy one unit.
2. Order the appraisal. Fourplexes use an income-property report that lists the market rent for each unit. Value sets everything that follows.
3. Run the equity test. The lender divides the new loan by the appraised value.
4. Check credit and reserves. Scores, payment history, and cash left after closing all get reviewed.
5. Calculate income and DTI. This is where rent from your other units gets treated, covered in its own section below.
6. Review documents and title. Income, assets, insurance, tax bills, leases, and the payoff statement all go in.
If you want the program-level view, Lendmire’s jumbo cash-out refinance program page lays out the structures available.
What Does the Equity Test Look Like?
Cash-out leverage is lower than purchase leverage, and multi-unit cash-out is usually tighter still. Across the wholesale jumbo lanes we place files with, the headline lane starts at a 660 decision score. Leverage on the strongest lanes tops out at 90% LTV, and several lanes reach 89.99% CLTV when a second lien is involved. The rest stop at 80%. Those are the purchase ceilings. A cash-out refinance sits below them, and some of the largest lanes put a cash cap on how much you can take out.
Agency loans publish their own maximums by occupancy and unit count. Fannie Mae’s Eligibility Matrix is where to see them. Multi-unit owner-occupied cash-outs carry a lower ceiling than one-unit homes there, and jumbo lenders generally do not go looser.
The practical result: on a fourplex, you can usually pull less equity than a single-family owner with the same percentage of equity.
How Is Rent From the Other Units Counted?
Rent from the units you don’t live in can help, but it rarely counts dollar for dollar. Fannie Mae’s Selling Guide on rental income says rent from the unit you occupy generally can’t be used to qualify. Rent from the other units can count, and the appraisal must state a monthly rent for each unit.
Lenders apply a vacancy haircut, so only part of the gross rent is credited. They usually want leases, proof of rent received, or the appraiser’s market-rent schedule to back it up. Some jumbo lenders count less of the rent than the agencies do. A few count none.
That swing is why two lenders can look at the same fourplex and return different DTI numbers. Across the jumbo lanes, the ratio ceiling is 50% on the fixed lanes, 45% on the adjustable lanes, and 43% on the interest-only lanes. Where your rent lands in that calculation can decide which lane fits.
Credit, Reserves, and Loan Size
Credit and reserves scale with the loan. A bigger loan means a higher bar. Here is how the pieces fit.
| Factor | How it works on a fourplex cash-out |
|---|---|
| Credit | 660 decision score on the headline lane |
| Leverage | Lower on cash-out than purchase |
| Loan size | Up to $5,000,000 on the largest lanes |
| DTI | Limits vary by payment structure (fixed, adjustable, or interest-only) |
| Reserves | Months of full payment, rising with amount |
| Appraisals | Two required above a lane’s threshold |
Reserves deserve a note. Lenders count them in months of your full payment (principal, interest, taxes, and insurance). On a fourplex, that payment is larger than on a typical house, so the cash you need to show is larger too. Pulling equity out does not count toward reserves unless the lender’s guidelines allow it.
What Happens With Two Appraisals?
On larger loans, some lanes require two appraisals once the amount passes that lane’s threshold. The lender typically uses the lower value or reconciles the two. Either way, the lower number sets your LTV.
Fourplexes are harder to appraise than houses. Comparable sales of four-unit buildings are scarce, and the appraiser has to build the value from limited data and the rent schedule. A low appraisal is the most common way a fourplex cash-out shrinks or stalls. Lendmire’s piece How Two Appraisals Size a Jumbo Cash-Out Refinance on a Primary Home walks through that process.
Where the General Rule Breaks
A few edge cases change the answer.
- Conforming, not jumbo. If the new loan stays under your county’s four-unit limit, you may be in conforming territory, with different rules.
- State restrictions. Some states limit cash-out refinancing on certain properties. Texas is a well-known example, and state law can rule out a route that works elsewhere.
- Condo or non-warrantable fourplexes. Two of the jumbo lanes accept non-warrantable condominiums, which matters if your building sits in a project that agency loans reject.
- Occupancy mix. Primary, second-home, and investment occupancy each carry lane-specific leverage. A building you don’t live in is underwritten differently.
- Unusual rent. Vacant units, below-market leases, and short-term rentals can all shrink the rent the lender credits.
- Five or more units. That is commercial and outside this loan.
What Should You Compare Before You Refinance?
Compare the full cost of the new loan to the loan you have now. A cash-out refinance replaces your existing mortgage, including its rate and term. If your current loan has favorable terms, you give those up on the whole balance, not just the cash you take.
The CFPB’s guide to using home equity warns that a cash-out may extend your payoff time and raise your payment, because you replace your loan with a bigger one. The agency’s research also found that borrowers often use the money to pay down other debts, and that credit card balances tended to creep back toward their earlier levels within a year, per the CFPB’s report on cash-out borrowers.
Closing costs on a larger multi-unit loan include the income-property appraisal, title work, and possibly a second review. Your Loan Estimate itemizes them. Read it line by line.
Consider the alternatives too: keeping the first loan and adding a second lien or home equity line, or a smaller cash-out. Each reaches a different amount of equity at different leverage.
Common Reasons Files Stall
- Low appraisal. Fix: provide the rent schedule, recent improvements, and any comparable four-unit sales you know of.
- Thin reserves. Fix: document more liquid assets, or borrow less.
- High DTI after the rent haircut. Fix: pay down debts, or look at a lane with a higher ratio ceiling.
- Credit below the lane’s floor. Fix: address late payments and card balances before applying.
- Missing leases or rent proof. Fix: gather signed leases and bank records showing rent received.
A Worked Example
Say you own a fourplex, live in one unit, and want to take cash out. The lender’s appraisal values the building, and the loan you want is 75% of that value. That is under the lane’s leverage ceiling, so the equity test passes, subject to the lane’s cash cap.
Rent from your three other units is reduced by a vacancy haircut, then added to your income. The full new payment goes in your debts. Your DTI lands under 50% on a fixed lane. Your reserves cover the months the lane requires for that loan size. Credit clears 660.
Change one input and the result shifts. A lower appraisal raises the LTV. Less rent credit raises the DTI. That is why a pre-file review matters before you pay for an appraisal. This example is illustrative only, and actual terms depend on lender guidelines and full file review.
Tax treatment can depend on your situation; borrowers should speak with a qualified tax professional before relying on any deduction or credit.
Frequently Asked Questions
Can I do a jumbo cash-out refinance on a fourplex I live in?
Yes, in many cases. You must occupy one unit, and the loan has to exceed the conforming limit for your county’s four-unit size to be jumbo. Leverage is lower than on a purchase, and approval is subject to lender guidelines and full file review.
Does the rent from my other units count as income?
Partly. The unit you live in doesn’t count. Rent from the others is usually reduced by a vacancy haircut and backed by leases or the appraiser’s rent schedule. Some jumbo lenders credit less than the agencies do.
Why might I get less cash out than on a single-family home?
Multi-unit owner-occupied cash-outs carry lower maximum leverage, and a fourplex is harder to appraise. A lower value or a lower ceiling means less equity available to borrow against.
How much can I borrow?
On the largest wholesale jumbo lanes, loans reach $5,000,000. Smaller lanes cap lower. A cash cap may limit how much of that is cash in your hands on a cash-out.
What is the biggest risk of a cash-out?
You replace your existing loan, with its rate and term, with a larger one. That can raise your payment and lengthen your payoff. Compare the full cost of both loans on your Loan Estimate.
If you are weighing a cash-out refinance against keeping the loan you have, Lendmire can help you compare the programs and the equity each one reaches. Reach the team at 828-256-2183.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage serving homeowners and home buyers in 16 states. FHA, VA, conventional and jumbo purchase and refinance loans are arranged through wholesale lending channels; Lendmire brokers the financing and the lender underwrites each application. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
For the program’s current guidelines, see jumbo loan programs.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. FHFA – 2026 Conforming Loan Limit Addendum
2. Fannie Mae – Eligibility Matrix
3. Fannie Mae Selling Guide – Rental Income
4. CFPB – Using Home Equity Guide
5. CFPB: CFPB Report Finds Cash Out Mortgage Refinance Borrowers Improve Credit Scores
This article is part of Lendmire’s jumbo cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Best Jumbo Cash-Out Refinance Program to Go Fixed · Jumbo Cash-Out Refinance Requirements Within the Seasoning Period · Jumbo Cash-Out Refinance Rules on an Inherited Property
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.