
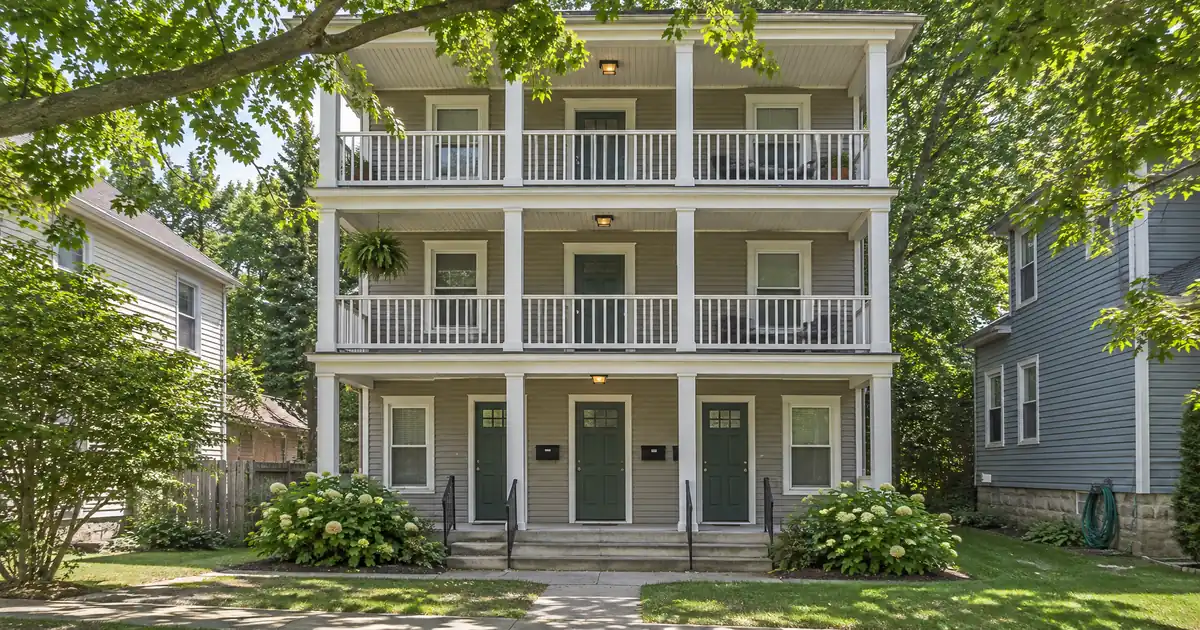
The Quick Read: A VA cash-out can reach 100% of the appraised value of a triplex, as long as you live in one of the three units. That ceiling applies to the whole building, rented units included. The financed funding fee and the payoff of your current loans come out of that 100%, so the cash that lands in your hands is smaller. Everything here is subject to lender guidelines and full file review.
What a VA Cash-Out on a Triplex Actually Is
A VA cash-out refinance replaces your current mortgage with a new VA-backed loan and lets you borrow against the equity. The old loan can be any type: conventional, FHA, or VA. That is a real strength of this program.
VA cash-out estimate
Seeded with an example value, a typical balance, and a round cash request at the first-use fee; change any field.
Editable benchmark: 7.18% as of November 5, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not a VA cash-out refinance quote.
Illustrative starting assumptions: a $350,000 home value, a $193,000 current balance, the full-value VA cap with the first-use funding fee financed, a thirty-year term at the current Freddie Mac benchmark, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conventional benchmark, a market reference and not a VA cash-out refinance quote; a VA loan is priced by the lender at lock. The total loan, funding fee included, is capped at the program leverage on the reasonable value; the fee follows the tier chosen. The cash available is what the cap allows less the balances paid off and the fee, before closing costs, which are not included. The HELOC line is the line program’s combined loan-to-value ceiling applied to the same value and balance. Taxes and insurance are editable estimates. The debt-to-income figure is a guideline; residual income decides a VA file. Licensed in sixteen states for consumer mortgages.
The occupancy test is the gate. VA’s own cash-out page says you need a Certificate of Eligibility and must plan to live in the home you are refinancing. VA’s purchase and cash-out program page describes the loan as refinancing the first mortgage on the home you own and occupy.
A triplex fits because you live in one unit and rent the other two. VA’s pages don’t spell out a unit count, and lenders commonly work from a limit of up to four units. Lendmire’s VA cash-out refinance program page covers the program basics if you want the short version.
One more point. VA does not lend the money. VA backs the loan, and a private bank, mortgage company, or credit union makes it. Lendmire is a mortgage broker, so it arranges these loans through wholesale lenders and never lends directly.
The Ceiling: How Much Can the Loan Be?
The ceiling is 100% of the appraised value, and it includes the financed funding fee. That number sets the outer edge of the loan.
This was not always true. VA once capped cash-out loans at 90% of value. In a 2018 rulemaking, VA replaced that cap with a 100% ceiling. The 90% figure now lives on only as one of the net tangible benefit tests. If you read an old article saying VA stops at 90%, it is out of date.
There is one narrow case where 90% still bites. The VA Lenders Handbook, Chapter 6 limits a fixed-to-adjustable refinance with more than one discount point to 90% of reasonable value. Most borrowers never touch that case.
Two things about a triplex are worth stating plainly:
- The ceiling applies to the whole building. One property secures one loan, so the rented units sit inside the value.
- Rent does not raise the ceiling. Rent only affects whether you qualify.
Some lenders set a cap below VA’s. A lender’s own overlay can cut your payout even when VA would allow more. Worth asking early.
From Appraised Value to Cash in Your Hands
The math is a short subtraction. Start with the ceiling, then take out what has to be paid before you see a dollar.
Here is the sequence, using percentages only:
1. Take 100% of the appraised value. That is the most the new loan can be. 2. Subtract the payoff of your existing mortgage and any other liens on the building. 3. Subtract the funding fee if you finance it, since it sits inside the 100%. 4. Subtract any closing costs you choose to roll in, where the lender allows it. 5. What remains is your cash out.
Be careful not to read “100% means 100% in cash.” It doesn’t. If the fee would push you over the ceiling, you pay that piece in cash instead.
The funding fee on a cash-out refinance is 2.15% for first use and 3.3% for later use. It is waived for veterans receiving compensation for a service-connected disability and for the other exempt groups. The fee is a one-time charge you can finance, and it is described here mechanically, not as a price quote.
A triplex does not change this formula. A duplex or fourplex runs the same steps. What differs is the appraisal and the rental-income handling, covered below.
Key Terms Defined
Reasonable value: the value VA’s appraisal assigns to the property, which is the number the 100% ceiling is applied to.
Funding fee: a one-time VA charge on most loans, financeable into the balance and waived for exempt borrowers.
Net tangible benefit: a test showing the refinance gives you a real, measurable advantage. VA lists eight acceptable benefits, and a cash-out must meet at least one.
Seasoning: the waiting period before you can refinance. For a VA cash-out it is the later of 210 days from your first payment and the sixth payment.
Residual income: the money left each month after your debts, taxes, and living costs. For VA it is the controlling test.
Certificate of Eligibility (COE): VA’s document confirming you earned the benefit. VA decides eligibility.
How the Loan Is Underwritten, Step by Step
A cash-out is not a streamline. The lender looks at credit, income, and residual income, then reviews the whole file.
1. Eligibility and occupancy. You provide your COE and certify that you will live in the building. On a triplex, that means one unit is yours.
2. VA appraisal. Cash-outs require one. On a multi-unit property, the appraiser also documents market rent for the other units.
3. Credit and income. The wholesale programs I place VA loans with start at a 580 decision score. Some lenders set a higher floor. VA itself sets no minimum.
4. Residual income. This is the controlling test. The 41% debt-to-income figure is a guideline, not a cap. A ratio above it needs residual income well above the table.
5. Net tangible benefit. The loan must satisfy at least one of VA’s eight listed benefits. The half-percent rate-reduction and fee-recoupment tests belong to the streamline and don’t apply to a cash-out.
6. Seasoning. The waiting period above must be met.
Your new, larger balance feeds into steps 3 and 4. Taking cash out raises the balance, so it can tighten your residual income. VA News also warns that a cash-out adds to the balance, increases total interest over time, and restarts your amortization schedule. That tradeoff deserves a real look before you sign.
Counting the Rent From the Other Two Units
Many lenders count about three-quarters of documented or appraiser-estimated rent. The haircut covers vacancy and upkeep. Tenant-occupied units need leases. A vacant unit relies on the appraiser’s market rent schedule.
If you use rent to qualify, Chapter 4 of the VA Lenders Handbook says the lender must verify:
- cash reserves of at least six months of principal, interest, taxes, and insurance;
- your experience managing rental units, or the use of a property management company.
Two limits matter here. Equity in the property cannot count as reserves. Cash proceeds from a VA regular cash-out refinance cannot count either. The reserves have to be your own money.
Here is the gray area. The Handbook wording is written around a multi-unit property securing the VA loan, with purchases in mind. Whether a lender applies it to a cash-out on a triplex you already own is a matter of lender interpretation. In practice, lenders generally apply it whenever rent is counted. If you qualify on your own income without the rent, the reserve condition generally isn’t triggered.
You may hear about an FHA-style self-sufficiency test for three- and four-unit buildings. Treat that as a possible lender overlay, not a VA rule.
Where the General Rule Breaks
The 100% ceiling is the headline. These cases pull the real number down or take the loan off the table.
- A lender’s own cap. A lender can set a lower limit than VA, which trims your payout.
- A low appraisal. The ceiling is a percentage of appraised value, not your estimate of it.
- A large existing balance. Payoff comes out first. Little equity means little cash.
- State rules. Some states restrict cash-out percentages. Ask a loan officer about yours.
- A vacant or renovating unit. The appraiser’s rent estimate stands in for a lease, and the lender may ask more questions.
- Entitlement already used. If you used the benefit before, remaining entitlement is a quarter of the county limit minus entitlement used and not restored, per VA’s program page. With full entitlement there is no VA loan limit. With remaining entitlement, talk to a loan officer.
- A pure rental. If you don’t live in the building, a VA cash-out generally doesn’t fit.
- A streamline instead. The VA IRRRL refinances an existing VA loan with no cash back and no VA appraisal. It carries a 0.5% fee unless exempt, and it can work on a former home that is now a rental. It’s a different tool.
Three Common Situations
| Your situation | What changes |
|---|---|
| Current loan is conventional or FHA | VA cash-out refinances it into VA. Full underwriting applies. |
| Current loan is already VA | Cash-out or IRRRL. Only the cash-out gives cash back. |
| One unit is vacant | Appraiser’s rent schedule replaces a lease. |
Picture a borrower with a conventional loan on a triplex who lives in unit one. The two rented units cover a good share of the building’s costs. The borrower wants cash for a roof and a kitchen. The VA route replaces the old loan, finances the fee, and leaves a smaller check. If the borrower needs rent to qualify, six months of reserves from personal savings come into play.
The call is close for some borrowers. A cash-out with no mortgage insurance and a high ceiling is a strong tool. A bigger balance and a restarted schedule are real costs. This one’s a genuine judgment call, and it depends on what the cash does for you.
What to Gather Before You Apply
- Your Certificate of Eligibility.
- Leases for any rented units.
- Proof you will occupy one unit.
- Your own savings statements, if rent will count toward qualifying.
- Evidence of landlord experience, or a property manager agreement.
- Your current mortgage statement and payoff information.
Be ready to explain what the cash is for. It helps with the net tangible benefit review.
Frequently Asked Questions
Can I use a VA cash-out on a triplex if I rent out two units?
Yes, if you live in the third unit and certify that you will. VA ties cash-out loans to occupancy of the home. The rented units sit inside the building’s value. Eligibility is still subject to lender guidelines and full file review.
Does the rent from my tenants raise how much I can borrow?
No. The ceiling is a percentage of appraised value. Rent affects whether you qualify, since a portion of it can count toward income. It does not lift the maximum loan.
Can my cash-out proceeds cover the required reserves?
Reserves must be your own funds.
Does VA still cap cash-out loans at 90%?
Not generally. VA replaced that cap with a 100% ceiling. The 90% figure survives as a net tangible benefit option and in one narrow fixed-to-adjustable case. Some lenders also set their own lower caps.
Will I get the full 100% in cash?
No. Your payoff, the financed funding fee, and rolled-in costs all come out first. If the fee would push the loan over the ceiling, you pay that part in cash.
If you are weighing a cash-out refinance against keeping the loan you have, Lendmire can help you compare the programs and the equity each one reaches.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
Lendmire, NMLS# 2371349, is a mortgage brokerage with consumer lending licenses in 16 states. FHA, VA, conventional and jumbo purchase and refinance loans are arranged through wholesale lending partners, and each application is reviewed individually by the lender. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. VA.gov, Cash-out refinance loan
2. VA Home Loans, Purchase & Cash-Out Refinance
3. Federal Register, Revisions to VA-Guaranteed or Insured Cash-Out Home Refinance Loans
4. VA Pamphlet 26-7, Chapter 6, Refinancing Loans
5. VA News, You could be losing thousands of dollars on your home loan
6. VA Pamphlet 26-7, Chapter 4, Credit Underwriting
This article is part of Lendmire’s VA cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How to Get the Most Cash From a VA Cash-Out After Payoff and Costs · How to Plan and Use a VA Cash-Out Refinance to Go Fixed · How to Use VA Cash-Out on a Triplex With No Prior Cash-Out
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.