
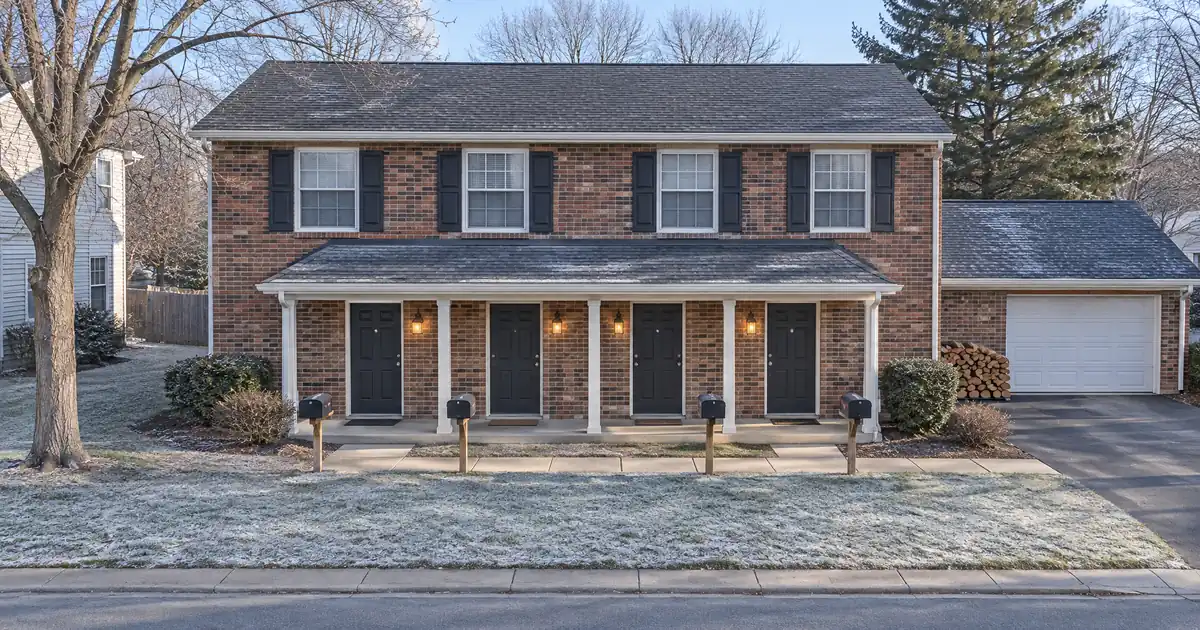
The Quick Read: For an eligible veteran living in one unit of a four-unit building, VA can reach far more of your equity. It allows a loan up to 100% of the appraised value, includes no mortgage insurance, and has no loan limit with full entitlement. Conventional makes sense when you have no VA eligibility, want to keep entitlement untouched, or need less cash than VA’s funding fee would make worthwhile. Both programs require you to occupy a unit, so neither is a rental-property loan.
VA is built for the veteran who wants maximum equity out of a building they live in. Conventional is built for the borrower who has plenty of equity, no VA benefit, or a reason to protect that benefit for a later purchase. On a fourplex, the leverage gap between the two is the single biggest practical difference, though the other details still deserve a careful read.
VA cash-out estimate
Seeded with an example value, a typical balance, and a round cash request at the first-use fee; change any field.
Editable benchmark: 7.18% as of November 5, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not a VA cash-out refinance quote.
Illustrative starting assumptions: a $350,000 home value, a $193,000 current balance, the full-value VA cap with the first-use funding fee financed, a thirty-year term at the current Freddie Mac benchmark, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conventional benchmark, a market reference and not a VA cash-out refinance quote; a VA loan is priced by the lender at lock. The total loan, funding fee included, is capped at the program leverage on the reasonable value; the fee follows the tier chosen. The cash available is what the cap allows less the balances paid off and the fee, before closing costs, which are not included. The HELOC line is the line program’s combined loan-to-value ceiling applied to the same value and balance. Taxes and insurance are editable estimates. The debt-to-income figure is a guideline; residual income decides a VA file. Licensed in sixteen states for consumer mortgages.
Side-by-Side
Start with the table, then the reasoning behind each row.
| Factor | VA Cash-Out | Conventional Cash-Out |
|---|---|---|
| Maximum loan vs. value | Up to 100% of appraised value, fee included | Noticeably lower on 2–4 units |
| Mortgage insurance | None | Usually not a factor at lower leverage |
| Upfront government fee | Funding fee, financeable, waived if exempt | None |
| Credit floor | VA sets none; wholesale programs start at 580 | Typically higher than VA’s wholesale floor |
| Rent from other units | Counted at 75% for qualifying | Treated under conventional rules |
| Main income test | Residual income, with a 41% guideline | Debt-to-income ratio |
| Who qualifies | Veterans and others with entitlement | Any qualified borrower |
| Loan limit | None with full entitlement | Conforming limits apply |
Every figure above is subject to lender guidelines and full file review, and nothing here is a commitment to lend.
What a Cash-Out Refinance Does on a Fourplex
A cash-out refinance replaces your current mortgage with a new, larger one. You keep the difference between the new loan and your payoff, minus closing costs. The CFPB draws the contrast with home equity loans and HELOCs, which leave your original first mortgage in place. A cash-out removes it.
That matters on a fourplex because the loan covers a bigger, more complex asset. The appraiser values four units, and the lender looks at how the building performs. You also take on a bigger balance against a property that supports four households. Run the whole budget, not just the cash you want at closing.
Leverage: The 25-Point Gap
VA’s cash-out reaches 100% of the appraised value, and that ceiling includes the financed funding fee. Conventional cash-out sits well below that on a one-unit home. On a 2–4 unit building, Fannie Mae’s eligibility matrix sets lower maximums still. That means a large slice of your equity has to stay in the building.
Picture two owners of identical fourplexes with identical balances. The veteran can pull out most or all of the equity through VA. The conventional borrower leaves a big cushion behind. If your goal is to fund a renovation or consolidate debt with a large sum, that gap decides the question before anything else does.
Here is the catch. VA’s 100% is a ceiling, not a promise. Some wholesale lenders set tighter limits on three- and four-unit files, and the financed funding fee eats part of the room. The fee is a percentage of the loan, so it shrinks the cash you actually receive.
What the VA Funding Fee Really Does
The funding fee on a VA cash-out is 2.15% for first use and 3.3% for subsequent use. Veterans who receive compensation for a service-connected disability, and the other exempt groups, do not pay it. You can finance it into the loan.
Two consequences follow. First, financing the fee raises your loan balance. Second, because the 100% cap includes the fee, your net cash drops by roughly the fee amount. A veteran with an exemption keeps all of that room.
Conventional has no funding fee. It also has no VA-style insurance waiver to talk about, because at the lower leverage conventional allows, private mortgage insurance usually does not come into play. So the trade is a one-time fee on the VA side against a large equity cushion on the conventional side.
How Rental Income Gets Counted
You live in one unit. The other three can produce rent. How that rent helps you qualify is a real difference between programs.
VA’s underwriting handbook counts 75% of the lease or rental amount when it is used for qualifying. The handbook also ties reserves to using rental income. That document is older, so check the live version.
The practical takeaway is simple. Do not budget as if every rent dollar counts. Make sure the full payment is supportable if a unit sits empty for a stretch.
Conventional underwriting treats rental income under its own rules, and a lender will explain which documentation it wants. Expect more paper on a multi-unit building than on a single-family home.
When VA Is the Better Fit
VA is the stronger choice in these situations:
- You want the most equity out. The 100% ceiling reaches where conventional cannot.
- Your credit has a few dents. VA sets no minimum score itself. The wholesale programs Lendmire places VA loans with start at a 580 decision score, though each lender sets its own floor.
- Your income is solid but your debt ratio is high. VA’s controlling test is residual income, the cash left each month after taxes, housing and debts. The 41% debt-to-income figure is a guideline, not a cap. A ratio above it needs residual income well above the table.
- You want to avoid mortgage insurance entirely. VA carries none on any of its loans.
- You are refinancing a non-VA loan into VA. This is the route the VA cash-out refinance exists to serve, and it accepts a conventional loan as the one being paid off.
Lendmire’s VA cash-out refinance program page lays out the program’s basics if you want the mechanics in one place.
VA’s cash-out also comes with tests that surprise people. It requires a net tangible benefit, meaning the loan must satisfy at least one of VA’s listed benefits, such as eliminating mortgage insurance, shortening the term, or moving from an adjustable to a fixed loan. The loan must also meet seasoning, and the lender must hand you a comparison of old and new terms. VA’s lender training deck spells these out. The half-percent rate-reduction and fee-recoupment tests belong to the IRRRL, VA’s streamline, and do not apply to the cash-out.
One more wrinkle: the cash-out is not a streamline. The VA’s refinancing chapter separates cash-out loans from the IRRRL because the rules differ. A cash-out requires an appraisal and full underwriting. An IRRRL does not.
When Conventional Is the Better Fit
Conventional wins in these cases:
- You have no VA entitlement. The comparison ends there. Conventional is open to any qualified borrower.
- You have a lot of equity and need only a modest amount. If you want a moderate cash-out and have deep equity, the leverage limit never bites. You also skip the funding fee.
- You want to leave VA entitlement alone. A veteran planning to buy another home with VA may prefer to keep that benefit for the purchase.
- You are a veteran who owes the fee and the numbers are close. If the funding fee would take a large bite from a small cash-out, conventional can keep more of the money.
The cost of conventional is mostly equity left behind. Another cost is documentation, which on a multi-unit building can be heavier than you expect. Treat both costs as typical, not fixed, because each lender sets its own requirements.
A Worked Comparison
Say you live in one unit of a fourplex that appraises well above your current loan balance. You are a first-time VA user with no exemption. You want cash for a roof, a unit renovation and paying off a car loan.
Under VA, the new loan can reach 100% of the appraised value. The 2.15% funding fee gets financed inside that cap, so the fee reduces your cash instead of arriving as an out-of-pocket cost. The lender checks residual income, counts 75% of the other units’ rent, and confirms the net tangible benefit.
Under conventional, the loan stops far short of full value. If your balance is already low, you may still reach your target. If your balance is high, the cap may block the cash you need. You skip the funding fee but leave a cushion of equity in the building.
Now change one fact: you receive disability compensation and the funding fee is waived. VA’s advantage widens. Change another: you plan to buy a second home with VA next year. Now the entitlement question may point you toward conventional. Same building, different answers. That is why this decision has to be run on your numbers, not a rule of thumb.
Entitlement, Moving Out, and the Next Purchase
Entitlement is the portion of your VA benefit that backs your loan. Full entitlement means no VA loan limit. If you use it on a cash-out, that entitlement stays tied to the loan until you repay it and VA restores it. That can limit what you can do with VA next. A veteran with a purchase coming up should ask a loan officer how a cash-out affects it before choosing.
Occupancy is the other piece. Both programs expect you to live in a unit when the loan closes. Whether and when you can move out later is a question to settle with your loan officer before closing, not after. Do not assume the answer.
Program Rules vs. Lender Rules
Program rules and lender rules are two different layers, and it helps to keep them apart. VA’s rules are public: the 100% cap, the funding fee, the net tangible benefit, residual income, owner occupancy. A lender’s rules are its own add-ons: a higher credit score on a fourplex, more months of reserves, tighter leverage on three- and four-unit files. In files Lendmire arranges through wholesale lenders, the same fourplex can look different from one lender to another because of those overlays. A broker’s value on a file like this is mostly in matching your profile to the lender whose overlays fit it.
The Verdict
VA is the better tool when you are eligible, want the most equity out, and are comfortable with a financed funding fee (or are exempt). Conventional is the better tool when you lack eligibility, need modest cash from a lot of equity, or want to preserve entitlement for another purchase.
Both options replace your current mortgage with a larger one. The CFPB notes that a cash-out can lengthen your payoff time and raise your monthly payment. Using the cash to pay off credit cards turns unsecured debt into debt secured by your home. That is a real trade, so make it deliberately.
If you are weighing a cash-out refinance against keeping the loan you have, Lendmire can help you compare the programs and the equity each one reaches. Call 828-256-2183 or request a quote through Lendmire’s mortgage quote page.
Key Terms Defined
Cash-out refinance: A new, larger mortgage that pays off your current loan and gives you the difference in cash.
Entitlement: The part of your VA benefit that backs your loan and sets how much the VA will guarantee.
Funding fee: A one-time VA charge, based on a percentage of the loan, that you can finance and that exempt veterans do not pay.
Residual income: The money left each month after taxes, housing costs and debts, which VA uses as its controlling test.
Seasoning: The waiting period between your existing loan’s first payments and the date you can refinance it.
Net tangible benefit: A VA test requiring the new loan to deliver at least one concrete advantage from a defined list.
Owner occupancy: Living in one of the units as your home, rather than renting all of them out.
Frequently Asked Questions
Can I use a VA cash-out on a fourplex if I don’t live there?
No. VA requires you to occupy one unit as your residence. If you live elsewhere and rent all four units, VA does not apply. Conventional owner-occupied rules also assume you live in the building, so a fully rented fourplex falls into a different loan category.
Does VA count all the rent from the other three units?
No. VA’s underwriting handbook counts 75% of the rent when it is used to qualify. Lenders may also ask for reserves when rental income is part of the approval. Because the handbook is older, confirm the current rules with your loan officer before relying on them.
How much cash will I actually receive on a VA cash-out?
Less than the full 100% in most cases. The funding fee, 2.15% for first use or 3.3% for later use, can be financed, but it counts inside the cap. That reduces your cash dollar for dollar. Veterans exempt from the fee keep all of that room, subject to lender guidelines.
Can I refinance a conventional loan into a VA loan?
Yes, through the VA cash-out refinance. It refinances any loan type into VA, and it comes with the same net tangible benefit and seasoning tests as other VA cash-outs. It requires an appraisal and full underwriting, unlike the IRRRL streamline.
Does a VA cash-out use up my entitlement?
It can tie up entitlement until the loan is repaid and the benefit is restored. That is why veterans planning another VA purchase should talk to a loan officer first. Conventional leaves entitlement untouched.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage serving homeowners and home buyers in 16 states. FHA, VA, conventional and jumbo purchase and refinance loans are arranged through wholesale lending channels; Lendmire brokers the financing and the lender underwrites each application. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. CFPB Office of Research blog on cash-out refinances
2. Fannie Mae Eligibility Matrix
3. VA Handbook, Chapter 4: Credit Underwriting
5. VA Pamphlet 26-7, Chapter 6: Refinancing Loans
6. CFPB guide to using home equity
This article is part of Lendmire’s VA cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How Much Cash Comes Out of a VA Cash-Out Refinance to Go Fixed? · VA Cash-Out Refinance vs Conventional Cash-Out for Military Borrowers · VA Cash-Out Refinance Rules After a Title Change
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.