
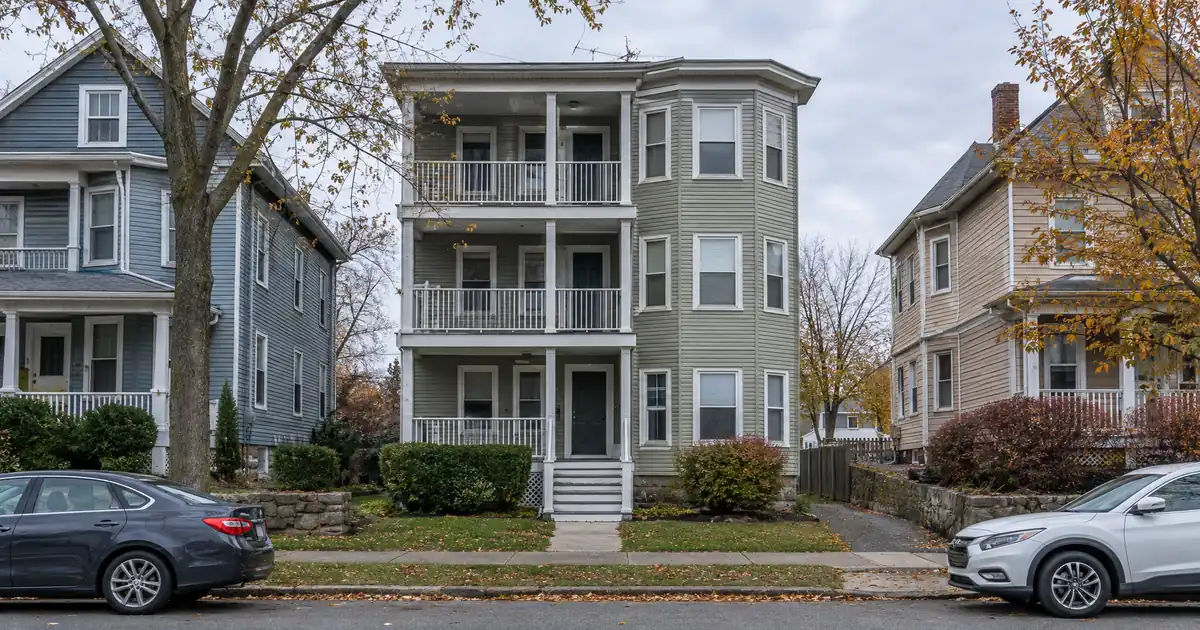
Can a Chicopee rental bought a few years ago support a meaningful cash-out refinance today? Often yes, but the equity comes from disciplined purchase pricing and a steady local price climb, not from a boom. Redfin puts the citywide median sale price at $324,885, up 4.8 percent year over year. Chicopee rewards investors who underwrite on today’s appraised value and treat any further gain as a bonus.
Lendmire, NMLS# 2371349, is a DSCR-focused mortgage broker. Chicopee, Massachusetts is one of the 41 markets — 40 states plus Washington, D.C. — where Lendmire places DSCR loans for investment-property borrowers. This report covers the equity-extraction side: where the coverage math holds after purchase, what seasoning and appraisal variance do to proceeds, and when the answer flips to “hold, don’t pull.”
DSCR Cash-Out Calculator
Run the cash-out numbers in Chicopee, MA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read: A DSCR cash-out refinance in Chicopee, Massachusetts is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the file turns on appraised value, seasoning, reserves, and a coverage ratio that clears the lender’s baseline.
- Citywide average rent runs about $1,700, with three-bedrooms near $1,850, per Zillow Rental Manager.
- Modeled duplexes cover roughly 1.25-1.35x including taxes and insurance; modeled single-families land below 1.00x.
- Westover Air Reserve Base anchors demand with more than 3,000 jobs.
- Cash-out is capped at 75 percent LTV, after about six months of ownership.
Chicopee Market Snapshot
A quick read on the Chicopee investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| University enrollment | 1,268 total (Wikipedia) |
| Population | 55,717 population (Western Mass EDC) |
| Employment | 3,000+ jobs (Rep. Neal) |
Chicopee Is a Cash-Flow Market (Don’t Underwrite a Boom)
Chicopee’s price signals are mixed, and that should shape how much equity an investor plans to pull. Redfin’s citywide median of $324,885 is up 4.8 percent, and Zillow’s home value index shows 3.8 percent annual growth on a $312,658 average value. That is a methodology difference, not a contradiction. An earlier Redfin snapshot showed a median near $301K with only 29 closed sales in the month, down from 43 a year before.
Neighborhood medians diverge too. Redfin shows Chicopee Center at $308K, up 2.5 percent, while Fairview sits at $295K, down 1.5 percent, and Chicopee Falls at $327,890, down 1.5 percent. The figures come from different months and cover all home types, so treat them as direction, not precision.
The read: modest appreciation with thin sales volume. A cash-out here should be sized on the value an appraiser can support today. Anything you’d have to forecast isn’t proceeds; it’s hope.
The Westover Factor
Westover Air Reserve Base is the structural reason rental demand here doesn’t swing like a cyclical market. According to Rep. Richard Neal’s office, the base is Chicopee’s largest employer, with more than 3,000 jobs, and the release highlighted a completed $32 million runway rebuild. The city notes that Westover shares the longest runway in Massachusetts with the adjoining metropolitan airport (City of Chicopee).
The surrounding airparks add a second layer. The UMass Donahue Institute reports that airpark businesses employ over 3,600 people across more than 100 establishments, and 58 percent of those workers come from Hampden County. That is a local workforce drawing paychecks from a federal, military-linked anchor.
The broader base is healthy but flat. Data USA counts 26.1k employed residents, led by health care and social assistance (5,546), manufacturing (2,918), and retail (2,875). Employment slipped 1.99 percent in the latest year. No major acute-care hospital sits inside city limits, but healthcare workers commute to Springfield and Holyoke, and Elms College adds a small pocket of student and nursing-related demand at roughly 1,200-1,300 students.
Steady, not spectacular. For a refinance, steady is fine. Lenders care that rent is durable, and this employer mix supports long-term leases better than it supports rent spikes.
Where the Coverage Math Holds
The historic mill neighborhoods offer the best fit for DSCR cash-out files, because older 2-4 unit buildings stack income against a price that is close to the citywide median. Point2Homes reports that 34 percent of Chicopee’s rental units, 3,356 of them, were built in 1939 or earlier, and two-bedrooms make up the largest share of rentals at 39 percent. Lendmire Research identified submarkets using three filters: small-multifamily stock, available sales data, and a nearby employment anchor.
Chicopee Center and Chicopee Falls. Both developed as industrial communities along the Chicopee River, per the city. Chicopee Falls is the most data-rich: Homes.com showed three multi-family listings from $287,500 to $472,900. That spread is itself a signal. Condition and unit count vary widely, so two “duplexes” can appraise very differently. Chicopee Center’s 2.5 percent gain on a $308K median is the firmest neighborhood-level trend in the data.
Willimansett. It is the most-cited investor submarket in local agent commentary, with a mix of single-family and multi-family stock near the Connecticut River. No reliable price or rent series exists, so this one stays qualitative. Investors who already own here should lean on a recent appraisal, not neighborhood headlines.
Fairview and Aldenville. Fairview, the northernmost village, developed residentially after Westover grew, and it suits single-family workforce rentals. Its three-month median of $295K, down 1.5 percent, is the softest number in the set. Aldenville’s listing-portal data also points to modest softening. Both are holds more than pulls, unless the property carries a rent premium.
Duplex or Single-Family? Run the Numbers
A duplex in Chicopee carries materially more coverage than a single-family rental at comparable prices, and that gap decides which properties produce proceeds. The figures below are modeled assumptions, not sourced market data. They use citywide benchmarks for price and rent, 75 percent LTV, and full taxes and insurance at Massachusetts-average levels.
| Factor | Single-Family | Duplex |
|---|---|---|
| Modeled value | About $325K (Redfin median) | About $377K (Redfin multi-family median) |
| Modeled rent | $1,700-$1,850 | $3,000-$3,300 combined |
| Coverage, full PITIA | Roughly 0.85-0.90x | Roughly 1.25-1.35x |
| Cash-out LTV ceiling | 75 percent | 75 percent |
Zillow’s average rent of $1,700 against its $312,658 average value implies a gross monthly rent-to-value near 0.54 percent. Two units at about $1,650 each against the multi-family median works out to roughly 0.88 percent. That is my arithmetic, not a sourced figure. The duplex takes about double the rent for about 20 percent more price. The multi-family median comes from an undated Redfin listing snapshot, so check it against current comps.
The single-family result sits under the standard 1.00x benchmark. Many programs are built around that baseline because rent covers the payment at that level. Below it, options a lender might review include a sub-1.00 program, an interest-only structure, or lower leverage. Each brings different pricing or cash requirements, and eligibility depends on lender guidelines, credit approval, and property review.
An honest toss-up sits in the middle. A single-family owner with heavy equity might prefer a lower-LTV cash-out that clears coverage, while a duplex owner can often take the full 75 percent. The duplex looks stronger on paper, though thin inventory (the Homes.com citywide page showed nine listings from $299,900 to $1,299,000) means fewer comps behind any appraisal.
DSCR files in markets like this one typically look the same: coverage is fine on small multifamily, tight on single-family, and the swing factor is appraisal comps, not borrower income. Brokers see the best results when the investor arrives with current leases, a recent rent survey, and reserves documented before the file goes to a lender. For a read on a specific building, talk through the file with the team before ordering an appraisal.
What Six Months of Seasoning Actually Buys
Seasoning is the gate, and it is typically about six months of ownership measured from title recording. Waiting does two things. It lets the investor show real rent collection, and it gives the market time to move. Redfin’s climb from a median near $301K in one snapshot to $324,885 in a later one suggests buyers who waited saw value gains, though the figures come from different months and aren’t seasonally adjusted.
Equity is not a guaranteed figure. It depends on the appraisal, rent used for lender review against the full monthly obligation, reserves (typically about six months of PITIA), and the 75 percent LTV ceiling. Credit tiers generally start at a 620 floor and improve at 660, 680, and 700, subject to lender guidelines. Standard programs reach up to $3,000,000, and smaller balances route through select lenders. LLC-titled properties are common, subject to lender program eligibility.
Consider an investor whose duplex appraises near the multi-family median, with an existing balance around half of value. The 75 percent ceiling leaves roughly 25 points of value as potential proceeds before costs and reserves. Change the appraisal by a few percent and that cushion shifts visibly. With monthly sales volume in the dozens, one or two comps can move the number. Budget for variance.
Proceeds also need a destination. Investors who recycle cash-out into the next acquisition should compare the new property’s coverage against the equity released, because pulling capital to fund a sub-1.00 purchase compounds thin margins. For program mechanics, see cash-out refinance details. For a broader comparison with bank products, the side-by-side comparison covers it, and Lendmire’s primer on DSCR loans explains how the ratio works.
When the Answer Flips
The case for pulling cash here holds when three things line up: a 2-4 unit building, rents documented at or near market, and an existing balance well under the LTV ceiling. It flips in a few situations:
- Rent rests on one source. Sources disagree: Zillow shows $1,700 and says rent is up only about $50 over the year, while Zumper shows $1,675 and an 8 percent gain. RentCafe reports $1,549, up 1.69 percent, but covers only buildings of 50 or more units. Underwrite on signed leases, not the flattering headline.
- The property is a soft-submarket single-family. Below 1.00x coverage, cash-out gets more expensive and proceeds shrink.
- The investor needs the cash for appreciation bets. Flat neighborhood medians make Chicopee a poor place to speculate on gains. Hold the property and keep the existing structure if nothing else needs the capital.
Also keep in mind that some programs cap residential at 1-4 units, and manufactured homes, log homes, and barndominiums fall outside these programs entirely. Verify current local rules, taxes, and insurance with qualified local professionals before committing.
Watchlist: Three Indicators for the Next Quarter
1. Monthly sales volume. Redfin’s count of 29 sales in a month is the weak point for appraisals. A rebound toward 40 or more would deepen comps.
DSCR vs. conventional financing
Two common ways to finance an investment property in Chicopee, MA. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
2. Rent direction. Zumper’s 8 percent and Zillow’s $50 gain tell different stories. Converging sources would make rent schedules easier to defend.
3. Westover and airpark activity. Employment at the base and the airparks drives the tenant pool. Any hiring shift there moves Chicopee’s rental demand more than any national headline.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Chicopee, Massachusetts?
Qualification centers on the property’s rent measured against its full monthly obligation, typically with a 1.00x baseline, about six months of ownership, a 620 credit floor, and about six months of reserves. The refinance is capped at 75 percent LTV. Final eligibility depends on lender guidelines, credit approval, and property review.
What are the requirements for an investment property refinance in Chicopee, Massachusetts?
Expect a current appraisal, a lease or rent survey, proof of reserves, and documentation of the ownership entity. Properties are generally 1-4 units. Manufactured homes, log homes, and barndominiums are outside these programs. Details vary by lender.
Do Chicopee duplexes cover better than single-family homes?
In Lendmire Research’s modeled math, yes. Duplexes land around 1.25-1.35x including taxes and insurance, while single-families land below 1.00x at the same leverage. The gap comes from collecting two rents against a price only about 20 percent higher. Your own building’s rents and appraisal will change the result.
Can a self-employed investor buying in Chicopee be reviewed for DSCR financing?
Yes, reviewed on rental income rather than W-2 history. Lendmire arranges DSCR investor loans and qualification centers on the property’s rental income. Approval remains subject to lender guidelines.
Does the Westover Air Reserve Base affect refinance value?
It affects demand more than price. More than 3,000 base jobs and 3,600-plus airpark jobs support steady tenant demand, but appraisals rely on recent comparable sales. Strong demand helps the rent schedule; it doesn’t replace comps.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income, not the borrower’s W-2 history, which is a practical fit for LLC-titled portfolios and self-employed investors. All scenarios remain subject to lender review and program guidelines. Recognized as a 2026 Scotsman Guide Top Workplace and a top-ranked workplace in 2025, with Lendmire’s industry announcements published on EIN Presswire. Investors can also review DSCR loan options for Massachusetts investors or call 828-256-2183.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin
3. Wikipedia
9. Data USA
10. Point2Homes
11. Homes.com
12. Zumper
13. RentCafe
14. a 2026 Scotsman Guide Top Workplace
15. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Chicopee, MA · Investment Property Cash-Out Refinance in Massachusetts
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.