
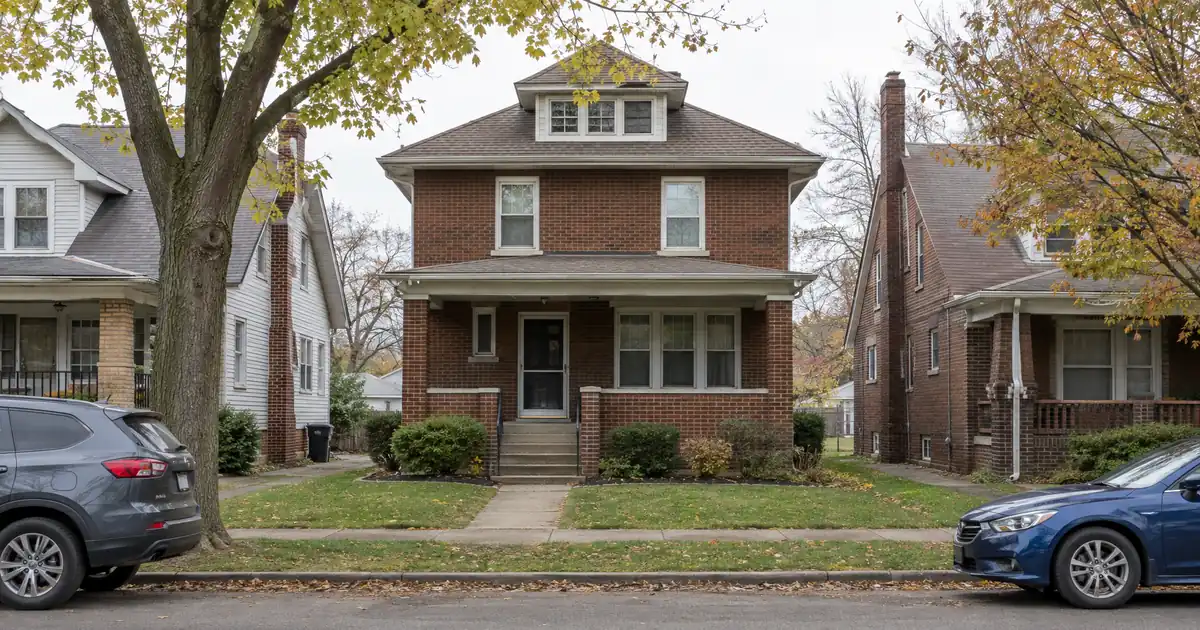
Does a city where the average home is valued near $153,063 have enough equity to refinance out of? Yes, but the equity sits in a specific place. Per Zillow, Lima’s average home value is up 6.4% over the past year. The cash-out math works best on older duplexes and small multi-unit buildings, where several rent streams sit under one appraisal. A single cheap house with one rent mostly doesn’t get there.
DSCR Cash-Out Calculator
Run the cash-out numbers in Lima, OH
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A cash-out refinance on an investment property in Lima, Ohio is underwritten primarily on the property’s rental income measured against its full monthly obligation, and the lender’s 75% LTV ceiling then decides how much equity can come out. In this market, unit count matters more than price. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
- Single-family detached homes are 71.43% of Lima’s housing units, per NeighborhoodScout.
- Renters occupy 56.86% of housing, a deep tenant pool for small buildings.
- Cash-out LTV tops out at 75%, with about six months of seasoning from title recording.
- Valuation sources disagree by roughly 20%, so size the refinance conservatively.
- Lima is a defense, refinery and data-center employment story, not a student-rental one.
Lendmire helps arrange DSCR financing for Lima, Ohio investors through wholesale and investor-lending channels across 41 markets, including Washington, D.C. Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker, so it places the file with a lender rather than lending itself. This article skips purchase mechanics entirely. The reader already owns the asset, and the question is how much capital can be pulled out of it and where it goes next.
Lima Market Snapshot
A quick read on the Lima investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $1,295 average (Zillow Rental Manager) |
| Recent appreciation | +6.4% (Zillow Home Values) |
| University enrollment | 723 total (Data USA, OSU Lima) |
| Employment | 50 full-time jobs (LimaOhio.com) |
What Does Lima’s Equity Actually Look Like?
Lima’s equity is modest per property and concentrated in older stock. The city of 35,010 people, per Census Reporter’s ACS five-year profile, has a median household income of $46,240, against $71,389 statewide. Prices stay low as a result. Rents can’t climb far on that income base, which is why the rent-to-value ratio matters more than appreciation here.
Appreciation is real but not the thesis. The 6.4% annual gain on Zillow’s $153,063 average gives a refinance some lift. This article treats Zillow’s figure as the canonical citywide value. Other sources run lower. NeighborhoodScout puts the median house at $125,948. An Ark7 article cites a typical home near $121,700. The gap is about 20%, and it matters because cash-out proceeds are a function of the appraisal, not the asking price.
Here’s the catch: an appraiser may land anywhere in that band. Plan for the low end.
Why Duplexes and Fourplexes Win the Cash-Out Math
Small multi-unit buildings win because the second and third door cost little extra. Redfin’s multi-family snapshot shows eight listings at a $148K median list price, versus NeighborhoodScout’s $125,948 median house. That gap is a couple of tens of thousands of dollars for added rent streams. The sample is small and the listings sit on the market a long time (Redfin cites 125 days for most Lima homes), so treat the figures as a snapshot.
NeighborhoodScout also reports that duplexes, converted homes and small apartment buildings make up about 11.41% of units. That cuts two ways. Scarcity supports the multi-unit thesis, but thin inventory means comps on a given block can be hard to find, and appraisers lean on what they can find.
Run the numbers on a modeled duplex. Assume an appraised value near the $148K median list price, two units, and rents inside the $700–$950 two-bedroom band that local brokerage LV5 Real Estate Team at Hartsock Realty cites. (That’s a broker’s marketing claim, so it’s directional.) At a 75% LTV with taxes and insurance in the payment, coverage lands at roughly 1.4 or better. It rises toward the upper end if both units rent near the top of the band. Those are modeled inputs, not a quoted deal. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Now the single-family comparison. Take a two-bedroom house at the $125,948 median value and the $950–$1,050 range Rentometer shows for two-bedroom houses. That works out to roughly 0.75%–0.83% of value per month. At 75% LTV, including taxes and insurance, modeled coverage sits in the low 1.1s. That is thin. The 1.00x benchmark is common because the rent covers the payment at that level, but a low-1.1 file has little room for a soft appraisal or a vacancy. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
The multi-unit case is clearly stronger. Single-family still works for investors with modest leverage targets, though.
How the Proceeds Actually Get Sized
Cash-out proceeds come out of three constraints, and the tightest one wins. The first is the 75% LTV ceiling on the appraised value. The second is the debt coverage ratio, where rent used for lender review is measured against the full payment including taxes and insurance, with 1.00 the minimum on the programs Lendmire works with. The third is reserves, typically about six months of the full payment, and the borrower must also have held title about six months, measured from recording. Credit tiers run from a 620 floor up through 660, 680 and 700, and the tier affects leverage and pricing.
Loan size is its own issue in Lima. Standard programs go up to $3,000,000, but smaller balances route through select lenders in the network. Lima’s low values make small balances common, so lender selection matters more here than in a high-priced metro. The guide “What Is a DSCR Loan” covers the mechanics, and the cash-out refinance details page walks through proceeds in more depth.
Seasoning rewards a particular strategy. An investor who buys a distressed older duplex, renovates it and gets it leased can refinance after about six months of ownership. The new appraisal reflects the improved condition and the in-place rent, so the proceeds can exceed what was spent on the work. That only holds if the leases are signed and the appraisal supports the number. Equity available is never a guaranteed cash figure, and everything is subject to lender guidelines and property review.
Where the Refinances Pencil: Four Lima Submarkets
No source provides reliable neighborhood-level rents, so this section sticks to character, price range and investor fit. Redfin names Northside Lima, Lakewood West, Riverside North, Northwest Perry Township and Southside Lima as popular areas.
Southside Lima. The housing is early-to-mid-1900s stock, and Homes.com puts its price range at $15,000 to $112,000. Cheap entry points make this the classic rehab-then-refinance zone. The risk sits at the bottom of that range. A $15,000 house will not support a meaningful cash-out. Appraisal, condition and the lender’s loan-size minimum can all cut against the more affordable properties. Buildings near the upper end of the range carry the more realistic refinance potential.
Riverside North. Early-20th-century homes near Faurot Park, close to downtown dining. This is the most likely place to find older two-to-four unit conversions, though no unit-level data exists in the research. Walk the blocks and pull county records before assuming anything.
Central Lima. A residential grid of bungalows and cottages within a mile of downtown, and one listing in the research describes a property as near the hospital and new downtown developments. Workforce renters tied to healthcare and industrial jobs are the natural tenant base.
Northside Lima. Wide streets, ranch-style homes, close to retail along the corridor. It reads as a single-family market, so refinance coverage tracks the lower-leverage single-family math above rather than the multi-unit math.
Honestly, Riverside North versus Southside is a toss-up for a rehab investor. Southside has the cheaper entry and more upside. Riverside North likely has the better unit mix for coverage. Which one pencils depends on the building, not the neighborhood label.
Larger assets exist too. Redfin shows a remodeled 30-unit building and a 30-home single-family portfolio listed at $2,650,000. These probably route to commercial or multifamily programs rather than the 1–4 unit DSCR path, and the research has no rent or NOI data on either.
Who’s Paying the Rent
Lima’s tenant demand comes from industry and healthcare. It does not come from students. That is good news for lease stability.
Per the Allen Economic Development Group, the main clusters are petrochemicals and energy, food processing, plastics manufacturing and biohealth. The metro had 100,866 residents, per Census Reporter’s metro profile. Several anchors stand out.
The Cenovus Lima refinery is marking 140 years of continuous operation, the oldest continuously operating refinery in the country. The plant’s general manager cited about 900 direct employees. That is a company statement. Turnaround projects also bring contract labor into town, a source of short-term workforce housing demand.
The Lima Army Tank Plant, which Wikipedia describes as the sole producer of the M1 Abrams tank, employed 856 civilians plus about 80 Army personnel in the most recent local reporting. Employment had dipped near 400 before rebounding. That swing is the lesson. Headcount follows federal contracts, so no lender or investor should treat it as a fixed base.
Healthcare rounds it out. Lima Memorial Health System reports about 1,600 associates and more than 25 facilities. Mercy Health St. Rita’s was the largest county employer in an older LimaOhio.com ranking, at 3,000.
Then there’s the Google data center, a $500 million project with $50 million earmarked for local infrastructure, per LimaOhio.com. It is expected to create only 50 full-time jobs. The rental case is construction-phase contractors, not permanent residents, and the project is contested locally. Treat it as a possible tailwind, never a guarantee.
Higher education is small. Ohio State Lima had 723 students, per Data USA, and the University of Northwestern Ohio enrolls roughly 2,600. A student-rental refinance thesis would be weak here. A workforce one is stronger.
What Working Brokers See in Markets Like This
Working DSCR brokers see a recurring pattern in small industrial Midwest markets: the rent supports the loan, but the appraisal limits the cash-out. Files often clear the coverage test comfortably and then lose proceeds to a conservative value or a small-balance minimum. The stronger files arrive with signed leases, documented rehab scope and a realistic view of the lowest plausible appraisal. Unlike balance-sheet lenders that treat investor files as portfolio-risk exercises, a broker can place the same file across several wholesale channels and match balance size to the lender that wants it.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Lima, OH, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Borrowers holding title in an LLC are common in these files. That route is generally available, subject to lender program eligibility.
Cheap Doesn’t Mean Refinanceable
Skip the sub-$30,000 shells for cash-out purposes. For anything in that range, the realistic play is to buy, renovate and hold, or to bundle properties into a larger financing structure.
Rent-data quality is the other trap. Zillow Rental Manager shows an average near $1,295 across all property types. Rentometer’s house bands run far lower, and older apartment-site figures run lower still. Those sources measure different things. For any refinance, anchor on the actual leases and a lender appraisal’s rent schedule, not a citywide average.
A cash-out refinance also changes the carrying cost of the property it’s drawn from. Borrowers on investor properties who might otherwise take the conventional route should compare conventional and DSCR loans, and see the investment property refinance options for the full menu. Verify current local rental rules, taxes and insurance with qualified local professionals.
Where the Proceeds Go
Cash-out dollars are most useful when they fund the next duplex’s down payment or renovation. Lima’s low entry prices mean one refinance can seed more than one acquisition. The state hub for Lendmire’s Ohio DSCR loan programs outlines the next-step financing. To model a specific property, see what the numbers look like or call 828-256-2183. Review details are subject to lender overlays.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Lima, Ohio?
Qualification centers on the property’s rent versus its full payment, with 1.00 the standard minimum on the programs Lendmire works with. Lenders also review credit (620 is the floor), about six months of reserves and roughly six months of seasoning. The 75% LTV ceiling then sets the maximum loan. Approval depends on borrower, property and lender guidelines. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
What are the requirements for an investment property loan in Lima, Ohio?
Expect a property-level rent review, an appraisal, a credit tier from 620 upward and reserve funds. Standard programs go up to $3,000,000, and smaller Lima-sized balances route through select lenders in the network. Manufactured homes, log homes and barndominiums fall outside these programs. Final terms are set by the lender.
Why do Lima’s duplexes refinance better than its single-family homes?
Because added units add rent without adding much value. Redfin’s $148K median multi-family list price sits near NeighborhoodScout’s $125,948 median house, so a second rent stream is cheap to buy. Single-family coverage modeled at 75% LTV sits in the low 1.1s with taxes and insurance, while a modeled duplex clears 1.4. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Does the tank plant’s headcount swing affect Lima refinances?
Not directly, but it matters for demand. The plant employed 856 civilians in recent reporting after a dip near 400, so a lender may view workforce-housing demand as steady but not guaranteed. The refinery, healthcare systems and food processors diversify the base. The appraisal and in-place leases drive the loan, not the employer.
Can Lendmire help investors explore DSCR financing for properties outside Ohio?
Yes. Lendmire (NMLS# 2371349) is a non-QM DSCR mortgage broker that arranges investor loans through wholesale lending channels across 41 markets in multiple states, so investors can explore financing beyond Ohio. Qualification centers on the property’s rental income, subject to lender program guidelines.
What to Watch Next Quarter
- Appraisal behavior on small multi-unit comps. If appraisers keep landing near the $125,948–$153,063 value band, size refinances to the low end.
- Data center construction progress. Watch for contractor housing demand and local pushback, per Signal Ohio reporting.
- Tank plant and refinery headcount. A federal contract change at the plant or a new refinery turnaround schedule is the fastest signal for workforce rental demand.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income rather than personal income, subject to lender and program guidelines, making it a fit for self-employed investors and LLC-owned portfolios. Lendmire was recognized as a Top Mortgage Workplace by Scotsman Guide in 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. NeighborhoodScout, Lima real estate
4. Data USA
5. LimaOhio.com
6. Census Reporter, Lima metro profile
7. Redfin, Lima multi-family listings
8. LV5 Real Estate Team at Hartsock Realty
9. Rentometer
10. Homes.com
11. Allen Economic Development Group, Top Industries
12. Lima Memorial Health System
13. Signal Ohio
14. a 2025 Scotsman Guide Top Workplace
15. a 2026 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Lima Ohio · Cash Out Refinance Investment Property in Wooster, Ohio: Hospital Corridor Duplex Equity · DSCR Cash Out Refinance in Strongsville, Ohio: How the Cash-Out Math Clears in Strongsville
Guides: Investment Property Cash-Out Refinance in Lima, OH · Investment Property Cash-Out Refinance in Ohio
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.