
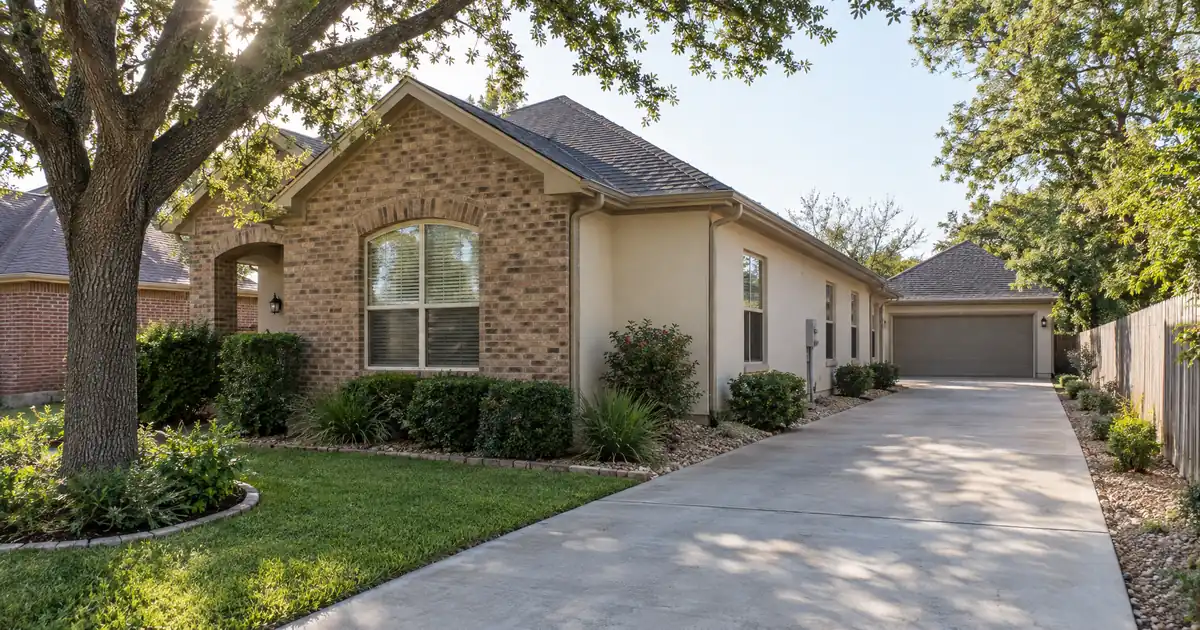
Most Odessa investors treat a cash-out refinance as a bet on oil. It isn’t. It’s a bet on an appraisal and a lease, and the oil price only matters to the extent it moves those two things.
Investors underwriting deals in Odessa, Texas can use DSCR programs Lendmire arranges — available across 41 markets, including D.C. Lendmire is a DSCR-focused mortgage broker (NMLS# 2371349), and the Odessa files that go smoothly are sized to what a cautious appraiser would say, not to what a boom-year comp would.
DSCR Cash-Out Calculator
Run the cash-out numbers in Odessa, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version: A DSCR cash-out refinance in Odessa, Texas is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the lease and the appraisal carry the file, and an oil-cycle market rewards investors who size the cash-out to a conservative value instead of a hot comp.
- Zillow puts the average Odessa home value at $253,740, up 4.9 percent year over year.
- Cash-out typically tops out at 75 percent LTV after about six months of ownership, subject to lender guidelines. RentCafe shows three-bedroom apartments averaging $1,775, a useful yardstick for house rents.
- Rent trackers disagree on direction, so underwrite on in-place leases.
- Rig activity moves this market more than household income does.
Odessa Market Snapshot
A quick read on the Odessa investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $218,900 home value (ZIP-Codes.com) |
| University enrollment | 5,622 students (UTPB) |
East Odessa and the University Boulevard Corridor Carry the Math
ZIP 79762 is the strongest cash-out fit in town. It covers east and north Odessa along University Boulevard, and it offers older workforce houses, a value base below the citywide average and steady tenant pull from campus and school-district jobs. Coverage clears here before it does on newer stock.
ZIP-Codes.com lists 40,253 residents, a $74,560 income figure and a $218,900 home value for the ZIP. That value sits well under the citywide average, which is exactly why the rent-to-value ratio works better here. UT Permian Basin enrolled 5,622 students this past fall, including a record 1,410 graduate students, and its STEM Academy sits inside the ZIP. The Odessa Development Corporation names Ector County ISD among the top employers, which adds a steady payroll base near the corridor.
Sherwood and Fleetwood show up on local listing pages, but no reliable neighborhood-level price or rent series exists for either. Pull comps address by address. Don’t trust a neighborhood label.
Central Odessa Around the Medical Center
The central belt near the hospitals is a solid second choice. Tenants there work at the medical campuses, and that demand doesn’t follow rig counts.
Medical Center Health System serves as the regional referral hospital for 17 surrounding counties, and the Development Corporation also lists Odessa Regional Medical Center and the Texas Tech medical and nursing schools as anchors. Odessa College sits in ZIP 79764 as well. One catch: travel-nurse demand can mean shorter lease terms, so underwrite on the lease actually in place, not on a hoped-for renewal. Crescent Park and Wilshire come up often on listing pages. Same rule applies. Comps first.
West Odessa: Read the Fine Print
West Odessa is a unincorporated area with a population of 33,340 at the last census, bordered by I-20 to the south and Texas SH 302 to the north. It’s oilfield workforce territory.
Skip it for cash-out unless the property is a conventional site-built house with clean comps. No verified price or rent series exists here, so appraisers may reach a wide radius for comparables. Manufactured homes, log homes and barndominiums fall outside the network’s DSCR programs entirely, and this part of the market has plenty of that stock. Know what you own before you call anyone.
What the Appraiser Will Actually See
Slow, modest appreciation with growing competition. That’s the picture, and the cash-out should be sized to it.
Zillow’s data shows values up modestly over the past year, and homes go pending in a little over a month. Movoto reports longer days on market than a year earlier, though its method differs from Zillow’s pending-time measure, so read the trend, not the exact gap. Together, the two sources point to slow appreciation, more inventory, and a market where most sales cluster in the middle of the price range.
Two implications. Well-priced houses still move, but overpriced listings sit, so appraisers lean toward the low end of the comps. And a rental priced well below that mid-band has fewer refinance comps, which means a wider search radius. (Honestly, it’s a toss-up whether the 4.9 percent gain or the inventory build will matter more to your particular appraiser.)
Run the Numbers (Modeled, Not Sourced)
These are modeled assumptions, not market data. Coverage below is rent divided by full PITIA, meaning principal, interest, taxes and insurance.
Assume a three-bedroom house valued near Zillow’s $253,740 average, a 75 percent LTV refinance and a modeled rent of $1,800. Coverage lands roughly at 1.0x, which is borderline. Now assume a house valued near $219,000 at the same rent, and coverage climbs into the low 1.2s. Cheaper, older workforce stock is where the number clears with room to spare. On the pricier house at a $1,600 rent, coverage drops below 1.00.
Sub-1.00 files aren’t dead, but they get harder. A lender may review a sub-1.00 program, an interest-only structure or lower leverage, subject to lender guidelines, credit approval and property review. Most standard programs are built around a 1.00x benchmark, with a credit floor around 620 and reserves near six months of PITIA on most files.
The pattern on Lendmire’s deal desk in markets like this is consistent. The cleaner files come in with a lease that matches market, reserves documented up front and a loan request sized under the ceiling instead of at it. The common friction point is an appraisal that arrives light because comps were thin, so the borrower’s planned proceeds shrink after the file is already moving. The Texas DSCR investor loans page covers state-level context, and the guide “What Is a DSCR Loan” breaks down the ratio itself. If you’re comparing structures, it helps to weigh conventional financing against a DSCR loan on investor properties.
Seasoning is straightforward: about six months of ownership, measured from title recording. Purchase the house, finish the rehab, sign the lease, then refinance. Proceeds depend on rent used for lender review, PITIA, reserves and the 75 percent ceiling. They aren’t a guaranteed figure.
What Happens When the Rigs Slow Down?
Rents and values move with drilling activity, so the refinance should survive a soft patch. The Dallas Fed reports that oil production, new wells drilled and active rigs all declined in its latest Permian Basin report, and Odessa single-family permits fell 8.4 percent between December and March. Employment still grew and unemployment ticked down. The backdrop is soft, not broken.
The labor base is bigger than the rigs. The Permian Basin Regional Planning Commission counts 72,566 workers in Ector County, with 17,565 commuting in from outside the county or state. Its projected county population is 174,473, with a median age of 34.
Rent signals are noisy. Apartment List shows rents down 4.0 percent year over year, while RentCafe shows the average apartment rent up 0.72 percent to $1,316 (its data covers larger complexes only). Don’t build a refinance thesis on either headline. Underwrite on flat market rent or the lease in hand. Renter households make up about 41 percent of Odessa, and Point2Homes shows two-bedroom units as the largest share of rentals at 32 percent. Demand favors two- and three-bedroom houses over studios.
Redeploying the Proceeds
Small multifamily is where investors want to put the cash, and it’s where Odessa is thin. Homes.com showed only three multi-family listings in Odessa at the time of its snapshot, and one east Odessa package offered eight units in four duplexes. No prices or rents were listed, so treat it as evidence of stock, not deal math. A thin comp pool means appraisers may need out-of-neighborhood comps or an income approach. Confirm appraiser and lender comfort before you contract.
The competition for those units is mostly dated. RentCafe reports institutional buildings average about 33 years old and nearly all are low-rise garden-style. That’s the benchmark a duplex or house has to beat, and it explains why well-kept small rentals hold tenants. For the mechanics of pulling equity from the property you already own, see the refi options. To run a specific Odessa property, pull a DSCR quote or call 828-256-2183.
Verify current local rental rules, property taxes and insurance with qualified local professionals before you commit.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Odessa?
Qualification centers on the property’s rent measured against its full PITIA, with a 1.00x baseline common on standard programs. Borrowers typically also need a credit score of 620 or higher, roughly six months of reserves and at least six months of ownership from title recording. Eligibility depends on lender guidelines, credit profile and property review.
DSCR vs. conventional financing
Two common ways to finance an investment property in Odessa, TX. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Odessa, Texas?
Expect a rental property with an appraisal, a lease or market-rent analysis, a credit score around the 620 floor, reserves and leverage capped at 75 percent for cash-out. LLC-titled properties are generally workable, subject to lender program eligibility. Loan amounts run up to $3,000,000 on standard programs.
Does the oil cycle change how a cash-out gets sized in Odessa?
Yes. Rents and values here have historically swung with energy activity, so the safest structure keeps coverage above 1.00x on flat rent and holds some borrowing capacity back. An investor who maxes the ceiling at a peak has no cushion if rigs fall.
Which Odessa property types fall outside DSCR programs?
Manufactured homes (single- and double-wide), log homes and barndominiums are not reviewable through the network’s DSCR programs. That matters in West Odessa and the outlying areas, where that stock is common. Site-built single-family houses and small multifamily are the eligible fits.
What down-payment ranges may DSCR lenders review for Odessa investment-property purchases?
Purchases typically start around 20 to 25 percent down, depending on credit, coverage and property type. Lendmire arranges DSCR investor loans. Qualification rests primarily on the property’s rental income, subject to lender guidelines.
What a Local Appraiser Would Tell You
A house that rents well and sits in the $200,000s is the easiest thing in Odessa to appraise and the easiest to defend. Trouble starts when a listing is priced off the last boom and sits while inventory keeps building. Buy and refinance the boring house, not the exciting one.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a non-QM mortgage broker (NMLS# 2371349), Lendmire facilitates DSCR investor loans across 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income instead of personal income documentation, subject to lender guidelines, serving LLC-structured portfolios and self-employed borrowers who don’t fit conventional boxes. Recognized as a 2025 Scotsman Guide Top Mortgage Workplace and a 2026 Scotsman Guide Top Mortgage Workplace, as covered in the Top Workplace press announcement.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Home Values – Odessa
4. UT Permian Basin enrollment release
5. Odessa Development Corporation – Major Employers
6. Medical Center Health System – Careers
7. Movoto
8. Dallas Fed Permian Basin Economic Indicators
9. Permian Basin Regional Planning Commission – Ector County
10. Apartment List
11. Point2Homes
12. Homes.com
13. RentCafe
14. a 2025 Scotsman Guide Top Mortgage Workplace
15. a 2026 Scotsman Guide Top Mortgage Workplace
16. the Top Workplace press announcement
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Odessa Texas · DSCR Cash Out Refinance in Bryan, Texas: Can Your Rent Cover a Bigger Loan After Pulling Equity? · DSCR Cash Out Refinance in Lufkin, Texas: The 2026 DSCR Financing Guide to the Timberland Rental Belt
Guides: Investment Property Cash-Out Refinance in Odessa, TX · Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.