
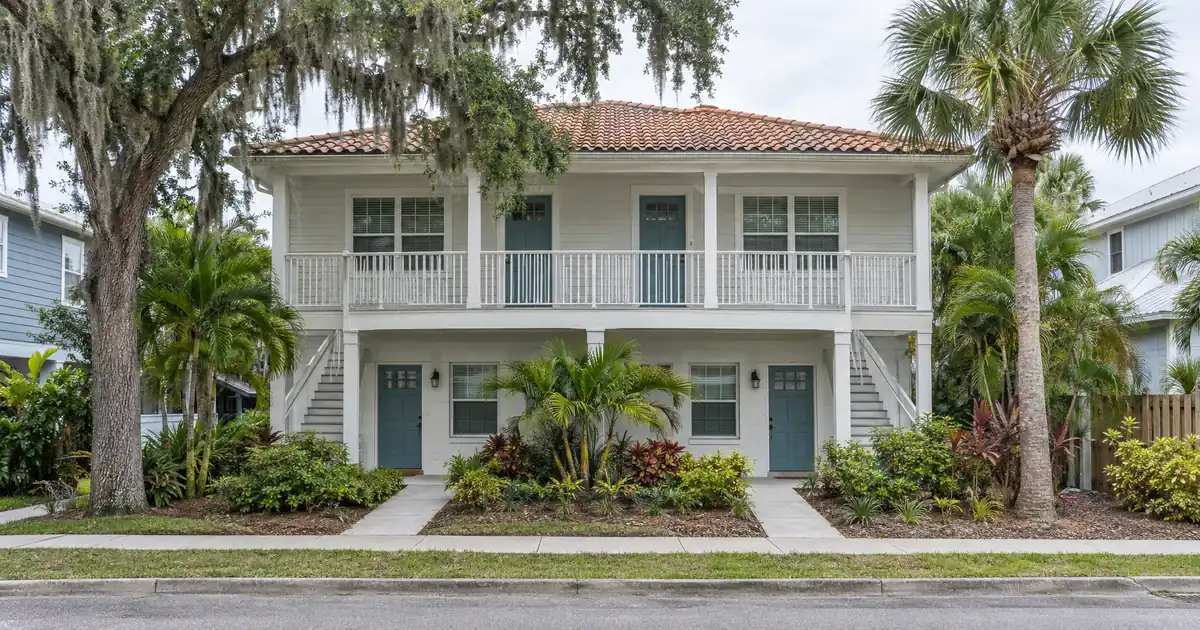
Picture two investors who both want to pull equity out of a rental. One owns a cottage in Anna Maria City, where Redfin puts the median sale price near $1.8 million, up 34.6 percent year over year. The other owns a three-bedroom house in South Bradenton, where Redfin shows a median sale price of $180,000. The cottage owner has the bigger paper gain. The South Bradenton owner has the file that clears a coverage test. On a cash-out, the second file is usually the one a lender can work with.
At a Glance: A cash-out refinance on an Anna Maria Island, Florida investment property is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the deal works from appraisal and seasoning through a coverage test before any equity is released, subject to lender guidelines.
DSCR Cash-Out Calculator
Run the cash-out numbers in Anna Maria Island, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out LTV typically tops out at 75 percent, with about six months of seasoning from title recording.
- On-island long-term rents of $2,500 to $3,000 sit against seven-figure values, so modeled coverage lands far below 1.00.
- South Bradenton’s $180,000 median sale price sets up coverage well above 1.00 on typical rents.
- Bradenton Beach shows a wide gap between median and average prices, a warning sign for appraisal support.
Anna Maria Island Market Snapshot
A quick read on the Anna Maria Island investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $1.8M median (Redfin Anna Maria Housing Market) |
| Typical rents | $2,067 median rent (Zillow zori) (Movewithmomentum) |
| University enrollment | 11,000 annual credit students (State College of Florida) |
| Population | 3,010 population (Wikipedia) |
| Employment | 550+ physicians/staff (Manatee Memorial Hospital) |
Two Cash-Out Files, One Island
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that arranges investor loans across 40 states plus Washington, D.C., and Anna Maria Island shows why cash-out files need sorting before anyone talks about proceeds. The typical parameters are simple. Most files cap cash-out at 75 percent of appraised value. Lenders generally look for about six months of ownership measured from title recording. The baseline coverage benchmark is 1.00, meaning rent used for lender review covers principal, interest, taxes, and insurance. Credit tiers run from a 620 floor up through 700, and reserves usually run about six months of the full payment, stepping up to about nine months on balances above $1.5 million. Standard programs run to $3 million. What DSCR qualification actually looks like is covered on the pillar page. All of this is subject to lender guidelines, credit review, and the appraisal.
Equity is not the same as extractable equity. Proceeds depend on the appraised value, the 75 percent ceiling, the existing payoff, reserves, and whether rent clears the coverage test. A paper gain that fails the coverage test is just a paper gain. The cash-out qualification details walk through the mechanics, and the investor-property refinance pathway covers the broader options.
What the Island Actually Rents For
On-island long-term rents run thin against values. Local reporting puts a typical two-bedroom annual rental at roughly $2,500 to $3,000 a month, and few owners offer year-long leases at all. Against a $1.8 million median, that is a gross monthly rent-to-price ratio of about 0.14 to 0.17 percent.
Model it as an assumption, not a market fact. Take a cottage valued at the Redfin median, a top-of-range $3,000 rent, and a 75 percent LTV. Coverage, including taxes and insurance, comes out well below 0.50. Rounded down, it is closer to a quarter of the obligation than to the 1.00 baseline. Movoto’s list-price median for Anna Maria runs much higher, near $2.99 million. That figure reflects asking prices rather than closed sales, so the coverage gap only widens on it.
Some lenders review sub-1.00 structures, such as lower-ratio programs, interest-only payment structures, or vacation-rental income documentation. These typically come with stronger compensating factors, lower leverage, or more cash reserves, and eligibility is not assured. The honest read is that an island cottage is an equity asset that rarely is reviewed on long-term rent alone.
The tenant pool explains why. Census-based figures show Holmes Beach at 3,010 residents with a median age of 64.7. Bradenton Beach recorded 908 residents and 70.4 percent of housing units vacant, nearly half of all units held for seasonal or occasional use. Anna Maria fell from 1,503 residents to 968 over a decade. This is a second-home economy with a thin year-round renter base, so there is little long-term rent data to lean on.
Bradenton Beach, Holmes Beach, Anna Maria: Where Appraisals Bite
Appraisal variance is the hidden cost of island cash-outs. Redfin shows Bradenton Beach with a median sale price of $722,000 but an average of $865,000, and the median fell 8.6 percent while the average rose 10.9 percent. That divergence means a handful of high-end sales are pulling the average up. An appraiser working a cash-out there has a thin, uneven comp set. Pull multiple recent closed sales before assuming any specific equity figure is extractable.
The Anna Maria numbers deserve the same skepticism. The 34.6 percent gain and the drop in days on market from 165 to 53 make a strong headline, but a small municipality with a few hundred transactions can swing on a handful of closings. Broader island estimates in the research put typical values around $2.15 million and describe a market with 14-plus months of inventory in some readings. Sources disagree, and the research flags all of these figures as aggregator-based and directional. Treat any island valuation as a range, not a point.
Property type matters too. Roughly 80 percent of Anna Maria real estate is single-family, per a local brokerage, and only about 5 percent are duplexes. Low height limits across all three municipalities, ranging from 29 to 37 feet, cap density and keep new supply scarce. That supports long-run values, but it also means an owner has no realistic path to income-stacking. A legacy duplex on the island is a rare asset. Multi-unit coverage math belongs on the mainland.
The Mainland Corridor Where the Number Clears
The mainland Bradenton corridor is where cash-out files pencil. South Bradenton’s $180,000 median sale price, down 12.2 percent over the prior year with 51 days on market, sits against 3-bed, 2-bath rentals listed between $2,050 and $2,575 a month. That is a gross rent-to-price ratio above 1.0 percent monthly, the strongest coverage in the island’s feeder market, according to Redfin listing data.
Run the numbers on a modeled South Bradenton house at $2,050 rent, a $180,000 value, and 75 percent LTV. Including taxes and insurance, coverage lands comfortably above 1.5. That clears the 1.00 baseline with room to spare. It also means a low-basis owner can pull proceeds and still hold a file that a lender may review favorably, subject to the appraisal and reserves.
Bradenton’s broader market is more mixed. Citywide, Redfin shows a median sale price of $312,743. Another aggregator puts it at $410,000, and the gap reflects different methodologies and property mixes. Manatee County’s median rent is about $2,067 per Zillow ZORI data, a gross yield near 6.1 percent. Model that rent against the $312,743 median at 75 percent LTV, and coverage lands right around 1.0 including taxes and insurance. In the $250,000 to $500,000 core, with a median near $359,000, the same rent drops coverage into the high-0.8s or low 0.9s. Bradenton is a market where the coverage number depends heavily on which side of the price band a property sits.
The renter base is a real plus. About 29 percent of Bradenton households rent, and rents have softened: RentCafe shows the average apartment at $1,788, down 5.87 percent year over year. Softening rent against flat values is a caution flag, not a footnote. Stress the modeled rent at 5 to 10 percent lower before trusting the cushion.
Demand anchors sit on the mainland, not the island. Manatee Memorial Hospital is a 319-bed facility with more than 550 physicians and allied professionals, and it is described as the county’s largest employer. State College of Florida, Manatee-Sarasota serves about 11,000 credit students annually. Per the Bureau of Labor Statistics via Randstad, the metro’s largest sectors are trade, transportation, and utilities at 64,500 jobs, followed by education and health services at 61,800. Leisure and hospitality adds 48,800, and that is the sector feeding island workers into mainland rentals. Near IMG Academy and the medical corridor, furnished monthly rentals can also support a durable income story, including a listed three-bedroom at $4,750 a month.
Palmetto and Ellenton are commonly cited as lower-entry corridors, but the research holds no independent pricing data for them. Cortez, the working fishing village across the bridge, has the same gap. Skip precise claims on either until comps say otherwise.
Consider an investor with a small mainland fourplex or duplex. Multi-unit stock is where income-stacking works best in this corridor, and it usually offers the most cushion above 1.00. The trade-off is a thinner buyer pool at exit than for a single-family house.
West Bradenton and Palma Sola are equity plays, not cash-flow plays. West Bradenton carries a $415,000 median sale price, homes going under contract in about 22.5 days, and a 17.0 percent year-over-year drop. It is strong by Redfin’s scoring, yet prices are sliding. Palma Sola is pricier still, with a median list near $899,000 at $303 per square foot. Canal-front homes with Gulf access via Anna Maria Sound are a mainland proxy for island pricing. An owner here is betting on convergence with the island, not on rent covering the payment. That bet can pay, but coverage on these files typically runs well below the mainland workforce corridor, so the cash-out case rests on appraised value and compensating factors rather than the rent line.
Side by Side: Modeled Coverage
The table below uses market values and rents from the research, combined into modeled 75 percent LTV scenarios. It shows coverage including taxes and insurance, rounded down. The rent and value pairings are illustrative assumptions.
| Submarket | Value marker | Rent marker | Modeled coverage |
|---|---|---|---|
| Anna Maria City cottage | $1.8M median | $3,000 | Well under 0.50 |
| Bradenton core | $359K median | $2,067 | High 0.8s to low 0.9s |
| Bradenton citywide | $312,743 median | $2,067 | Right around 1.0 |
| South Bradenton house | $180K median | $2,050 | Above 1.5 |
Not every seller’s gain is a lender’s equity. The island owner has the highest value and the lowest coverage. The South Bradenton owner has the reverse.
Where the Proceeds Go
Cash-out proceeds are only as useful as the next deal. The strongest use in this market is buying mainland cash-flow property with island-derived equity, which is the same rotation the coverage data supports. An owner who extracts from a high-value island asset and redeploys into Bradenton or South Bradenton rentals converts paper appreciation into rent-producing property. Whether the rotation makes sense depends on how the island asset itself performs, and the honest view is that this is a genuine toss-up. Holding the island cottage for appreciation and financing a mainland purchase separately might beat a cash-out that stretches coverage. Compare DSCR versus conventional options before committing, and see DSCR loans in Florida for the statewide picture.
One pattern from Lendmire’s deal desk applies to markets structurally like this one. Files with high values and thin long-term rent comps tend to stall on two items: the appraisal, because comp depth is limited, and the rent support, because year-round leases are scarce. The cleaner files usually document a signed lease or a well-supported market rent early, and they carry more reserves than the minimum. Getting the appraisal expectation and the rent evidence lined up before the file goes to a lender saves the most friction.
Title structure matters for the borrower’s plan. Many island investors hold property in an LLC, and vesting in an entity is workable subject to lender program eligibility. Confirm current local rules, taxes, and insurance with qualified local professionals before underwriting, since these vary by municipality and change often. To run a specific file, investors can start your quote or call 828-256-2183.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance on Anna Maria Island?
Qualification centers on the property’s rent compared with its full monthly obligation, with 1.00 as the typical baseline. Lenders also review the appraisal, about six months of ownership, a credit score in the 620-plus range, and reserves of about six months. On the island, the rent line is the hard part because long-term comps are scarce, and outcomes depend on lender guidelines and property review.
DSCR vs. conventional financing
Two common ways to finance an investment property in Anna Maria Island, FL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Anna Maria Island, Florida?
Most programs review credit tiers from 620 up through 700, reserves of about six months (about nine above $1.5 million), and a coverage ratio near 1.00. Cash-out is capped at 75 percent LTV, and manufactured homes, log homes, and barndominiums fall outside these programs. Cottages, single-family homes, and legacy duplexes are the usual on-island property types, subject to lender guidelines.
Why does the median-versus-average gap in Bradenton Beach matter for a cash-out?
The gap signals a thin comp set where a few high-end sales skew the average. An appraiser has fewer clean comparable sales to support value, so appraisal variance is wider. Since proceeds are capped at 75 percent of appraised value, a conservative appraisal directly shrinks the equity available.
Is a mainland rental a better cash-out candidate than an island cottage?
Usually yes, on coverage. South Bradenton’s $180,000 median sale price against $2,050-plus rents supports coverage above 1.5 in modeled scenarios, while an island cottage models far below 1.00. The island can still win on appreciation, which is a different question from qualifying.
What down-payment ranges may DSCR lenders review for Anna Maria Island investment-property purchases?
Purchase files typically review about 20 to 25 percent down, with purchase LTV up to 80 percent on most files, subject to lender guidelines and credit review. Lendmire arranges DSCR investor loans, with eligibility reviewed mainly on the property’s rental income. Cash-out refinances are capped lower, at 75 percent.
The Choice in Front of Island Owners
Anna Maria Island owners face a binary decision. Refinance the island asset itself and accept thin coverage, wide appraisal variance, and reliance on lender flexibility in exchange for keeping every dollar of island equity working. Or hold the island for appreciation, finance mainland cash flow separately, and accept that Bradenton rents have softened while island values stay concentrated in a handful of comps. Either way, the deciding number is the same one that has always decided this market: whether rent from a property near the Manatee County hospital corridor can carry what the island’s values cannot.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a non-QM mortgage broker (NMLS# 2371349), Lendmire facilitates DSCR investor loans across 41 markets, including Washington, D.C. Eligibility is generally reviewed around a property’s rental income rather than personal income documentation, subject to lender guidelines, which suits LLC-structured portfolios and self-employed borrowers who fall outside conventional boxes. Lendmire is a two-time Scotsman Guide Top Mortgage Workplace, recognized by Scotsman Guide in 2025 and named a 2026 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin: Anna Maria Housing Market
2. Redfin: South Bradenton Housing Market
5. Wikipedia: Holmes Beach, Florida
8. Anna Maria
9. Redfin: Bradenton Beach Housing Market
10. Redfin: Bradenton Citywide
12. State College of Florida, Manatee-Sarasota
13. Randstad USA: Bradenton Jobs
14. Redfin: West Bradenton Housing Market
16. recognized by Scotsman Guide in 2025
17. a 2026 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Anna Maria Island, Florida · Super Jumbo DSCR Loans In Anna Maria Island · Luxury Rental DSCR Loans In Anna Maria Island: What The Rent Must Cover
Guides: Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.