
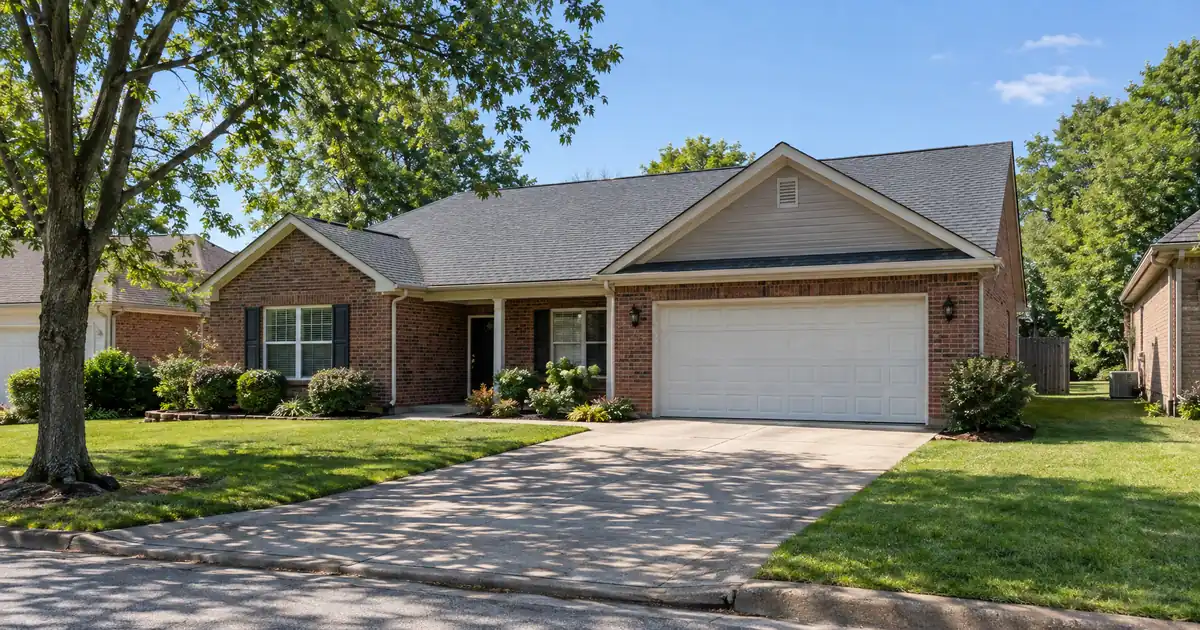
Redfin puts Murfreesboro’s median sale price at $405K over the three months ending in May, down 4.8 percent year over year, with homes taking 66 days to sell against 55 a year earlier. That is the backdrop for any DSCR cash out refinance in Murfreesboro, Tennessee. The pandemic-era run is over. Value has leveled off, and an owner who bought near the top may find the equity is thinner than the listing-site narrative implies. The investors with real room to pull capital out are holders with some seasoning and a property whose rent can carry a bigger balance.
DSCR Cash-Out Calculator
Run the cash-out numbers in Murfreesboro, TN
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A DSCR cash-out refinance in Murfreesboro, Tennessee is underwritten primarily on the property’s rental income measured against its full monthly obligation. Locally, flat prices and flat rents make the 75 percent LTV ceiling and a thin single-family rent-to-price ratio the binding constraints, not the seasoning requirement.
- Median sale price sits near $405K with 66 days on market, per Redfin.
- Modeled median-priced 3BR houses land below 1.00x including taxes and insurance at full leverage.
- Duplexes and small multifamily model materially stronger than single-family on the same loan structure.
- MTSU, manufacturing wages and Nashville commuters create three distinct tenant tiers.
- Cash-out caps at 75 percent LTV after roughly six months of ownership.
Murfreesboro Market Snapshot
A quick read on the Murfreesboro investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $405K median (Redfin, Murfreesboro housing) |
| Typical rents | $2,195 and $2,200 rents (Redfin multi-family listings) |
| Cap rates | 6–8% cap rates (Dyad property management guide) |
| University enrollment | 20,488 students (Wikipedia, MTSU) |
| Vacancy | 12-day (Dyad property management guide) |
Equity Is Thinner Than the Headlines Suggest
Murfreesboro’s price signals conflict, and the spread matters for cash-out proceeds. Redfin’s $405K median is the figure used here. Zillow shows a higher average home value of $430,785, down 0.3 percent, reflecting a different methodology. WGNS Radio, citing Construction Coverage, reports $424,995, up 1.9 percent, and notes that only 12.6 percent of homes sell above asking versus 27 percent nationally.
Read together: flat to slightly negative, with buyers holding leverage. For a cash-out, that means the appraisal is the swing factor, and a value that comes in at or below purchase price leaves nothing to extract. The program structure is straightforward. Ownership of about six months, measured from title recording, sets the seasoning floor. The loan ceiling is 75 percent of value. Proceeds equal that ceiling minus the existing payoff, and the equity available depends on rent used for lender review, the full monthly obligation, reserves and the LTV cap. It is not a guaranteed cash figure, and guidelines vary by lender.
An owner who bought at peak pricing with a high-leverage first loan should run the payoff against a conservative value before spending a dollar on the file. Skip the optimism.
The Median House Is a Coverage Problem
Here is the plain math on the typical Murfreesboro rental. Rentometer puts 3BR rent at $2,071. Against a $405K median price, that is roughly 0.51 percent per month (arithmetic, not a sourced statistic). Modeled at 75 percent leverage with full taxes and insurance in the obligation, coverage lands around 0.85x to 0.95x. Rent assumptions vary: RentHop shows 3BR rentals averaging $2,223, up 10.24 percent, though other sources show rents essentially flat. Zumper has overall median rent at $1,799.
Treat those as modeled assumptions, not guaranteed outcomes. The standard DSCR benchmark is 1.00x because rent covers the obligation at that level. Some lenders review lower ratios with compensating factors: lower leverage, more reserves, different pricing. Those structures come with trade-offs, and eligibility depends on lender guidelines, credit and property review.
The practical read: a median house can work as a cash-out candidate if the existing balance is low enough that a reduced-leverage refinance still produces useful proceeds. A full 75 percent pull on a median house is a sub-1.00 conversation.
Where Coverage Clears: The 2-4 Unit Band
The stronger play is small multifamily, and the listings data supports it directionally. Redfin’s multi-family listings show five properties at a median list of $485K. One listed duplex was rented at $2,195 and $2,200 per side, about $4,395 from one deed. Against $485K that is roughly 0.9 percent monthly rent-to-price, nearly double the single-family ratio. Modeled at full leverage including taxes and insurance, coverage runs around 1.4x.
Caveats apply. Five listings is a tiny sample, and the $485K median is not that duplex’s ask price. Platforms disagree on inventory: Homes.com shows 39 multi-family listings from $219,000 to $654,900. The low end of that band is where coverage math gets interesting, but pull MLS comps before underwriting anything. No reliable data turned up for fourplex or ADU pricing here.
The multi-unit case is also the right use for proceeds. A single house that can only clear 1.00x at reduced leverage may still fund a duplex down payment, and that duplex then carries its own coverage.
Blackman, Siegel and the East Side
Submarket data is thin, and no reliable neighborhood-level rent source exists. Zumper notes it lacks enough active inventory to publish neighborhood rents. What follows is directional.
Blackman (37128) is the family-tenant, newer-construction corridor near I-24 and I-840. PropertyIQ shows a $441K median, up 0.4 percent, with 56 days on market. Dyad Property Management, a local manager whose guide is marketing rather than independent data, cites newer-construction rents of $1,700 to $2,300 across the Northwest and Siegel High areas. At $441K even the top of that band models around 0.85x to 0.9x with taxes and insurance at full leverage. Strong tenants, expensive entry. Not a cash-out candidate for maximum proceeds.
Siegel (37129) has the longest tenancies in the manager’s claims (two to four years, 12-day vacancy) but also the highest purchase prices. Those tenancy figures are manager claims. Use them qualitatively.
Downtown and East (37130) carries the lowest entry prices among the main corridors. Redfin’s downtown median is $440K, down 19.5 percent year over year, but that is a small, noisy sample. Older east-side stock is where price-to-rent generally improves, which matters for coverage. It also demands the closest appraisal scrutiny.
Student Stock and the Enrollment Cliff
Does the MTSU renter pool justify aggressive underwriting near campus? Less than it appears. Middle Tennessee State University carried about 20,500 students in its most recent fall headcount per Wikipedia’s MTSU entry, a dated and secondary source. The president’s office reports more than 9,000 freshmen admitted for the coming fall and close to 5,000 graduates a year. Admits are not enrollment.
The same letter warns the “enrollment cliff” has arrived, with Tennessee high school graduates set to decline for several years. It adds that Middle Tennessee schools should not see as much of a decrease. Fair, but not a guarantee.
Student configurations run $1,200 to $1,800 for 2BR and 3BR homes near campus, about $400 to $600 per bedroom. One listing less than a mile from campus rents a 4BR unit by the room at $650 each, $2,600 total, against Rentometer’s $2,454 average for 4+BR. A DSCR lender may underwrite that on a standard lease or appraiser rent schedule instead of the by-the-room total. Confirm the lender’s treatment before counting it. Student units also churn every August.
No reliable vacancy survey turned up for the city. Stress-test student-oriented assets at 5 to 8 percent vacancy rather than assuming the flat-rent market stays full.
Workforce and Commuter Tiers
The non-student tiers are the steadier base. Rutherford Works lists Ascension Saint Thomas Rutherford, Amazon, Murfreesboro City Schools, Schneider Electric, General Mills, Franke, Cardinal Health and Stevens Aerospace among the county’s largest employers. The Rutherford County Chamber, via WKRN, reports employment growth of 11 percent over five years. Commuter overflow from Nashville adds a third tier.
Rental depth is real. Point2Homes counts 26,898 renter-occupied units against 30,501 owner-occupied, roughly 47 percent renters, with 46 percent of rentals family households. Where the demand is this broad, vacancy risk concentrates in apartments and student stock, not in workforce houses.
Working DSCR brokers see a recurring pattern in markets with flat appreciation: the coverage number, not the equity number, ends up controlling the loan size. Borrowers arrive expecting a 75 percent pull, then find a lower-leverage structure or a multi-unit property is what makes the file work. The fix is usually portfolio sequencing, using a modest single-family proceeds pull to fund the higher-coverage asset.
Putting Proceeds to Work
Cash-out proceeds only add value if they buy coverage. The refinance pathway for investor properties and pulling equity out explain the mechanics. The DSCR fundamentals cover the ratio itself, and DSCR versus conventional covers why rental income, not personal income, drives the review. Investors can pull a DSCR quote or call 828-256-2183. For state context, see Lendmire’s page on Tennessee DSCR financing.
Verify current local rental rules, taxes and insurance with qualified local professionals before committing.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Murfreesboro?
Qualification centers on the property’s rent against its full monthly obligation, with 1.00x as the common benchmark. Typical guidelines call for about six months of ownership, a maximum of 75 percent LTV, a credit floor around 620 and roughly six months of reserves. Exact eligibility depends on the lender, credit profile and property review.
DSCR vs. conventional financing
Two common ways to finance an investment property in Murfreesboro, TN. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What loan sizes, ownership structures and property types are eligible for a DSCR loan in Murfreesboro, Tennessee?
Standard programs generally run up to $3,000,000, with smaller balances placed through select lenders in the network. LLC-titled properties may be eligible, subject to lender program eligibility. Manufactured homes, log homes and barndominiums fall outside these DSCR programs.
Can by-the-room rent at a student house count toward coverage?
Sometimes, but do not assume it. Lenders commonly rely on a standard lease or an appraiser’s market rent schedule, which may come in below a by-the-room total. Confirm how the lender treats it before building the coverage math around it.
Does flat appreciation hurt a cash-out here?
Yes, mostly through the appraisal. With the median down 4.8 percent year over year, an owner who bought recently may find little room under the 75 percent ceiling. Longer-held properties with a lower payoff are better candidates.
Last Word
Murfreesboro offers student, workforce and commuter tenant tiers, but flat values and a median rent-to-price ratio near half a percent limit what single-family equity can fund. If you only take one thing from this piece, it’s this: in Murfreesboro the equity often sits in the house, but the coverage to use it sits in the duplex.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
A DSCR-focused mortgage broker, Lendmire (NMLS# 2371349) places investor financing across 41 markets — 40 states plus Washington, D.C. — with DSCR eligibility generally reviewed by the lender on property cash flow instead of traditional personal-income documentation, subject to lender guidelines. Scotsman Guide named Lendmire a 2026 Scotsman Guide Top Mortgage Workplace and recognized by Scotsman Guide in 2025.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin, Murfreesboro housing market
2. Redfin’s multi-family listings
5. Zillow
6. WGNS Radio
8. RentHop
9. Zumper
10. Homes.com, multi-family listings
11. PropertyIQ
12. Redfin — Downtown Murfreesboro Housing Market
13. Middle Tennessee State University
14. MTSU Office of the President
15. Rutherford Works, largest employers
16. Point2Homes, Murfreesboro rent data
17. a 2026 Scotsman Guide Top Mortgage Workplace
18. recognized by Scotsman Guide in 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Murfreesboro Tennessee · DSCR Loans in Murfreesboro, Tennessee: Investor Financing for Midtown, Northwest Murfreesboro, and the Gateway District — Rapid Growth Market & Real Estate Investors · DSCR Cash Out Refinance in Dyersburg, Tennessee: Can the Rent Support a Cash-Out in Dyersburg?
Guides: Investment Property Cash-Out Refinance in Murfreesboro, TN · Investment Property Cash-Out Refinance in Tennessee
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.