
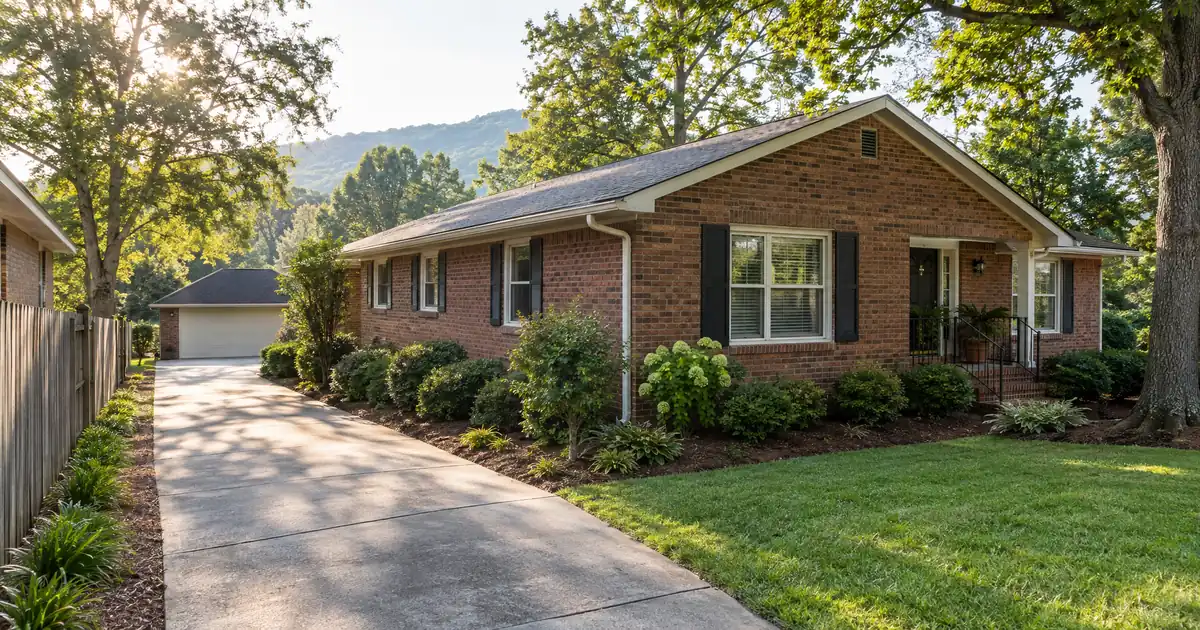
Picture an out-of-state investor scrolling Jackson listings. The first thing that catches the eye is price: a median sale price around $270K per Redfin, with 3-bedroom rents in the mid-$1,500s. The thing that gets missed is that Jackson is not a market where equity shows up on its own. A DSCR cash out refinance in Jackson, Tennessee works when the property was bought at a sensible basis or improved, and when the rent covers the full monthly obligation with room to spare. Market drift won’t do that work here.
TL;DR: A DSCR cash out refinance on a Jackson, Tennessee rental is underwritten primarily on the property’s rent measured against its full monthly obligation, with proceeds capped by a loan-to-value ceiling rather than by personal income. – Lower-basis 3BR houses cover their debt more comfortably than median-priced homes. – Small multifamily is 13.57% of housing units, but listings are scarce. – Appreciation is flat, so proceeds hinge on basis, rehab or rent growth. – Cash-out LTV tops out at 75%, with about 6 months of seasoning.
DSCR Cash-Out Calculator
Run the cash-out numbers in Jackson, TN
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Lendmire, a DSCR-focused mortgage broker (NMLS# 2371349), arranges DSCR investor loans across 40 states plus Washington, D.C., and was named a top-ranked workplace in 2026 by Scotsman Guide. This article is about the back end of the deal: the investor already owns the asset and wants to turn trapped equity into the next down payment. Purchase mechanics belong in a separate piece.
Jackson Market Snapshot
A quick read on the Jackson investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Employment | 7,000 jobs (The Kirkland Company) |
| Vacancy | 9.0% rental (Wikipedia, Madison County, TN) |
Jackson Is a Cash-Flow Market, So the Equity Has to Be Earned
The equity story in Jackson comes from how you bought and what you improved, not from market momentum. NeighborhoodScout puts Jackson’s latest annual appreciation below 90% of Tennessee cities, with the latest quarter at 0.00%. Redfin’s median sale price is down 3.6% year over year, and homes sold after 47 days on average. NeighborhoodScout’s median home value is $237,780, lower than Redfin’s $270K because the two use different methodology. This article uses Redfin’s figure for the citywide median.
An appraisal that comes in flat caps the proceeds, and that’s the honest starting point. Owners who bought below market, renovated a dated 3BR or raised rents on a stabilized unit have the strongest refinance files. Owners counting on the market to lift value have the weakest.
Price Tier Decides the Coverage
Coverage in Jackson depends far more on what you paid per door than on the rent, because rents cluster tightly around the market while prices spread widely. Zumper shows 3-bedroom rentals at $1,520 and 2-bedrooms at $1,165 (a thin sample of 57 rentals, so treat it as directional). Divided by a $270K median, that’s roughly 0.56% monthly rent-to-value. That figure is derived and market-wide, not a submarket read.
A Coldwell Banker Southern Realty market piece frames quality 3BRs at $120,000-$200,000 to buy, with rents of $1,000-$1,500. Its worked example is a $150,000 house renting for $1,200, or 0.8% monthly. It’s broker marketing, so use it for the range only. Still, the direction matches what the Zumper numbers imply.
Here’s how modeled coverage moves across price tiers. The prices and rents are modeled assumptions for illustration. Each ratio is rent divided by full PITIA (principal, interest, taxes and insurance), at 75% LTV, rounded down. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
| Modeled scenario | Price | Rent | Coverage |
|---|---|---|---|
| Workforce 3BR | $150,000 | $1,200 | About 1.3x |
| Median-priced 3BR | $270,000 | $1,520 | Just under 1.0x |
| Mixed 2BR/3BR duplex | $300,000 | $2,685 | About 1.4x-1.5x |
The median-priced house lands just under the 1.00x benchmark. That doesn’t end the conversation. Options a lender may review include a sub-1.00 program, an interest-only structure, or a lower LTV, all subject to lender guidelines, credit approval and property review. The cleaner fix is the lower-basis house, which is where the way DSCR coverage is calculated works in your favor.
Underwrite by price tier, not by the citywide median.
Duplexes: Thin Inventory, Better Cushion
Two-unit properties give Jackson investors the most coverage cushion, but the pool is small and appraisal comps are thin. Duplexes, converted homes and small apartment buildings are 13.57% of Jackson’s housing units, while single-family detached is 63.67%. Homes.com counted only six multi-family homes and duplexes for sale.
Redfin’s multifamily page shows what the product looks like: a turnkey duplex with two 2-bed/2-bath units, and a North Jackson duplex pairing a 3BR/2BA side with a 2BR/1.5BA side. Stack a 3BR at $1,520 and a 2BR at $1,165 and the modeled coverage above climbs well past the single-family version.
The catch is the appraisal. With few sales, a cash-out appraiser may reach outside the immediate submarket for comps, and that can pull value down. A duplex owner should expect the appraisal, not the rent roll, to be the binding constraint.
The Homes.com page also lists a historic Midtown/LANA building with approved plans for 11 units of 650 square feet each. That’s a value-add or development story, not a stabilized DSCR asset. Skip it for cash-out purposes until it has leases in place.
Where Jackson’s Refinance Files Sit
Four pockets do most of the work for cash-out files: North Jackson, the hospital and university areas, the Stanworth and Lawrence single-family belt, and the I-40 industrial corridor. No reliable neighborhood-level rent source exists for Jackson (Zumper itself says neighborhood data isn’t available), so the differences below are qualitative.
North Jackson (the North Highland, Oil Well Road and University Parkway corridor) is the higher-basis end. Dyad Real Estate puts homes from $200,000 for smaller ranch styles to $450,000 or more for executive homes. Tenants skew toward professionals, faculty and healthcare workers. Higher basis means cash-out leverage leans on the appraisal. Retail is also shifting: WBBJ reported Old Hickory Mall listed for sale by its owner, with activity moving toward the Vann Drive corridor. Don’t treat that as settled.
The hospital and Union University areas trade steadier occupancy for more cost per door. Dyad Property Management, a local manager, says these areas command slightly higher rents and offer the best mix of tenant quality and occupancy. It’s marketing copy, but the split is logical.
Stanworth and Lawrence are suburban single-family areas with I-40 and US-45 access. Livability describes Stanworth’s mostly 1970s ranch, split-level and brick homes on generous lots, and Lawrence’s proximity to Muse Park and the West Tennessee Healthcare Sportsplex. They fit the workforce 3BR profile, which is the deepest rental product in a city where three- and four-bedrooms are the most common unit size.
The I-40 industrial corridor and Bemis are yield-led. Dyad describes the industrial corridor as offering the highest gross yields while requiring more active management. A cash-out appraiser will treat these areas differently from the hospital side, and turnover risk is real. Dyad’s claimed 7-9% cap rates are manager-reported with no method behind them, so don’t underwrite to them.
Downtown Jackson has a June median near $235K on only 7 sales. Too thin to rely on.
The Tenant Demand That Already Exists
Jackson’s rental base rests on anchors that exist today: healthcare, manufacturing, education and commuters. The metro holds 183,680 people and 75,841 households, with a median household income of $62,566, per Census Bureau QuickFacts. The Kirkland Company calls West Tennessee Healthcare the metro’s largest employer, with 7,000 jobs anchored by the 642-bed Jackson-Madison County General Hospital.
The Greater Jackson Chamber says more than half of Madison County employees commute in from outside the county, and the labor draw area spans Madison and the surrounding eight counties. Many of those workers could live in the city and currently don’t. That’s the long-term rent-demand argument.
Manufacturing adds a second pool. The chamber’s industry page notes Toyota Motor Manufacturing Tennessee’s engine block plant with a 400+ workforce, and Delta Faucet in Jackson since 1995. Union University enrolls 1,856 undergraduates per a regional college. That’s small, so student rentals are a niche.
Vacancy needs a straight read. Wikipedia’s Madison County entry, citing the last decennial census, shows 37.6% of occupied units renter-occupied and a 9.0% rental vacancy rate. Those are county-wide, dated figures, but 9% isn’t tight. Underwrite with a real vacancy allowance instead of assuming full occupancy.
Working DSCR brokers see a recurring pattern in secondary regional hubs like this one: coverage looks fine on the rent roll, then softens once the lender applies its own vacancy and expense factors and the appraiser leans on distant comps. The files that go smoothly usually arrive with a lease history, a fresh appraisal expectation and an honest read on which submarket the property sits in.
Skip the BlueOval Bet.
Base your cash-out numbers on the hospital, the plants and the campuses, not on Ford. The chamber-commissioned housing study projected roughly 3,500 new single-family homes and 1,600 multi-family units in Madison County by 2035, as quoted by the Beacon Center of Tennessee. That rested on growth from BlueOval City, about 40 miles west of Jackson per the Jackson Post.
Wikipedia now describes the original EV campus plan, with 5,800 planned jobs, as not realized, with gas-powered trucks planned instead. Confirm current status from a primary Ford source. Treat any spillover as upside, not a base case.
How the 75% Ceiling and Seasoning Shape Proceeds
Cash-out proceeds are set by three things: rent used for lender review, full monthly obligation and the 75% LTV ceiling. On most files, seasoning runs about 6 months of ownership measured from title recording, and reserves run about 6 months of PITIA. Credit tiers step up from a 620 floor, and loan amounts run up to $3,000,000 on standard programs, with smaller balances routed through select lenders in the network. The minimum coverage benchmark is 1.00x. Some lenders may review lower scenarios with stronger compensating factors or less leverage. All of this is subject to lender guidelines, credit profile, property review and state overlays.
Because Jackson isn’t appreciating, the LTV math tends to bind before the coverage math does on higher-basis homes, and the reverse on lower-basis ones. A $270K house that appraises flat leaves little to pull. A rehabbed $150K house that appraises well above its purchase basis leaves more. The dollars come from the calculator, since equity is never a guaranteed figure. Pulling equity with a DSCR cash-out works best as a recycling step: proceeds fund the next low-basis purchase, and the cycle repeats. Loans to LLC-titled entities are available, subject to lender program eligibility.
To see how a specific file might structure, run the numbers with Lendmire or call 828-256-2183. Lendmire’s broader guidance on refinancing options covers rate-and-term alternatives, and the comparison of DSCR and conventional financing below explains why owners with several rentals often prefer property-income underwriting. Lendmire’s Tennessee DSCR platform covers the state overview. Verify current local rental rules, taxes and insurance with qualified local professionals before closing on any assumption here.
DSCR vs. conventional financing
Two common ways to finance an investment property in Jackson, TN. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Jackson, Tennessee?
Qualification centers on the property’s rent versus its full monthly obligation, not personal income. Most files look for coverage at or above 1.00x, a credit score of at least 620, about 6 months of seasoning and about 6 months of reserves. A Jackson 3BR renting near the Zumper median of $1,520 can clear that benchmark when the price basis is low enough. Final eligibility depends on lender guidelines and property review.
What are the requirements for an investment property loan refinance in Jackson, TN?
Expect a 75% maximum LTV on cash-out, an appraisal, proof of rent (lease or market rent schedule) and reserves. Loan amounts run up to $3,000,000 on standard programs. Manufactured homes, log homes and barndominiums fall outside these DSCR programs. Terms are guidance, not commitments.
Does a flat Jackson market hurt a cash-out refinance?
Yes, if your plan depends on appreciation. With appreciation near zero and the median sale price down 3.6%, proceeds come from a low purchase basis, renovation or rent growth. Owners who bought below market or improved the property are in the best position.
Should I count on BlueOval City demand in Jackson?
No. The original EV campus plan has been scaled back, so treat any Jackson spillover as possible upside. Hospital, plant and campus employment is the sturdier base case for tenant demand.
The Choice in Front of a Jackson Owner
An owner with a stabilized workforce 3BR faces a real fork. Pull the equity now and redeploy it into a thin duplex market where comps are scarce but coverage cushions are wider. Or hold the cash flow and wait for a better appraisal, accepting that Jackson’s flat values may not deliver one soon.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire — NMLS# 2371349 — is a DSCR and non-QM mortgage brokerage with investor loan programs in 41 markets, including Washington, D.C. DSCR eligibility is commonly reviewed by the lender on property-level rent rather than personal income documentation, subject to lender guidelines, and the brokerage helps arrange financing for LLC-owned portfolios beyond conventional financed-property limits. Recognized by Scotsman Guide as a Top Mortgage Workplace in 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin
2. NeighborhoodScout — Jackson Real Estate
3. Scotsman Guide — Top Workplaces 2026
6. Zumper
8. Homes.com
9. Redfin — Jackson Multi Family Homes for Sale
10. Dyad Real Estate
11. WBBJ
13. Livability
16. jacksontn.com — Development Industries
17. Beacon Center of Tennessee
18. Jackson Post
19. Wikipedia
20. Scotsman Guide 2025 Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance Elizabethton Tennessee: Access Equity Without Income Docs · DSCR Cash Out Refinance Dyersburg Tennessee: Access Your Equity Without Income Docs · DSCR Cash Out Refinance McMinnville Tennessee
Guides: Investment Property Cash-Out Refinance in Jackson, TN · Investment Property Cash-Out Refinance in Tennessee
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.