
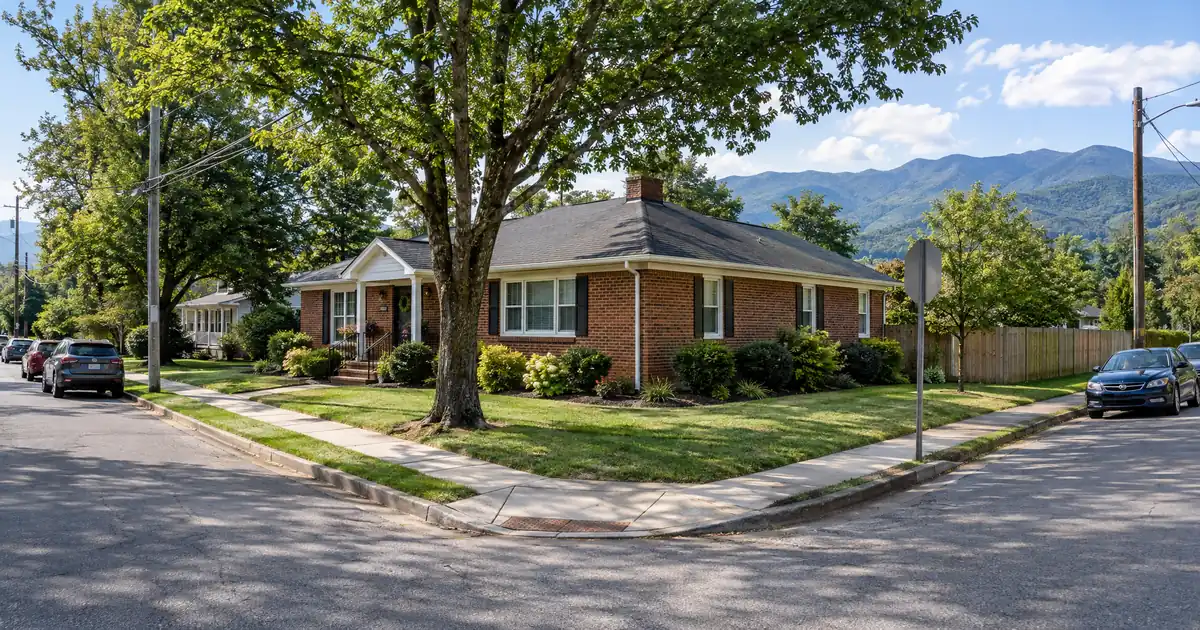
An out-of-state investor scrolling Elizabethton listings sees a median sale price of $260K, up 14.4 percent year over year per Redfin, and assumes a hot small town with fresh equity. Look one line down. Price per square foot is $168, down 16.0 percent, and only 61 homes sold in the latest month. That gap is the whole story for anyone planning a cash-out here: the headline gain is probably a sales-mix artifact, and the appraisal, not the headline, decides how much capital comes out.
For real estate investors in Elizabethton, Tennessee, Lendmire helps structure and place DSCR financing through wholesale lenders operating in 41 markets, including D.C. (NMLS# 2371349). This piece covers only the equity-extraction side: what a cash-out looks like on a rental you already own, where the coverage math holds, and where it doesn’t.
DSCR Cash-Out Calculator
Run the cash-out numbers in Elizabethton, TN
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read: A DSCR cash-out refinance in Elizabethton, Tennessee is underwritten primarily on the property’s rental income measured against its full monthly obligation, so a rental you already own can be reviewed for equity release based on cash flow rather than personal income documents, subject to a loan-to-value ceiling, seasoning, reserves, and an appraisal that supports the value.
- Median sale price sits near $260K per Redfin, with thin monthly sales volume.
- Cash-out caps at 75 percent LTV after roughly six months of ownership. Sample single-family asking rents of $1,500 to $1,900 put coverage near the 1.00 floor.
- Multifamily inventory is nearly absent, so duplex stacking takes patience.
- A hospital, a manufacturer, and a university anchor tenant demand.
Elizabethton Market Snapshot
A quick read on the Elizabethton investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | 61 sales (Redfin Elizabethton Housing) |
| Typical rents | $31,433 renter income (Point2Homes Demographics) |
| Recent appreciation | +14.4% yoy (Redfin Elizabethton Housing) |
| University enrollment | 2,500+ students (City of Elizabethton) |
| Employment | 5.91K employees (Data USA Elizabethton) |
Why the Median Price Jump Shouldn’t Set Your Cash-Out Number
Underwrite the appraisal, not the headline. Redfin shows the median up 14.4 percent while price per square foot fell 16.0 percent, and PropertyIQ’s ZIP 37643 data shows values up about 3.4 percent over twelve months, with roughly 23 percent of active listings carrying a price cut. Days on market ticked up to 47 from 43.
Read those together. The underlying trend looks like low single digits, and a few larger homes closing in a small sample can drag the median around. With 61 sales in a month, comps are shallow. An appraiser working from shallow comps tends to be conservative, and a conservative value at a 75 percent LTV cap shrinks proceeds fast.
So the planning rule is simple. Model your equity on what a cautious appraiser could reasonably land on, and treat any gain above that as a bonus. If the deal only works at the headline number, it doesn’t work.
The Coverage Math on a Median-Priced House
Run the numbers on a modeled house at the $260K median price. Assume a rent of $1,700, which sits inside the range of sample three-bedroom asking rents of about $1,500 to $1,900. These are modeled inputs, and asking rents aren’t achieved rents. Take a cash-out at 75 percent LTV on a 30-year amortization, count taxes and insurance in the full obligation, and coverage lands around 1.1x. At $1,500 rent it slips just under 1.00. At $1,900 it reaches the low 1.2 range.
That rent-to-price ratio, roughly 0.6 to 0.7 percent monthly, is the honest constraint on this market. Standard DSCR programs are built around a 1.00 minimum (rent versus full PITIA), and a typical Elizabethton house sits right on top of it at the leverage cap. Some lenders review sub-1.00 files, but that usually means less leverage, stronger credit, and more reserves.
Two levers move the number. First, pull less than the cap. Taking 65 or 70 percent instead of 75 lifts coverage noticeably, and the freed-up cushion often matters more than the last few points of proceeds. Second, use the higher-rent stock. Rents on sample listings vary widely, and a renovated three-bedroom near the Milligan and Johnson City commuter corridor is a different asset than a dated one on the east side.
Lendmire’s primer on DSCR loans covers the ratio mechanics, and the program-to-program comparison explains why a rental-income basis matters for entity-owned or self-employed borrowers.
What Sets a Cash-Out Apart From a Purchase Here
Seasoning and appraisal risk define the file. Cash-out generally requires about six months of ownership measured from title recording, so a rental bought and renovated last quarter usually isn’t ready. Reserves run about six months of PITIA on most files, and credit tiers start at a 620 floor, with better positioning at 660, 680, and 700. Loan sizes run up to $3,000,000 on standard programs, which is far beyond anything Elizabethton’s price band will test. All of this is subject to lender guidelines and property review.
The bigger practical point is that value drives proceeds. With a median near $260K and a lot of stock priced below it, many Elizabethton rentals produce modest cash-out sums even when the percentage math is clean. That’s fine if the goal is a down payment on the next deal, and disappointing if the plan needs a large lump sum. For the mechanics beyond this city, the cash-out refinance walkthrough lays out the full sequence.
Where the Equity Sits: Four Pockets of Elizabethton
Milligan and Cedar Grove (west side, ZIP 37682). This is the strongest tenant story in the city, though not for the reason most people guess. Milligan University has more than 1,300 students, and most live on its 355-acre campus, so don’t underwrite this as student housing. The rental demand is faculty, staff, and Johnson City commuters, since the area sits minutes from the boundary. Housing is small to medium single-family homes plus apartment complexes. For a cash-out, this is the pocket where a long hold and steady occupancy tend to support both the appraisal and the tenant file.
Downtown and the Historic District. Around the 1882 Elizabethton Covered Bridge and the county government area, tenants skew toward courthouse and county workers and small-business employees. It’s a steady, low-drama rental profile. No reliable price or rent data exists for the district, so treat coverage as deal-specific.
Watauga Point and Riovista. Older workforce stock, with many homes built between 1940 and 1970 and mostly owner-occupied. The catch: the area also includes mobile homes, and manufactured homes fall outside these DSCR programs entirely. Site-built houses only, and expect older systems to trim net income and appraisal support.
East Side along the Doe River and US-19E. Skip this for a first cash-out unless you’ve done the diligence. The river has a history of flooding that limited southward growth, and flood exposure can complicate both the appraisal and the file. Check it with local professionals before you commit.
The Sycamore Shoals and Watauga River corridor is worth a mention for its hospital adjacency, but there’s no price or rent data behind it, so it stays a qualitative watch-list area.
Sub-$150K Stock: Better Ratios, Thinner Proceeds
Cheap old houses look great on paper and awkward in a refinance. Sample listings show a one-bedroom house near $850 a month and apartments from about $530 to $895, which imply far stronger rent-to-value than the median house. I found no matching purchase prices, so those are snapshots, not comps.
Here’s the tradeoff. Coverage may clear easily, but the appraised value caps the cash you can pull, and thin comps in a low-priced band make appraisals harder to predict. This is the pocket for an investor who wants cash flow and plans to recycle small sums. It isn’t the pocket for a big equity draw.
Duplexes Would Fix the Math. Finding One Is the Problem.
Stacked units beat single houses on coverage, and this city barely has them. Two units at $979 to $1,449 each on one loan clear the obligation more comfortably than one $1,600 house. But Redfin showed 14 condos, one townhouse, and zero multifamily listings in a recent one-month window, and RentCafe puts the average apartment building at about 34 years old.
The stronger play is probably to buy a small multifamily when one surfaces, hold through seasoning, and cash out against it, though an investor who already owns a single-family house in the right pocket doesn’t need to wait for that. Older buildings mean capex, and capex shows up in net income and appraisals. Budget for a long search.
What the Tenant Base Actually Supports
Rents here are constrained by local incomes. Data USA reports median household income of $46,975, and employment grew 3.41 percent to 5.91k workers. Point2Homes shows 37.4 percent of households renting, renter median income of $31,433, and a 28.3 percent rent-to-income ratio. That ratio leaves little room for aggressive rent pushes, so underwrite rents as they are, not as you wish they’d grow. (The 11.2 percent vacant-unit figure on the same page is total housing stock, not rental vacancy.)
Demand anchors are real if modest. The TNECD Carter County profile lists Sycamore Shoals Hospital at an estimated 269 employees. Snap-on is the county’s third-largest employer, and its $44 million expansion adds 50 jobs. Elizabethton City Schools has over 2,500 students, and the city is one piece of a mid-sized county in the Johnson City metro, per Wikipedia’s Carter County entry. Rental sources disagree sharply, from $723 on Apartments.com to $1,034 on RentCafe, so lean on deal-level comps.
New Builds: A Low-Capex Hold, Not a Cash-Flow Play
New construction changes the risk profile but not the rent. NewHomeSource lists 20 communities from five builders, priced from $239,990 to $620,000, so the entry point sits close to the resale median. Rents don’t scale with price here, so a new build is an appreciation and low-maintenance bet. Coverage is tighter than on older stock at the same rent. Before counting on it for a future refinance, check builder incentives and whether resale comps support the price, because incentives can hide a soft appraisal.
The Deal Desk View on Markets Like This
In small Appalachian-corridor markets with thin sales volume, the common friction point isn’t the borrower’s credit or the lease. It’s the appraisal. Files with a documented lease, a clean ownership timeline from the recording date, and a value supported by at least a few recent nearby sales tend to move through lender review with fewer questions. Files that lean on a single headline appreciation number, or on rent assumptions above local comps, tend to get resized. Ordering the rent schedule and reserve documentation early prevents most of the re-trading.
Equity Into the Next Deal
Cash-out proceeds are a down payment on the next property, so the second deal has to survive on its own coverage. Elizabethton’s thin multifamily supply means the next asset may be in Johnson City or another Tri-Cities market, and that decision is worth making before you pull equity. For a broader view, the investment property refinance options and DSCR loan options for Tennessee investors show how the structure travels. When you’re ready to price a scenario, you can compare DSCR options or call 828-256-2183. As always, confirm current local rental rules, taxes, and insurance with qualified local professionals.
The Real Choice on an Elizabethton Rental
An owner here is usually choosing between two moves. Pull a smaller draw, closer to 65 or 70 percent, and keep coverage comfortably above 1.00 with a house that can absorb a soft appraisal or a vacancy. Or push toward the 75 percent cap to maximize capital for the next acquisition, and accept a file sitting near the coverage floor in a market where sales are thin and appraisals swing on a handful of comps.
DSCR vs. conventional financing
Two common ways to finance an investment property in Elizabethton, TN. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Elizabethton?
Qualification centers on the property’s rent versus its full PITIA, with 1.00 as the common minimum, plus about six months of ownership seasoning, a credit floor of 620, and roughly six months of reserves. The appraised value then sets the ceiling at 75 percent LTV. Because median-priced houses here run close to the coverage floor, the rent schedule matters as much as the credit score. Everything is subject to lender guidelines and property review.
What are the requirements for an investment property loan in Elizabethton, Tennessee?
The property must be an eligible type, meaning site-built single-family homes, condos, and small multifamily fit, while manufactured homes, log homes, and barndominiums fall outside the programs. Borrowers typically show a 620-plus credit score, documented rent, and reserves. Older stock near Watauga Point or the east side may need extra property review. Details vary by lender and borrower.
Can an LLC-owned Elizabethton rental be reviewed for DSCR financing?
Yes, subject to lender program eligibility.
Does the 14.4 percent price jump mean I have that much new equity?
Probably not. The median price rose while price per square foot fell, and ZIP-level data points closer to 3.4 percent growth. An appraiser working from a small set of recent sales will likely land conservatively, so plan proceeds off a cautious value.
Will a duplex give a better cash-out than a single-family house?
On coverage, usually yes, because two units at roughly $979 to $1,449 each carry more income than one house. The problem is availability, since Redfin showed no multifamily listings in a recent one-month window. Older buildings also bring capex that can reduce net income and appraisal support.
About Lendmire
A non-QM mortgage broker (NMLS# 2371349), Lendmire arranges DSCR financing for real estate investors in 41 markets, meaning 40 states plus Washington, D.C. Because deals are underwritten primarily on property cash flow rather than personal income documentation, the structure suits self-employed buyers and entity-owned portfolios. Lendmire places loans through wholesale investor lenders and is not a direct lender. The firm has been recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a 2025 Scotsman Guide Top Mortgage Workplace; the full Lendmire news archive has more.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. $260K, up 14.4 percent year over year per Redfin
2. Sample single-family asking rents of $1,500 to $1,900
3. Point2Homes
5. Data USA
6. PropertyIQ’s ZIP 37643 data
7. Elizabethton Covered Bridge
8. Zillow — Elizabethton TN Rentals
9. RentCafe — Apartments for Rent Elizabethton TN
10. Redfin showed 14 condos, one townhouse, and zero multifamily listings
11. TNECD Carter County profile
12. expansionsolutionsmagazine.com — Snap on to Expand Manufacturing Operations in Carter County
13. Wikipedia’s Carter County entry
16. NewHomeSource
17. a 2026 Scotsman Guide Top Mortgage Workplace
18. a 2025 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Elizabethton Tennessee · DSCR Cash Out Refinance Union City Tennessee: Access Equity Without Income Docs · DSCR Cash Out Refinance Dickson Tennessee
Guides: Investment Property Cash-Out Refinance in Tennessee
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.