
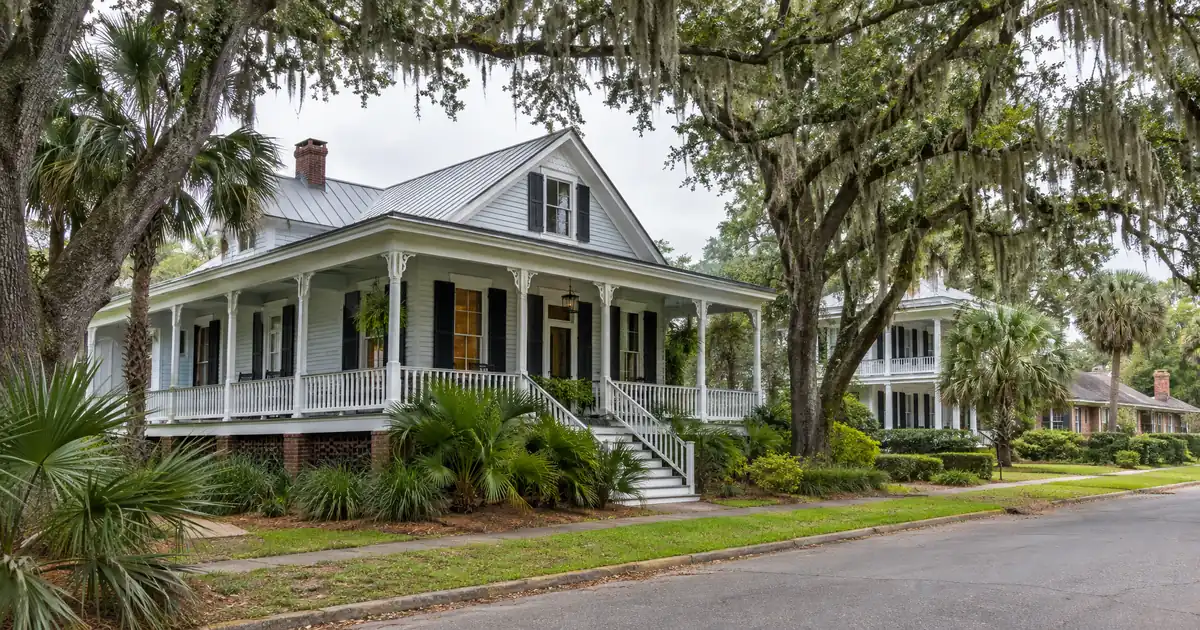
Picture two investors who each own a long-term rental on Edisto Beach. One holds an older, off-beach house bought well below the town’s median. The other holds a beachfront home bought near the top of the market. For a rent-driven cash-out refinance, the math favors the first investor. Median gross rent in town sits near $1,170 per Point2Homes, while the median property value is $719,200 per Data USA. That gap is a rent-to-value ratio of roughly 0.16% per month (Lendmire Research’s own arithmetic), and it explains why equity here is easy to see on paper and hard to convert into proceeds.
This article is about pulling equity out of a property already owned. It covers how the coverage number behaves in a town this small, what the seasoning and leverage limits do to the payout, and where the proceeds tend to go next.
DSCR Cash-Out Calculator
Run the cash-out numbers in Edisto Beach, SC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
At a Glance: A DSCR cash-out refinance in Edisto Beach, South Carolina is underwritten primarily on the property’s rental income measured against its full monthly obligation, so a market with high values and a small renter pool puts the appraiser’s rent schedule at the center of the file.
- Median property value is $719,200 per Data USA, with 85.6% homeownership.
- Only 11.7% of occupied units are renter-occupied, per Point2Homes.
- Zillow puts average value down 2.1% year over year, which pressures available equity.
- Cash-out leverage tops out at 75% LTV, with about 6 months of seasoning. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Edisto Beach Market Snapshot
A quick read on the Edisto Beach investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $719K median (Redfin Edisto Beach Housing) |
| Typical rents | $1,170 (Point2Homes) |
Start With the Off-Beach Streets and Attached Units
The strongest cash-out candidates in Edisto Beach are the lower-priced, off-beach detached homes and the attached townhome and condo product, not the oceanfront strip. Lower values shrink the payment side of the ratio faster than they shrink achievable rent, which is what moves coverage toward 1.00x.
The price spread is wide in a town this small, per World Population Review. City-Data puts mean detached-house values well above townhouse or attached values. The interior residential streets sit behind the beachfront strip, and they read as quiet and walkable to the water. Attached units cluster mostly inside the Wyndham Ocean Ridge resort community, which also has cabins and a golf course. Point2Homes says attached options such as duplexes and townhouses make up only a small share of the housing stock, while the large majority of units are detached single-family homes.
So the closest thing to small multifamily here is a townhome or condo. A conventional “buy a fourplex and stack rents” thesis doesn’t exist in this town. Skip it.
Now the rent side. The Zillow rental set is small (about 10 listings) and covers the whole island, most of it outside the beach town limits. Even so, it’s the best directional read available. Asking rents for 3-4 bedroom houses run from $1,800 to $4,100 per month. Against purchase prices of $700K-$790K, the top of that range gives a rent-to-value ratio of only about 0.4-0.5%. Against a lower-priced off-beach house, the picture improves.
Run the numbers on a modeled case. Assume a $475,000 property value (the median listing price for Edisto Island and Edisto Beach combined per Locating Charleston) and a 75% LTV cash-out. Assume $2,800 in market rent. Coverage on full PITIA, including taxes and insurance, lands right around 1.0x. That’s borderline, not comfortable. At $3,500 in rent the same modeled file moves into the low 1.2 range, and at $2,400 it slips to the high 0.8s. Those rent figures are modeled assumptions, not comps. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
What an Edisto file typically looks like. DSCR files in markets like this one, thin renter pools with high values, usually turn on one document: the appraiser’s market-rent schedule. Coverage that looks fine against an owner’s asking rent often compresses once the appraiser can only find a handful of long-term comparables. The stronger files show a signed lease at or near the appraised rent before submission. The weaker ones rely on a rent estimate from a listing aggregator.
The Beachfront Strip: Big Equity, Thin Coverage
Oceanfront and beachfront holdings carry the most equity in town and the weakest rental coverage. Here’s the catch: the same features that make the strip valuable (uncommercialized shoreline, waterfront inventory) don’t translate into long-term rents that scale with price.
Vacasa describes Edisto Beach as one of the last remaining uncommercialized beaches in South Carolina, and the Town of Edisto Beach calls itself one of the few remaining family-oriented, gently developed beaches on the state’s eastern coast. That scarcity supports price. It doesn’t support a monthly lease that covers a 75%-LTV payment on a property valued near the town median.
Run the numbers on the town median. Take a $719,200 property refinanced at 75% LTV, with rent modeled at $3,500. Coverage including taxes and insurance comes to about 0.8x. At $3,000 rent it falls to the low 0.7s. Even the $4,100 top-of-range asking rent from the Zillow set lands just under 1.00x. On a beachfront property valued well above the median, the shortfall widens. (For a house appraised over $1,500,000, reserves also step up to about 9 months of PITIA versus about 6 months below that threshold.) These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Coverage below 1.00x doesn’t automatically end the conversation, and it shouldn’t be treated as a verdict. Structures a lender may review include a sub-1.00 DSCR program, an interest-only period, or a lower LTV that trims the payment side. Each comes with tradeoffs: stronger credit, larger reserves, different pricing, or less cash out. Qualification is subject to lender guidelines, credit approval, and property review. The question worth asking first is whether the structure should be used. If the only way a beachfront file works is by stretching several of those levers at once, the better answer may be a smaller draw, or waiting.
Seasoning, LTV Caps and the Flat-Price Problem
Cash-out proceeds on a DSCR refinance are capped by three things at once: a 75% LTV ceiling, about 6 months of ownership seasoning measured from title recording, and the property’s coverage number. In Edisto Beach the appraised value is the least predictable input. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
The DSCR itself is simple. Monthly rent divided by the full monthly obligation (principal, interest, taxes, insurance and any HOA dues) has to clear the baseline, typically 1.00x on standard programs. Some lenders review lower ratios with compensating factors. The full breakdown covers the mechanics. What matters in this town is that appreciation can’t be assumed.
The value data disagrees with itself, which is a signal in its own right. Data USA’s median value of $719,200 reflects a 17.8% jump from $610,500 the prior year. Zillow’s average of $734,201 is down 2.1% year over year, a different methodology pointing the opposite direction. Redfin’s median sale price of $719K is down 4.1%, with median price per square foot at $500, down 2.2%. In a town with a few dozen sales a year, one large transaction can swing any of these numbers. This piece treats the $719,200 median as the working figure and the others as a caution.
A cash-out only works on appraised value. If values are flat to slightly down, an investor who bought within the last few years may find less equity available than the headline medians suggest. Stress-test the file at an appraisal several points below the last comparable sale before committing to a plan that depends on the proceeds. The exact cash figure depends on rent used for lender review, payment, reserves and the 75% cap, and it isn’t guaranteed.
Credit matters too. The network’s credit tiers step through 620, 660, 680 and 700, with 620 as the floor. Higher scores typically improve leverage and pricing options, subject to lender guidelines.
Six Months. Then What?
The seasoning clock is about 6 months from title recording, and on an Edisto file the practical bottleneck is usually not the clock but the comps.
Redfin reports the average home sells about 4% below list and goes pending in roughly 58 days. It also shows recent sales spanning about $600K in an interior area to $1.1M in an oceanfront area. A wide spread on a small number of sales gives an appraiser dispersed comparables and sometimes forces older or off-street comps into the analysis. That’s valuation risk for a cash-out, and it cuts both ways. The discount to list also hints that buyers have negotiating leverage on entry.
Inventory is thin. Movoto shows 16 homes for sale in Edisto Beach with a median listing price of $789K, or $504 per square foot. Locating Charleston’s combined island-plus-beach report shows a $475K median, and single-family homes are 94% of inventory. The $475K versus $789K gap shows how much the answer depends on which slice of the market the appraiser draws from. These are portal and brokerage figures, and they represent listings rather than closed values.
Renters Are Scarce, and That Shapes Everything
Only 11.7% of occupied units in Edisto Beach are renter-occupied, and about 74.7% of all housing units are vacant, per Point2Homes. That vacancy figure reflects seasonal and second-home use, not long-term rental vacancy. No reliable long-term rental vacancy or rent-growth series exists for the town.
Demand for a year-round lease comes from a thin base. Data USA counts 452 people employed in the town, with professional and technical services (56 people), accommodation and food service (49) and real estate and rental services (44) the largest sectors. Average commute is 27.5 minutes, so many residents work outside the town limits. The nearest hospital is Colleton Medical Center in Walterboro, a 135-bed HCA facility with 24-hour emergency care. Charleston is about 28.7 miles away, and Charleston International Airport is 42 miles from the heart of the island.
The SC Department of Employment and Workforce’s Colleton County profile lists the county’s largest employers alphabetically, without headcounts. It includes Colleton Medical Center, Wal-Mart Associates, Food Lion, Gehl Foods Southeast, Cracker Barrel, PruittHealth Walterboro and Wyndham Vacation Ownership, the resort operator on Edisto Beach. Edisto Beach sits in Colleton County while the rest of Edisto Island is in Charleston County, so local employment data comes from a rural county even though visitor and owner demand leans toward the Charleston metro. This is not an employer-driven or student-driven tenant base. Tenants are hospitality and service workers, seasonal residents and households renting before buying, and the pool is small.
That means a single vacancy can move a file. It also means a signed lease is worth more here than in a deep market.
DSCR vs. conventional financing
Two common ways to finance an investment property in Edisto Beach, SC. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Conventional or DSCR on This Type of Property?
For an Edisto investor with strong personal income and one or two financed properties, conventional financing may carry a lower cost and can work cleanly, because it doesn’t depend on a rent-to-payment ratio that this market struggles to produce. DSCR becomes the more practical path for LLC-held rentals (subject to lender program eligibility), self-employed borrowers whose traditional personal-income documentation understates income, and investors already past the conventional financed-property limits. The conventional vs DSCR comparison lays out the break-even. In this town the flip point comes earlier than usual: if the property can’t reach roughly 1.0x on an appraiser’s rent schedule, a DSCR cash-out is a weak fit regardless of portfolio size.
Where the Proceeds Go (This One’s a Toss-Up)
The proceeds argument depends on the next deployment. Pulling equity to buy another rental where coverage clears comfortably makes the strategy straightforward. Pulling equity to buy another Edisto Beach house at these prices repeats the same thin-coverage problem, only bigger.
The stronger play might be redeploying inland. Workforce single-family and small multifamily are more plausible around Walterboro, roughly 30 miles inland, where the county’s hospital and large employers sit. That’s analysis, not researched data, and the numbers there would need their own work. But for an investor whose Edisto property is over-equitied and under-covered, a modest cash-out used to buy in a market with a deeper renter pool can improve the whole portfolio’s coverage. Investors who own for appreciation and second-home enjoyment could reasonably argue the other way: keep the Edisto asset, take a smaller draw and accept lower coverage. Both are defensible.
Two more paths are worth naming. A rate-and-term refinance avoids the cash-out cap and leverage limits. The guide “The Refi Options” covers the difference and shows how proceeds are sized. And investors who want to talk through a specific file can reach Lendmire at 828-256-2183. For a wider view, the DSCR loan options for South Carolina investors page covers the statewide picture. Before underwriting anything on the coast, verify current local rental rules, taxes, flood and wind exposure and insurance with qualified local professionals.
Frequently Asked Questions
How do you qualify for a DSCR loan in Edisto Beach?
Qualification centers on the property’s rental income relative to its full payment. Most standard programs use 1.00x as the baseline, alongside credit tiers starting at a 620 floor and reserves of about 6 months of PITIA. In Edisto Beach the appraiser’s market-rent schedule carries extra weight because renter-occupied units are only 11.7% of occupied housing. Exact eligibility depends on lender guidelines, credit, reserves and property review.
What are the requirements for a cash-out refinance on an investment property in Edisto Beach, South Carolina?
Expect a 75% maximum LTV on cash-out, about 6 months of ownership measured from title recording, a 1.00x minimum DSCR on standard programs and reserves of about 6 months of PITIA (about 9 months above $1,500,000). Loan sizes go up to $3,000,000 on standard programs, and smaller balances route through select lenders. Manufactured homes, log homes and barndominiums fall outside these programs. All figures are subject to lender guidelines.
Can I use a duplex or small multifamily strategy in Edisto Beach?
Not realistically. Attached units make up only a small share of the housing stock, and duplexes sit mainly inside Wyndham Ocean Ridge. Most long-term-rental DSCR files here will be single-family homes, townhomes or condos.
Why do Edisto Beach appraisals carry more risk than a larger market?
Sales volume is small and price dispersion is wide, with recent Redfin-reported sales ranging from about $600K to $1.1M. An appraiser may have to reach for older or off-street comparables, which can pull the value below what an owner expects. That directly reduces available cash-out proceeds.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
Edisto Versus Walterboro
Edisto Beach wins on scarcity and equity, and Walterboro likely wins on rent-to-payment math, so for a cash-out that has to pass a coverage test, the inland market is probably where the numbers work right now while the barrier island rewards patience over payout.
About Lendmire
Lendmire is a DSCR-focused mortgage brokerage, NMLS# 2371349, placing investor loans across 41 markets, including Washington, D.C. Eligibility is generally reviewed by the lender on a property’s rental income rather than personal income documentation, which fits LLC-held rentals (subject to program terms), self-employed investors and portfolios scaling past conventional financed-property limits. Lendmire is a 2026 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2025.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. median property value is $719,200 per Data USA
3. Zillow — Home Values Edisto Beach SC
4. Redfin’s median sale price of $719K
6.
8. Vacasa describes Edisto Beach
10. Movoto shows 16 homes for sale in Edisto Beach with a median listing price of $789K
11. SC Department of Employment and Workforce’s Colleton County profile
12. a 2026 Scotsman Guide Top Mortgage Workplace
13. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Edisto Beach, South Carolina: How the Rent Math Clears at 75% LTV · DSCR Cash Out Refinance in Walterboro, South Carolina: The 2026 Guide to Downtown Walterboro · DSCR Cash Out Refinance in Myrtle Beach, South Carolina: A 2026 Refi Guide to Ocean Blvd
Guides: Investment Property Cash-Out Refinance in South Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.