
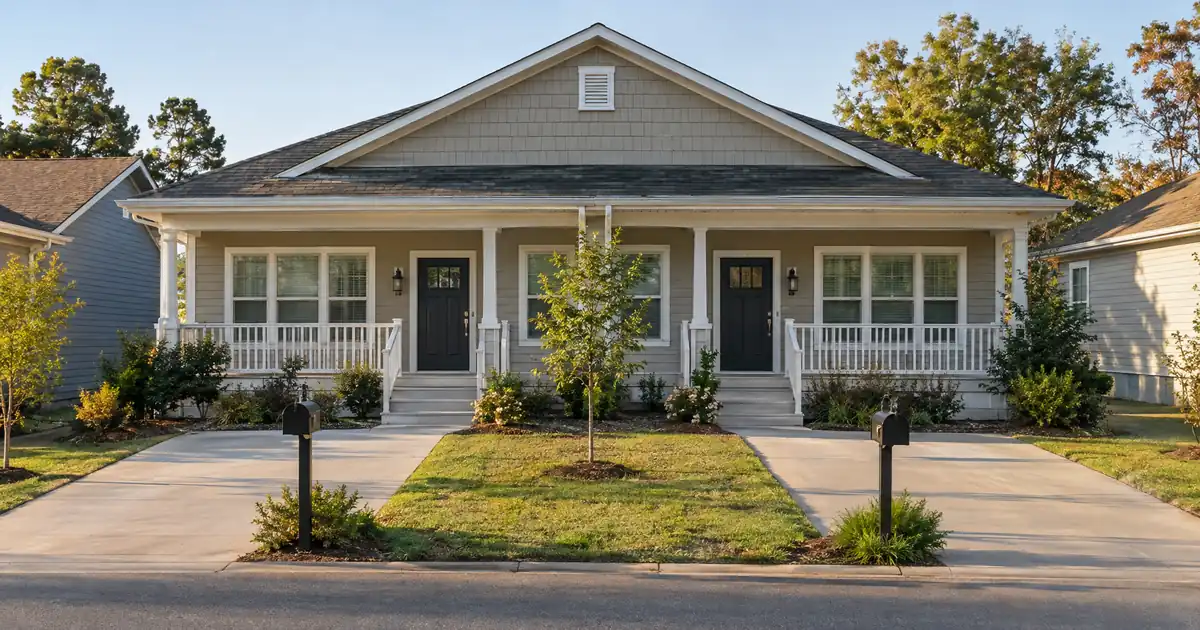
The Quick Read: A self-employed contractor can buy a duplex, live in one unit and rent the other with a small down payment, but only through an owner-occupied loan, never a DSCR loan, and the file qualifies either on two years of traditional personal-income documentation or on twelve months of bank statements, depending on how far write-offs shrink reported profit. The deciding factor is occupancy, because living in the building puts you in a different loan category than a pure rental buyer. DSCR financing becomes useful later, on the next property you do not live in.
- Living in one unit makes the loan owner-occupied, so DSCR is off the table for this purchase.
- FHA is the standard low-down route, and it reads your income from traditional personal-income documentation.
- Bank statement programs read deposits instead, which helps when write-offs cut your taxable profit.
- A duplex is the easiest multi-unit house hack because it skips the extra rent test that applies to three- and four-unit buildings.
- DSCR comes in for the property after this one, where rent carries the file.
Key Terms Defined
House hack: Buying a small multi-unit building, living in one unit and renting the others to cut your own housing cost.
1099 contractor: A self-employed worker paid without withholding who reports income on a personal tax return instead of receiving a W-2.
Schedule C net profit: The profit line on a self-employed tax return after business expenses are subtracted. Tax-return lenders review your file on this number, not on gross receipts.
Owner-occupied loan: A mortgage on a home you will live in as your residence.
FHA loan: A government-insured mortgage that allows a low down payment, including on two- to four-unit homes if you live in one.
Bank statement loan: A non-QM loan (a mortgage that sits outside standard agency underwriting) that is reviewed around documented income from your deposits.
LTV (loan-to-value): The loan amount divided by the property value. A 90% LTV means roughly 10% down. Each figure is subject to lender guidelines and a complete review of property type, leverage, and credit.
DSCR loan: An investor loan that qualifies a property primarily on rental income covering its payment, subject to lender guidelines.
Reserves: Cash you keep after closing, counted in months of the housing payment.
What your deposits qualify you for.
Alt-doc programs read 12 months of business or personal bank deposits instead of tax returns. Enter your average monthly deposits and see the income a lender would credit you.
The expense factor is set by the lender from your business type and profit-and-loss statement; it is not a number you choose. This widget quotes no rate and no payment.
Program parameters shown update from Lendmire’s centralized guideline source.
Estimate
Illustrative estimate only — not a quote, Loan Estimate, approval, or commitment to lend. Deposit average, expense factor, and housing ratio are editable assumptions; the expense factor a lender applies is set from your business type and documentation. No interest rate or monthly payment is quoted here. Purchase capacity is a simplified illustration and does not account for taxes, insurance, HOA dues, or other debts. Alt-doc income documentation is available on consumer mortgages in the states where Lendmire is licensed for consumer lending; actual terms vary by lender, borrower, and property.
What a House Hack Looks Like for a Self-Employed Buyer
A house hack is simple on paper. You buy a duplex, move into one side and let a tenant pay for much of the other. Lofty’s house-hacking guide describes the standard structure as an owner-occupied loan on a duplex, triplex or fourplex, with the owner living in one unit and renting the rest.
The appeal for a contractor is cash. A rental purchase usually asks for a bigger down payment than an owner-occupied one. Owner-occupied loans often need far less cash up front, which is why this strategy suits people who are earning well but have not stacked up a large down payment.
The same guide flags the cost of going low. A low down payment means thin equity. On a 3.5% down FHA purchase with closing costs rolled in, you can sit near 100% loan-to-value if prices go flat. Keep that in mind when you decide how much cash to put in. Leverage, reserves, and pricing vary by lender and program; the final terms follow the full file review.
Why a duplex and not a fourplex? Two units keep the underwriting lighter. More on that below.
How Lenders Read a 1099 Contractor’s Income
Lenders read a contractor’s income in one of two ways, and the difference can decide the whole file. One route trusts your traditional personal-income documentation. The other trusts your deposits.
The tax-return route (FHA). An FHA loan treats you as self-employed. Lenders generally want a two-year self-employment history and two years of personal returns. Qualifying income comes from net profit, not gross 1099 receipts. That means every write-off you take lowers the income the underwriter can use. Lender rules differ in the details, so confirm the specifics against the HUD handbook index at HUD’s handbook library, which points to Handbook 4000.1.
The bank statement route. Across the wholesale network Lendmire works with, bank statement programs typically look at twelve months of business or personal statements. The lender averages your deposits and applies its own expense factor to estimate income. Expense factors vary by lender, and no formula is universal. The file is reviewed on documented income under the applicable program, subject to lender guidelines.
Picture a contractor who grosses a healthy amount but writes off vehicles, tools and home-office costs until the tax return shows modest profit. On the tax-return route, that contractor looks small. On the deposit route, the same contractor can look stronger. The reverse can also happen. A contractor with few write-offs and a clean return may do fine on FHA and pay less in the process.
Here is how the paths compare for a house hack:
| Path | Occupancy | Income proof | Best fit |
|---|---|---|---|
| FHA, 2-4 units | You live in one unit | Two years of traditional income documentation | Clean returns, low cash |
| Bank statement, owner-occupied | You live in one unit | Twelve months of deposits | Heavy write-offs |
| DSCR purchase | You do not live there | Property rent | Your next rental |
Bank statement files cost more than agency-style loans, and they often want more down. On a primary residence purchase, select lenders in the network go up to 90% LTV, and the strongest files earn the top of that range. Weaker credit, thin reserves or a lumpy deposit history pull it lower. Loan sizes run roughly $125,000 to $3,500,000, and reserves commonly sit around six months of the housing payment. Everything here is a typical range, and every file is underwritten individually.
Compare the leverage. Lofty’s guide describes FHA’s low-down structure at 3.5%. Bank statement purchases at the top of the range work out to roughly 10% down. FHA is lighter on cash when your returns support it. The bank statement route exists for contractors whose returns do not. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
How the Second Unit’s Rent Counts
Rent from the unit you don’t live in can help you qualify, but it rarely carries the file alone. Lenders generally treat it as supplemental income. An appraiser estimates market rent for the units, and the lender counts a portion of the rented unit toward your qualifying income.
A few practical points matter here.
- The rent supports your income. It does not replace it. A contractor with weak documented income cannot usually lean on tenant rent to make up the gap.
- The rent figure usually comes from the appraiser’s estimate or a lease, depending on the program.
- Vacancy matters. Lenders discount the rent for it, and you should too.
A duplex gets an easier ride than bigger buildings. For three- and four-unit FHA purchases, lenders run an extra self-sufficiency test. They take the building’s net rent, reduced by a vacancy and maintenance haircut, and check that the full housing payment does not exceed it. Three- and four-unit files also carry added reserve requirements. Practitioner sources agree the test does not apply to duplexes. In expensive markets a fourplex can fail it, and a failed fourplex may only work as a non-owner-occupied DSCR purchase. Check the HUD handbook before you rely on any of this. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
That is the main reason a duplex is the cleanest first house hack for a 1099 contractor.
Why DSCR Can’t Finance the Duplex You Live In
Occupancy decides which rulebook applies, and that choice is not a technicality. DSCR loans are designed for non-owner-occupied investment properties. Because they are business-purpose investor loans, they are reviewed differently from a standard owner-occupied mortgage.
The federal line is drawn by actual use. The CFPB’s official interpretation of Regulation Z treats credit to acquire rental property that is not owner-occupied as business purpose, whatever the number of units. It also says an owner who expects to occupy the property more than 14 days in the coming year cannot treat it as non-owner-occupied under that rule. Owner-occupied rental property sits under separate comments, which you can read in the Cornell LII text of the supplement. The practical result is that a house-hack duplex is a consumer mortgage, with the standard consumer disclosure package (known as TRID). A non-owner-occupied rental purchase is business-purpose and exempt from TRID.
DSCR documents also ask you to certify that you do not live in the property and do not plan to. That certification can cover family members too. Signing it falsely is occupancy fraud, and no loan structure fixes that.
So labels do not help. Putting the duplex in an LLC does not change where you sleep. Calling it an investment does not either. Occupancy follows the facts, and the lender will treat you as an owner-occupant if you are one.
Where the General Rule Breaks
The rule is clean. The edge cases are where files get messy.
I’ll move in later, or my brother lives there. Neither works for a DSCR purchase. A promise to occupy at some point is occupancy intent, and a relative living there is covered by the family language in the certification. Treat both as owner-occupied purchases or as non-starters.
Under two years of self-employment. Tax-return programs generally want two years, with some flexibility if you did the same kind of work as an employee before going out on your own. Bank statement programs work from twelve months of deposits, so a shorter 1099 history is easier to document there. Flexibility varies by lender.
Three or four units. The self-sufficiency test can fail in high-priced markets. If it does, the building may only fit an investor loan with no occupancy.
A veteran contractor. Eligible veterans can buy up to four units with VA financing if they occupy one.
Short-term rental use on the second unit. Disclose the actual use. Short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income.
A mixed household. A W-2 spouse or co-borrower can strengthen the file, since their income is documented the ordinary way. Their credit and debts come into the file too, so it cuts both ways.
The Two-Step Plan: House Hack First, DSCR Next
The legitimate version of DSCR plus house hack is a sequence, not a single loan. You use owner-occupied financing on the duplex you live in. Later, you use DSCR financing on rentals where nobody in your household lives.
That is where DSCR earns its place. It qualifies primarily on property-level rental income covering the payment, subject to lender guidelines. Your personal returns stay out of later purchases, which matters for a contractor whose tax return undersells their cash flow. Lendmire arranges DSCR investor loans across 41 markets, including Washington, D.C., through select lenders in its wholesale network. Programs below a 1.00 coverage ratio exist through select lenders, though leverage and terms adjust.
Moving out of the duplex later is another route into the same plan. After you satisfy the occupancy period your owner-occupied loan requires, the building can become a rental. Refinancing it into a DSCR loan is then a separate transaction, with its own seasoning and eligibility rules that depend on the lender. Do not plan that refinance until you have confirmed what your original loan requires.
Funding the next down payment is its own question. Lendmire has covered whether a cash-out refinance can fund a down payment on another house and the tradeoffs in HELOC down payment vs cash purchase when you have a low first mortgage. Read those before you pull equity from the duplex.
For the bigger picture on how investor loans work, see the complete DSCR loans guide.
From Document Prep to Move-In
The sequence matters more than the calendar. Here is the order that keeps surprises to a minimum.
1. Decide occupancy. If you will live there, the file is owner-occupied. Settle this before anything else.
2. Pick the income route. Compare what your conventional personal-income paperwork shows with what your deposits show. A CPA can help you see the gap before you apply.
3. Gather documents. For FHA, that means standard personal-income documentation and business records. For a bank statement program, it means twelve months of statements with deposits that match your business story.
4. Get pre-approved. The lender reviews credit, income, reserves and the likely property type.
5. Make the offer. Keep the duplex’s rent potential in mind, since the appraiser will estimate it.
6. Appraisal. For two- to four-unit properties, the appraiser documents market rent for the units.
7. Close and move in. Occupancy rules start here. Follow your loan’s requirement on moving in and staying.
One more note on reserves. Contractors have slow seasons, and vacancy on the rented unit adds risk. Cash left after closing is not just a lender requirement. It is the cushion that keeps the building paid when income dips.
Which Path Fits You
Run through these questions in order.
- Does your conventional income documentation show strong net profit after write-offs? If yes, FHA is worth pricing first, since it asks for the least cash.
- Do heavy deductions shrink your reported income? If yes, a bank statement program may qualify you where returns would not. Expect more cash down and a higher cost.
- Is the building three or four units? If yes, test it against the self-sufficiency rule before you fall for it.
- Do you want to rent both units and live elsewhere? Then this is not a house hack. It is an investor purchase, and DSCR is the likely path.
- Do you need to keep personal income out of future files? Plan your later rentals on DSCR.
Honestly, the stronger play for many contractors might be the owner-occupied purchase now and the investor loan later. Investors chasing speed of portfolio growth could argue for skipping the duplex and going straight to rentals. The tradeoff is cash: owner-occupied financing asks for much less of it.
This article is general education, not legal or tax advice. Tax treatment can depend on how the funds are used and how the property is held; investors should keep clear records and speak with a qualified tax professional before relying on any deduction. Talk to an attorney or CPA about your own situation before choosing a structure.
Frequently Asked Questions
Can I use a DSCR loan to buy a duplex I’ll live in?
No. DSCR loans are business-purpose loans for properties you do not occupy, and the paperwork asks you to certify that. A primary-residence duplex needs an owner-occupied loan, such as FHA or a bank statement program. Use DSCR for the rental you buy next.
How much down payment does a 1099 contractor need?
It depends on the route. On a bank statement purchase of a primary residence, select lenders in Lendmire’s network go up to 90% LTV, which means roughly 10% down for the strongest files. Credit, reserves, deposits and loan size all move that number, and every file is underwritten individually. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
What if I’ve been self-employed less than two years?
Tax-return programs generally want two years of history, with some flexibility for prior work in the same field. Bank statement programs run on twelve months of deposits, so a shorter history can be easier to document there. How much flexibility you get depends on the lender and the program.
Does the other unit’s rent count toward qualifying?
Usually, partly. Lenders count a portion of the rent, based on the appraiser’s estimate or a lease, as supplemental income. It generally cannot qualify you on its own, so your documented income still has to hold up.
Can the duplex become a rental later?
Yes, once you have met the occupancy period your loan requires. After that, you can keep it as a rental or refinance it into a DSCR loan, subject to seasoning and lender guidelines. Confirm both with your lender before you plan the move.
Next Steps
Owner-occupied bank statement programs through Lendmire are available in 16 states, and eligibility review depends on lender guidelines and credit approval. This is not a commitment to lend.
About Lendmire
As a non-QM mortgage broker (NMLS# 2371349), Lendmire facilitates DSCR investor loans across 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income instead of personal income documentation, subject to lender guidelines, serving LLC-structured portfolios and self-employed borrowers who don’t fit conventional boxes. A two-time Scotsman Guide Top Mortgage Workplace (2025, 2026).
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. HUD, Handbooks library (Handbook 4000.1 index)
3. CFPB, Regulation Z official interpretation of section 1026.3
4. Cornell LII, Supplement I to 12 CFR Part 1026
This article is part of Lendmire’s self-employed mortgage guides — full qualification details, guidelines, and scenarios live on the program page.
Related reading: In an LLC 24-Month Bank Statement Loan vs Portfolio Loan · In an LLC Bank Statement Loan vs Profit and Loss Only Loan · How to Buy a House When You’ve Been Self-Employed Less Than Two Years
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.