
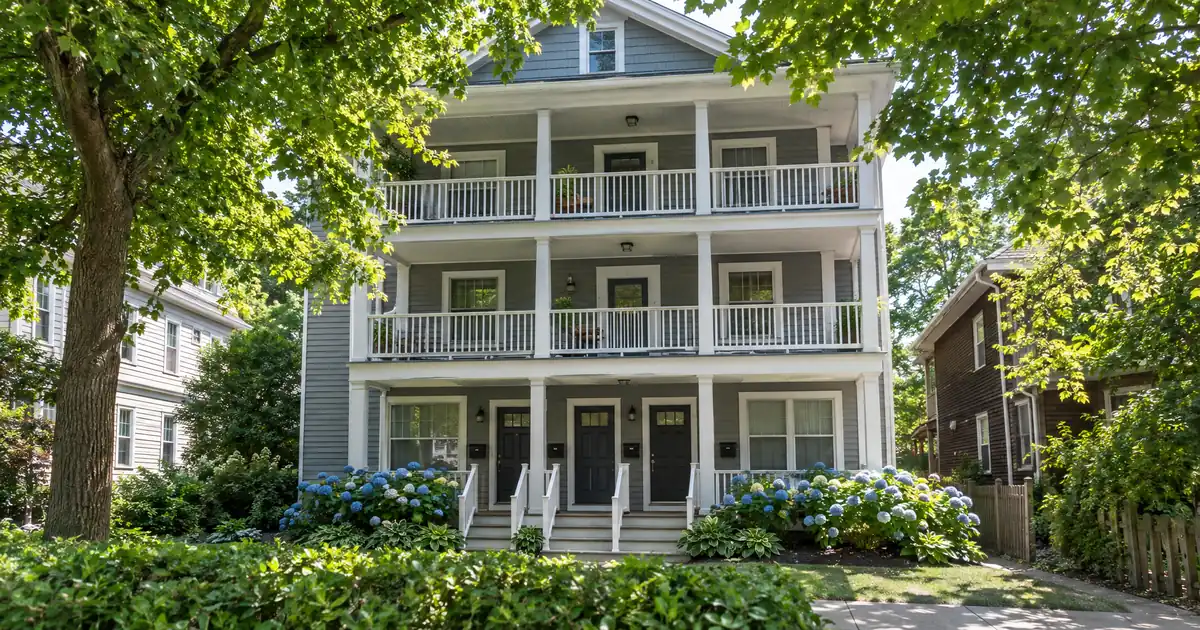
The Quick Read: On a 2-4 unit you plan to live in, the smaller down payment is for buyers who are short on cash but strong on income and credit. The larger one is for buyers who have the cash and still want a cushion left after closing. Putting 5% down is allowed on a two- to four-unit home you will occupy. Reaching 20% down removes mortgage insurance, but only helps if it does not drain the savings the lender also wants to see. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Neither choice is “smarter” in general. It comes down to your cash, your income, and how much of the building’s rent a lender will count.
Key Takeaways
- A two- to four-unit principal residence can be bought with as little as 5% down on a conventional loan, subject to lender guidelines and full file review.
- Mortgage insurance applies above 80% loan-to-value. It is not permanent: it can be cancelled and it ends on a schedule.
- A bigger down payment draws from the same pool of savings that covers reserves, so cash left after closing matters as much as cash to close.
- Rent from the other units can help you qualify, but rent from the unit you live in generally cannot.
- The right answer usually sits between the extremes. Many buyers land at 10% or 15%.
Conventional payment estimate
The starting figures are an example price at the first-time buyer’s minimum down payment. Replace them with yours.
Editable benchmark: 7.32% as of October 22, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not a conventional loan quote.
Estimate seeded at the low end of Fannie Mae’s published range (0.58%–1.86% a year); the insurer prices the actual premium on the score and the leverage. Applies only above 80% loan-to-value.
Illustrative starting assumptions: a $350,000 price, the first-time buyer’s minimum down payment, a thirty-year term at the current Freddie Mac benchmark, mortgage insurance at the low end of Fannie Mae’s published range, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conventional benchmark, a market reference and not a conventional loan quote; your rate is set by the lender at lock. The mortgage insurance figure is an editable estimate seeded from Fannie Mae’s published typical range, not a premium quote; the insurer prices the actual premium, and the cancellation month assumes scheduled payments with no extra principal and no change in value. Taxes, insurance and dues are editable estimates; closing costs are not included. Conforming loan limits apply by county. Licensed in sixteen states for consumer mortgages.
Side-by-Side
Here is how the two paths compare on a principal-residence purchase of a two- to four-unit home. “Smaller” means about 5% down. “Larger” means 20% or more. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
| Factor | Smaller (about 5% down) | Larger (20%+ down) |
|---|---|---|
| Leverage (LTV) | Up to 95% | 80% or less |
| Mortgage insurance | Required above 80% LTV | None at 80% or less |
| Credit floor | 620 wholesale floor; stricter tiers can apply | 620 wholesale floor; more room at lower LTV |
| Cash left after closing | Higher | Lower |
| Reserves | Easier to meet | Can become the limit |
| Occupancy | You live in one unit | You live in one unit |
| Documentation | Standard file; fewer large deposits to source | Standard file; more funds to document |
Two notes on that table. First, the credit floor is where the wholesale programs start. The automated finding governs most files, with a total debt-to-income ceiling of 50%. Second, occupancy decides leverage. If you do not live in the building, a two- to four-unit purchase tops out at 75% LTV, so a low down payment is off the table.
Why Down Payment Isn’t Just One Number
Most buyers treat the down payment as a single decision. In practice it moves four things at once.
Loan size. Your down payment sets the loan-to-value ratio, or LTV: the loan amount divided by the lesser of price or appraised value. Put 5% down and your LTV is 95%. Put 20% down and it is 80%. Terms depend on the lender’s guidelines, the property type, the leverage, and a full review of the credit profile.
Mortgage insurance. Above 80% LTV, mortgage insurance is required. The coverage steps up as the LTV band rises. Published typical annual premiums run from 0.58% to 1.86% of the balance. That is a range, not a quote. Your own figure depends on your file. The exact numbers vary by lender and program and follow a full review of property, leverage, and credit.
Cash left over. Every dollar you put into the down payment is a dollar you cannot use for repairs, a vacant unit, or a cushion.
How the lender sees you. At lower leverage, a lender sees less risk. That can help a thinner file. It can also matter if your credit score sits near the floor.
You can read about the full range of conventional loan programs Lendmire arranges. For this article, the question is how those pieces behave on a building with more than one unit.
When the Smaller Down Payment Is the Better Fit
A smaller down payment fits when cash is your tightest resource and income is not.
You want to keep a real cushion. A multi-unit home has more moving parts than a single-family house. Roofs, boilers, and turnover between tenants all cost money. A buyer who puts 5% down keeps more savings in the bank for those surprises. Final terms depend on the lender’s guidelines, the property type, and the borrower’s complete credit picture.
Reserves are the binding limit. Fannie Mae’s automated system generally asks for six months of reserves on a two- to four-unit principal residence. A one-unit principal residence has no such minimum. Reserves are counted in months of the property’s full housing payment. You can read the rule in the Fannie Mae Selling Guide on minimum reserves. The automated system can also ask for more based on the file as a whole.
That matters because the same savings do both jobs. Picture a buyer with a fixed pile of cash. If most of it goes to a 20% down payment, there may not be enough left to meet reserves. The file that looked strong at 5% down can stall at 20%. Each figure is subject to lender guidelines and a complete review of property type, leverage, and credit.
The other units can carry part of the load. For a purchase, a lender may count a reduced portion of the other units’ rent toward your income. The lender typically works from the appraiser’s market rent or the signed leases. The rent from the unit you occupy generally cannot be counted. That is one reason a 2-4 unit can qualify more easily than the price tag suggests, even at higher leverage.
You expect the insurance to be temporary. Mortgage insurance is a cost with an exit. The Homeowners Protection Act says you can ask to cancel it when your balance is scheduled to reach 80% of the home’s original value. The servicer must end it automatically at a scheduled 78%. The CFPB explains the cancellation conditions: a written request, a good payment history, no junior liens, and no decline in value. So a smaller down payment is a cost you carry for a period, not for the life of the loan.
You’d rather buy now than wait. Some buyers could reach 20% with another stretch of saving. That is a fair plan. But waiting has its own cost, and a smaller down payment lets you start building equity sooner. This is a genuine toss-up, and it depends on your timeline.
The catch with going small
A smaller down payment has real downsides:
- A larger loan balance means a larger monthly housing payment.
- Mortgage insurance adds to that payment and raises your debt-to-income ratio.
- A higher ratio leaves less room under the 50% automated ceiling.
- You start with less equity. If values dip, you have less of a buffer.
- A weaker credit score can raise the cost and narrow your options at higher leverage.
If the numbers feel tight at 5% down, that is a signal worth respecting. Across the wholesale programs we place files with, a file that barely clears the ratios at maximum leverage has little room for a surprise. Leverage, reserves, and pricing vary by lender and program; the final terms follow the full file review.
When the Larger Down Payment Is the Better Fit
A larger down payment fits when you have cash to spare and want a lower monthly obligation.
You want to skip mortgage insurance. At 80% LTV or less, the mortgage insurance requirement does not apply. That removes a line from your monthly budget for good. It also removes the paperwork of cancelling it later. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Your ratios are tight. A smaller loan means a smaller payment. That lowers your debt-to-income ratio, which can be the difference between a file that fits and one that doesn’t. If your other debts are heavy, extra down payment may do more for your file than a higher income would.
Your credit score is near the floor. The wholesale programs start at a 620 decision score. A score near that line gets more scrutiny at higher leverage. Lower leverage gives a lender more comfort and can widen your options. Some lenders also set stricter floors than the baseline, so a larger down payment can keep more doors open.
You are worried about the appraisal. If the home appraises below your contract price, the loan is based on the lower value. You then need more cash to stay under the leverage limit. A buyer who already planned a larger down payment has room to absorb a shortfall.
You have reserves to spare. This is the key test. A larger down payment makes sense only if you still meet reserves after closing, with a cushion beyond that. If you do, the extra equity is a quiet strength.
The catch with going big
- The cash is tied up in the building. You cannot spend it without refinancing or borrowing against the home.
- You may fall short of reserves, which can sink an otherwise approvable file.
- You lose flexibility for repairs, vacancies, or a second move.
- The money could do more elsewhere, such as paying down higher-cost debt or covering renovations.
Here is a picture of the trade-off. Say you have a down payment of 20% available, but using it all leaves almost nothing in the bank. A buyer in that spot may do better at 10% down with a healthy cushion. The mortgage insurance is a real cost, but an empty account on a four-unit building is a bigger risk. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
What About Rent From the Other Units?
Rental income is where a 2-4 unit differs most from a single-family home, and it ties directly to the down payment choice.
Rent from the unit you occupy generally cannot be used to qualify. The Selling Guide’s rental income topic lays this out. Rent from the other units can help, but a lender counts only part of it. The appraiser reports market rent, and the lender weighs it against any leases.
Here is how that plays out:
- Smaller down payment: The payment is higher, so your ratios are tighter. Credit for the other units’ rent may be what makes the file work.
- Larger down payment: The payment is lower, so you may not need much rental credit. A file that is strong on income alone has fewer moving parts.
Think of rental credit as a tool, not a promise. A lender reviews it as part of the full file. If your plan depends on counting every dollar of future rent, build in room for a vacancy or a lower appraisal.
How Occupancy and Loan Size Change the Answer
Two edge cases can change the whole comparison.
Occupancy. Everything above assumes you will live in one of the units. Occupancy decides leverage. A two- to four-unit purchase you will not live in is capped at 75% LTV. That means a larger down payment is required, not optional. Rental and investment financing is a separate lane from this article. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Loan size. The FHFA sets conforming loan limits by unit count, and the limit rises with each added unit. A higher-priced building may exceed the limit for its unit count. At that point it becomes a jumbo loan, which follows different rules. The FHFA conforming loan limit announcement explains how the limits are set. Your county’s limit depends on where the property sits.
Fannie Mae’s Eligibility Matrix is the table that sets maximum leverage by unit count and occupancy. It shows that a two- to four-unit principal residence can go to 95% on a purchase. It also shows different caps for a cash-out refinance on the same property type, which is a separate transaction from a purchase. Freddie Mac has also widened its own leverage for certain two- to four-unit loans, so the two agencies now sit closer together than they once did. Which one applies to your file depends on the lender’s channel and the automated finding.
Some buyers also hear that a 2-4 unit needs 20% down. That belief is out of date for owner-occupants. The 20% figure is the line where mortgage insurance falls away. It is not the line for qualifying.
A Simple Way to Decide
Work backward from your budget instead of forward from a target percentage.
1. Start with the monthly housing cost you can carry after counting a reduced share of the other units’ rent.
2. Add up all your cash. Include the down payment, closing costs, and reserves.
3. Protect the reserves first. Subtract the reserves your lender requires, plus a cushion for repairs and a vacancy.
4. Spend what is left on the down payment. That is your ceiling, not your target.
5. Check the middle. If 5% feels too thin and 20% empties the account, look at the bands in between. Mortgage insurance coverage steps by LTV band, so each tier changes the cost.
Run this with two or three down payment levels, and compare them on the Loan Estimate your broker provides. The full terms matter more than any single line.
Which buyer are you?
- The house-hacker with modest savings. Lean smaller. Keep the cash for repairs and reserves, and plan to cancel the insurance as the balance falls.
- The buyer with strong savings and a tight payment. Lean larger, as long as reserves stay intact.
- The buyer with a score near the floor. Lean larger if you can. A bigger down payment can offset a thinner credit profile.
- The buyer with a gift in play. Rules differ on how gift funds count. Lendmire’s piece Can a Gift Cover the Down Payment on a Conventional 2-4 Unit? walks through it.
Key Terms Defined
LTV (loan-to-value): The loan amount divided by the lesser of the purchase price or appraised value.
Mortgage insurance: Coverage the borrower pays for on a conventional loan above 80% LTV. It protects the lender, not you.
Reserves: Liquid savings left after closing, measured in months of the full housing payment.
Principal residence: The home you live in as your main address.
Debt-to-income ratio: Your monthly debts divided by your monthly income.
The Balanced Verdict
Neither option wins on its own. The smaller down payment keeps your cash flexible and gets you into the building sooner. The larger one lowers your monthly cost and removes mortgage insurance. Each has a trap. Going small can strain your ratios. Going big can strain your reserves.
For many buyers of a 2-4 unit, the best answer is neither extreme. It is the amount that leaves your reserves whole, keeps your ratios comfortable, and still lets you sleep when a tenant moves out.
Every figure here is subject to lender guidelines and full file review. Nothing here is a commitment to lend.
Next Step
If you are buying a home and want to see whether a conventional loan fits your file, Lendmire can help you compare the options and what each one asks of the file.
Frequently Asked Questions
Can I really buy a duplex, triplex, or fourplex with 5% down?
Yes, if you will live in one of the units and your file meets the lender’s guidelines. A two- to four-unit principal residence can go to 95% LTV on a purchase. Reserves, credit, and ratios still have to work, so the low down payment is only the starting point.
Do I need 20% down to avoid paying mortgage insurance?
You need to reach 80% LTV or lower to skip it. That is a 20% down payment on a purchase. Below that line, mortgage insurance applies. It is not a qualifying rule, just the point where the insurance requirement stops.
Does mortgage insurance last for the life of the loan?
Usually not. You can ask in writing to cancel it when the balance is scheduled to reach 80% of the original value, if you meet the conditions. A decline in the home’s value can block cancellation.
Why can a larger down payment make a file harder to approve?
Because the savings are shared. A 2-4 unit principal residence generally requires reserves on top of the down payment and closing costs. If a bigger down payment pulls your cash below that mark, the file can fail on reserves even though the loan is smaller.
Will the rent from my building help me qualify?
Partly. Rent from the other units can count in reduced form, based on the appraiser’s market rent or signed leases. Rent from the unit you live in generally cannot. A lender reviews all of this as part of the full file.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
As a mortgage broker (NMLS# 2371349), Lendmire helps homeowners and home buyers in 16 states with FHA, VA, conventional and jumbo purchase and refinance loans arranged through wholesale lenders. Lendmire is never the lender; program terms are set by the lender and the agency guidelines. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Fannie Mae Selling Guide: Minimum Reserve Requirements
2. CFPB: When can I remove PMI from my loan?
3. Fannie Mae Selling Guide: Rental Income
4. FHFA conforming loan limit values
5. Fannie Mae Eligibility Matrix
This article is part of Lendmire’s conventional loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Conventional Loan Down Payment Rules for a First-Time Buyer on a 2–4 Unit · Conventional Loan Requirements for a Condo With a Low Down Payment · Can a Repeat Buyer Use Homeready on a 2-4 Unit Conventional Loan?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.