
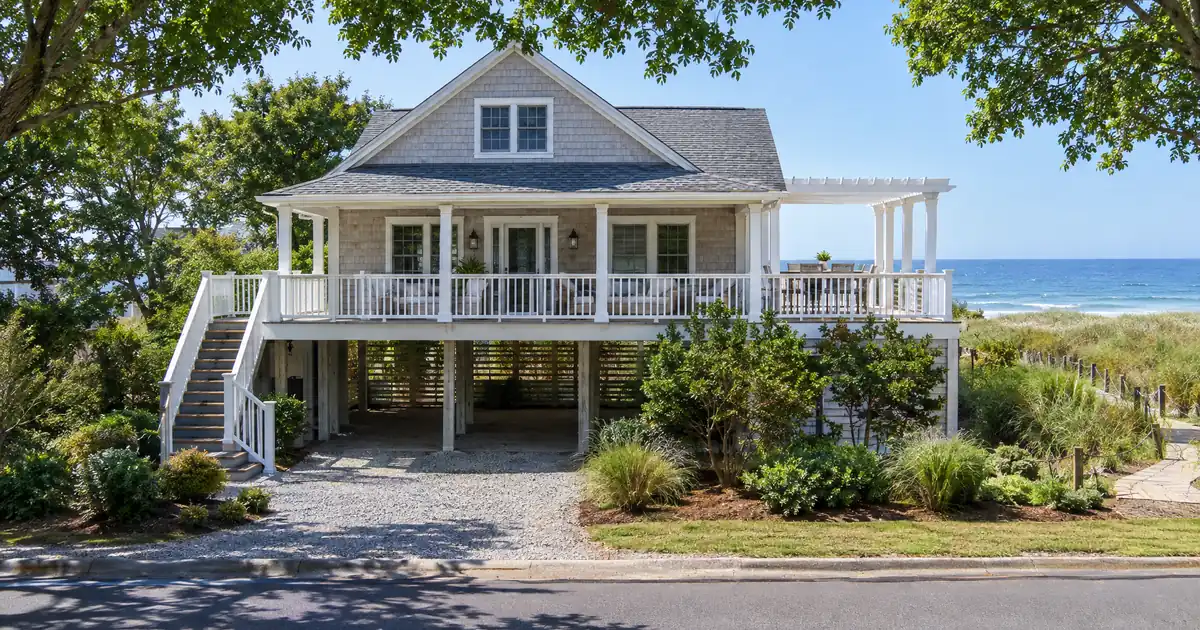
The Quick Read: A DSCR loan tests the property’s rental income against its payment, while a bank statement loan tests the borrower’s deposits, so the right choice on a Bald Head Island house depends first on whether you will live in it or rent it out as an investment.
- A pure rental usually points to the DSCR side, because the loan is reviewed primarily on property-level rental income covering the payment, subject to lender guidelines.
- A house you will use yourself usually points to a bank statement loan, which is reviewed on documented income under the applicable program, subject to lender guidelines.
- Short-term rental income on a car-free island is harder to document than a lease, and that evidence often decides which path holds up.
- Personal debts count on a bank statement file. They do not count against the borrower on a DSCR file.
- Many self-employed investors end up using both: one for the home they live in, one for the rental.
The Honest Answer
Neither loan is better in the abstract. They answer different questions.
What your deposits qualify you for.
Alt-doc programs read 12 months of business or personal bank deposits instead of tax returns. Enter your average monthly deposits and see the income a lender would credit you.
The expense factor is set by the lender from your business type and profit-and-loss statement; it is not a number you choose. This widget quotes no rate and no payment.
Program parameters shown update from Lendmire’s centralized guideline source.
Estimate
Illustrative estimate only — not a quote, Loan Estimate, approval, or commitment to lend. Deposit average, expense factor, and housing ratio are editable assumptions; the expense factor a lender applies is set from your business type and documentation. No interest rate or monthly payment is quoted here. Purchase capacity is a simplified illustration and does not account for taxes, insurance, HOA dues, or other debts. Alt-doc income documentation is available on consumer mortgages in the states where Lendmire is licensed for consumer lending; actual terms vary by lender, borrower, and property.
A DSCR loan is for the investor whose property can carry itself. The file turns on the rent, the full housing payment, and the borrower’s credit and reserves. Personal tax returns and personal debt-to-income do not drive it.
A bank statement loan is for the self-employed borrower whose real cash flow is stronger than the tax return shows. The file turns on twelve months of deposits, the expense factor the lender applies, and the debts the borrower already carries.
Across the wholesale network, the split is simple. If the house is an investment and the rent can be supported, DSCR is usually the cleaner fit. If the buyer will use the house personally, or the rent is thin and the deposits are strong, a bank statement loan is usually the better one.
Both are non-QM products. HousingWire’s non-QM guide cites Polygon Research estimates that bank statement loans made up about 34% of non-QM volume and DSCR loans about 29%, so neither is a niche product.
Side-by-Side
| Factor | DSCR Loan | Bank Statement Loan |
|---|---|---|
| What is tested | The property’s rent vs. its payment | The borrower’s deposit history |
| Core documents | Appraisal, rent evidence, assets, entity papers | 12 months of business or personal statements |
| Occupancy | Investment property only | Primary, second home, or investment |
| Personal DTI | Generally not part of the review | Part of the review |
| Entity vesting | Commonly an LLC, per program terms | Usually individual borrowers |
| Reserves | Commonly required, amount varies | Around 6 months of housing payment |
| Scaling | Each property stands on its own rent | Limited by the borrower’s debt load |
| Main risk | Weak or unproven rent evidence | Heavy debts or lumpy deposits |
The DSCR column reflects published industry norms, which vary by lender. The bank statement column reflects select wholesale-network guidelines. Entity vesting on either side depends on lender program eligibility, and every file is underwritten individually.
Occupancy Decides It First
Occupancy settles most of these files before anyone runs a number. A DSCR loan is built for non-owner-occupied investment property. A bank statement loan can also fit a primary residence or a second home.
Picture three buyers looking at the same cottage.
The first plans to rent it full time and never stay there. That is an investment, and DSCR is on the table.
The second plans to stay there several weeks a year and rent it the rest of the time. Lenders read the occupancy declaration closely on a file like that. A house the buyer uses personally often reads as a second home, and a second home usually points away from DSCR.
The third will live there. That is a primary residence, and a bank statement loan or another owner-occupied program is the lane.
The middle case is the one that trips up buyers. Declare occupancy as it will actually be, because the lender reviews it, and a mismatch between the declaration and the facts can break a file.
When DSCR Is the Better Fit
DSCR wins when the house is a true rental and the rent can be supported on paper. The ratio is the monthly rent divided by the full monthly housing obligation: principal, interest, taxes, insurance, and any HOA dues. A ratio of 1.00x means rent covers the payment. Most standard programs are built around that level, but select lenders in the network offer programs below 1.00 coverage, with leverage and terms adjusting.
Four situations favor DSCR.
- Heavy personal debt. Because the loan does not weigh personal debt-to-income, a borrower with a large mortgage on a primary home can still add a rental.
- Portfolio growth. Each property is reviewed on its own rent, so buying a third or fourth rental does not depend on how much debt sits on the borrower’s personal statement.
- Entity ownership. Investors who hold title in an LLC typically find DSCR the natural fit, subject to lender program eligibility.
- Documented rent history. A property that already has platform booking history or a lease gives the file strong evidence.
The complete DSCR loans guide walks through ratios, leverage and documents in more detail.
One point matters here. DSCR does not mean no documents. It means no personal-income documents. The file still needs an appraisal, credit, proof of assets and reserves, and entity papers when an LLC holds title. The down payment and reserves still come from statements that have to be sourced.
When a Bank Statement Loan Is the Better Fit
A bank statement loan wins when the borrower is strong and the property is not yet proven. It also wins when the buyer will use the house personally.
Four situations favor it.
- Self-employed buyer with heavy write-offs. The tax return understates cash flow, but twelve months of business or personal deposits tell the real story. The lender averages eligible deposits and applies an expense factor that varies by program.
- A second home you will use. A bank statement loan is available on owner-occupied files. A DSCR loan is not.
- Thin or unproven rent. If a new listing has no booking history and the rent projection is uncertain, the borrower’s deposits can carry the file instead.
- Larger loan sizes. Across the network, bank statement loans run roughly from $125,000 to $3,500,000, subject to lender guidelines.
On leverage, the figures depend on the transaction. On a primary residence purchase or rate-term refinance, select lenders go up to 90% LTV on the bank statement side. That figure does not describe a second home or a rental. On an owner-occupied cash-out, a primary residence goes up to 80% LTV with a fixed expense ratio, or 75% with an accountant-prepared ratio. A second home cash-out goes up to 75% LTV. An investment property cash-out tops out around 75% LTV. Investment purchase leverage on bank statement documentation varies by lender, and investor-focused leverage guidance belongs on the DSCR side.
Two cautions apply. Lenders strip out inconsistent deposits such as refunds, transfers between accounts, and one-time asset sales. Then personal debts count against the borrower, because debt-to-income is part of the review. Commingled accounts and lumpy seasonal deposits are the usual friction points. Clean, separated statements keep that part of the file short.
An asset-depletion alternative also exists. It qualifies a borrower from liquid assets and runs to about 80% LTV on a primary residence. Terms depend on the lender’s guidelines, the property type, the leverage, and a full review of the credit profile.
What Bald Head Island Changes
Bald Head Island is a car-free barrier island. VisitNC describes it as reachable only by passenger ferry or private boat, with cars prohibited. The ferry from Southport takes about 20 minutes, and some rentals include a golf cart. The island matters because of what it does to the file.
Rent evidence is the hard part. A long-term lease is easy to document. A vacation rental is not. For an existing short-term rental, platform booking history is the usual evidence. For a purchase, lenders often lean on a market projection from a rental-data service. Some lenders will fall back on a long-term-rent appraisal as the conservative number. Which method applies depends on the lender’s guidelines. DSCR lenders also tend to treat short-term income as more variable than lease income, so eligibility can be tighter.
The appraisal can be thin. The standard one-unit rent schedule is Form 1007. One appraisal firm argues that the form cannot capture short-term rental income and that appraisers use a narrative projected-income analysis instead. That is one firm’s view, and lenders differ on what they accept. On a small, car-free island, comparable sales and comparable rentals may also be scarce. That can make the rent estimate harder to support, so ask early how the lender will handle it. Appraisal reconsideration is a routine step when comps come in light, and a packet with recent island sales and condition adjustments gives the underwriter more to work with.
Insurance and flood sit inside the payment. On a coastal barrier island, insurance and flood coverage feed the denominator of the ratio. A rent projection that clears the ratio on an old quote can miss on a new one, so get a current, complete quote in before the file goes to review.
Local rules are a separate check. Short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income. Some programs also want the short-term use to be legally permitted and common for the area.
One Property, Both Paths
Consider a self-employed owner of a small consulting firm. The tax returns show heavy write-offs, but business deposits are steady. The owner is eyeing a cottage on the island that has never been rented and will be used for a few weeks each year.
Path one: DSCR. The lender needs a rent figure. With no booking history, the file relies on a projection and an appraisal narrative. If the projected rent covers the full housing obligation with room to spare, the file can work. If it lands near break-even, select lenders in the network offer programs below 1.00 coverage, but leverage and terms adjust. The bigger issue is occupancy. If the owner stays in the house for personal use, the lender may read it as a second home, and DSCR may not apply.
Path two: bank statement. The file runs on twelve months of statements, the expense factor, and the owner’s existing debts. If the cottage is a second home, the loan is an owner-occupied consumer file. Leverage on a second-home purchase varies by lender. The file does not depend on how well the rent is documented, but it does depend on the owner’s other debts staying manageable.
The result. If the owner treats the cottage as a pure rental, DSCR is likely the cleaner path, provided the rent evidence holds. If the owner wants personal use, the bank statement path is the one that matches the facts. The fail points differ. DSCR fails on weak rent evidence or an occupancy mismatch. A bank statement loan fails on lumpy deposits or a debt load that is already heavy.
Using Both, or Moving From One to the Other
Many investors do not choose one. They use a bank statement loan for the home they live in and DSCR loans for rentals. Each bank statement loan adds debt that counts against the next file, while DSCR loans are reviewed property by property. A home business magazine article makes the same point about scaling.
A second sequence also works. A buyer can start on a bank statement loan while a new property has no rent history, then move to DSCR once leases or booking history exist. That route costs a second closing, and the refinance has its own seasoning and reserve review, so it is a real tradeoff, not a free option. Lendmire’s comparison of DSCR and bank statement for a luxury rental explores the high-balance version of this decision.
Which Disclosure Regime Applies
Occupancy also decides the paperwork regime. An owner-occupied file, whether a primary residence or a second home, is a consumer mortgage, and TRID disclosures apply. A DSCR loan on a non-owner-occupied rental, including a short-term rental, is a business-purpose loan. The CFPB’s Truth in Lending compilation treats credit to acquire non-owner-occupied rental property as business-purpose credit. The Federal Register’s ability-to-repay rule says investment-purpose loans fall outside its ability-to-repay provisions.
Business-purpose does not mean unregulated, and the classification turns on the loan’s stated purpose and the borrower’s real occupancy intent. A home the borrower also uses personally is the grey zone. Lendmire’s consumer licensing for owner-occupied mortgages covers 16 states, and its DSCR investor programs run on a separate business-purpose platform.
Key Terms Defined
DSCR (debt service coverage ratio): The property’s monthly rent divided by its full monthly housing payment.
Bank statement loan: A mortgage that qualifies a borrower on average deposits over twelve months instead of tax-return income.
Expense factor: The percentage a lender subtracts from business deposits to estimate what is left as personal income.
Non-QM: A mortgage that does not fit the standard agency documentation box and is reviewed under investor guidelines.
Occupancy: How the borrower will use the home: as a primary residence, a second home, or an investment.
Reserves: Liquid assets the borrower holds after closing, commonly measured in months of housing payment.
Vesting: The name on title, either an individual or an entity such as an LLC.
The Verdict
Choose DSCR when the house is a true investment, the rent can be documented, and you want each property judged on its own income. Choose a bank statement loan when you will use the house, when your deposits are stronger than the property’s rent, or when the rent has no history yet.
Use both when you are building a portfolio and also own a home you live in. The deciding questions are the same on every file. How will you occupy the property, how will the rent be evidenced, and how much personal debt already sits on your statement?
Tax treatment varies; consult a qualified professional.
Frequently Asked Questions
Can a bank statement loan be used on a rental property?
Yes, in some programs. On an investment property cash-out, select lenders go up to about 75% LTV. Investment purchase leverage on bank statement documentation varies by lender. Personal debts still count in the review.
Does a DSCR loan work for a short-term rental with no booking history?
It can, but the file leans on a market projection and the appraisal narrative instead of platform history. Some lenders count only a portion of projected revenue, and some fall back to a long-term-rent figure. The method depends on the lender’s guidelines.
Can an LLC borrow under either loan?
DSCR loans commonly close in an LLC, subject to lender program eligibility. Bank statement loans are usually structured for individual borrowers, so entity vesting there depends on the specific program.
What if the DSCR ratio comes in below 1.00?
Select lenders in the network offer programs below 1.00 coverage, but leverage and terms adjust. A larger down payment, stronger credit, or more reserves can help the file. Outcomes depend on lender guidelines and property review.
Can I buy with one loan and refinance into the other later?
Yes, though it adds a second closing and a second review. A buyer may start on a bank statement loan while a property has no rent history, then refinance into DSCR once leases or booking history exist.
Next Step
If you are self-employed and want to see how the numbers work, Lendmire can help you compare bank statement loan options based on your deposits, the property, credit profile, leverage, and your goals. Call 828-256-2183 or request a quote. Bald Head Island offers few comparable sales and its short-term rental evidence is thin, so the choice between these two loans rests on how well the property’s income can be proven.
About Lendmire
As a mortgage broker (NMLS# 2371349), Lendmire helps self-employed and high-net-worth borrowers in 16 states qualify on bank statements, a profit-and-loss statement, 1099s or liquid assets instead of tax returns, through wholesale lenders. Lendmire is never the lender; program terms are set by the lender and its guidelines. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. HousingWire non-QM loans guide
3. ClassValuation: Form 1007 and short-term rentals
5. CFPB Truth in Lending Act compilation
6. Federal Register: Ability-to-Repay and Qualified Mortgage Standards
This article is part of Lendmire’s bank statement loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR vs Bank Statement Loan for a Galena Rental Investor · DSCR vs Bank Statement Loan for a Rental in a Low-Rent Market · DSCR Loan vs. Bank Statement Loan for a St. Petersburg Landlord
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.