
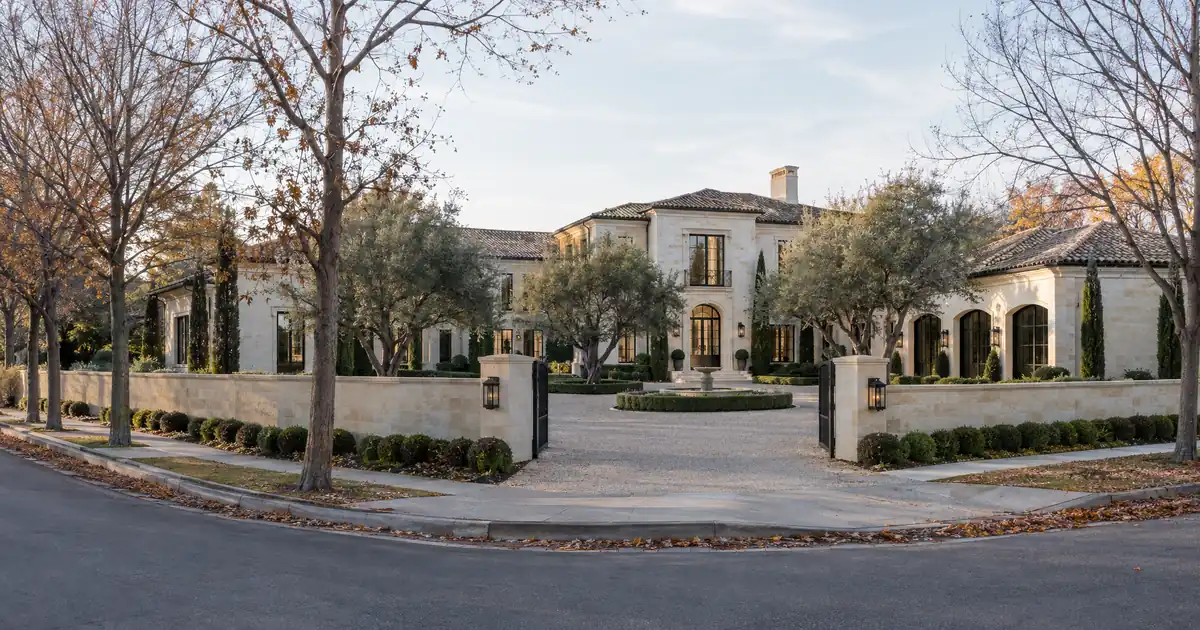
The Quick Read: You qualify by showing twelve or twenty-four months of consecutive bank statements whose eligible deposits, after an expense ratio, support the loan at a debt-to-income ratio up to 50%, and then by showing the lender that the golf community’s HOA, club membership and dues are documented and fit inside the full monthly housing cost. Everything below comes from placing these files through a wholesale network. Every figure is a typical ceiling through select wholesale programs, subject to full underwriting.
- Income: eligible deposits, minus an expense ratio, divided by the number of statement months. Your traditional personal-income documentation is not the yardstick.
- Credit and cash: a 660 credit floor on the portfolio non-QM program, with reserves of 3, 6 or 9 months depending on loan size.
- Leverage: on a primary residence purchase, 90% up to $1,000,000, stepping down as the loan grows. Second homes and investment property run lower at most sizes, and the gap widens on larger loans (see the table below).
- The golf layer: club dues, HOA budgets and assessments get counted and documented before the lender signs off.
- Above $4,000,000: every file is reviewed case by case before submission.
Key Terms Defined
Bank statement loan: a mortgage that is reviewed around deposit history instead of traditional personal-income documentation, so a self-employed borrower’s write-offs don’t shrink the income the lender sees.
Non-QM: short for non-qualified mortgage, meaning a loan that follows its own documented underwriting rules instead of the standard agency template.
Expense ratio: the share of business deposits the lender assumes went to overhead, so only the remainder counts as your income.
Debt-to-income ratio (DTI): your total monthly debts, including the new housing cost, divided by your qualifying monthly income.
Reserves: liquid cash left over after closing, measured in months of housing payments.
Equity membership: a club membership you own and can usually sell or transfer, often with a refund or transfer process attached.
Warrantable condo: a condo project that meets standard eligibility tests for owner-occupancy mix, finances and litigation. A non-warrantable project fails one or more of them.
How Does the Lender Turn Deposits Into Income?
The lender totals your eligible deposits across the statement window, subtracts an expense ratio if the account is a business account, and divides by the number of months. That monthly figure is your qualifying income. Then it gets tested against the new housing cost plus your other debts.
Step by step, here is how it runs.
1. Choose the window. Programs use 12 or 24 consecutive months of personal or business statements. A 12-month window favors income that has recently climbed. A 24-month window smooths out a lumpy year. Statements must be consecutive and complete, and a transaction history printout never substitutes for the statements themselves.
2. Screen the deposits. Transfers between your own accounts, refunds and loan proceeds get stripped out. Large unexplained credits usually need a letter of explanation. One exception helps you: when you move money from your own business into your personal account, those transfers count in full.
3. Apply the expense ratio. Business statements need at least 25% ownership on your part. The ratio depends on the business, and the table below shows the fixed options.
4. Test the result. The qualifying income goes against the full housing cost and your other debts. DTI can run to 50% on these programs.
Here is the part that surprises people. This is still full underwriting. The federal ability-to-repay compliance guide says a lender must make a good-faith determination of repayment ability, and it lists the factors to consider without requiring any one underwriting model. Information relied on has to be verified with reasonably reliable third-party records, and bank statements are those records. Nobody is waving you through.
Which Expense Ratio Applies to You?
The expense ratio is the single biggest lever on your qualifying income, and it follows how your business is built. Across the wholesale network, these are the fixed options.
| Business profile | Fixed expense ratio |
|---|---|
| Service business, no employees | 20% |
| 1 to 5 employees | 40% |
| 6+ employees, or any product business | 50% |
| Accountant-provided ratio | Set by the preparer’s letter |
Picture two founders with identical deposits. One runs a solo consulting practice, so 80 cents of every deposited dollar counts as income. The other sells physical product with a large team, so 50 cents does. Same bank balance, very different borrowing power.
If your real overhead runs lower than the fixed ratio, an accountant-provided ratio may fix that. Programs also offer a profit-and-loss path with an 80% LTV ceiling. Personal statements work too when they show a clear pattern of business income and you want to skip the expense ratio math. Personal-account transfers from your own business count at 100%. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
What Changes Because It’s a Golf Community?
Golf community homes add a second layer to the file: the lender qualifies you, then reviews the property’s association and club structure. The income side works exactly as above. The property side is where these files stall, so it deserves a plain walkthrough.
Is the club mandatory or optional? This is the first question to settle before you write an offer. In some communities, HOA members are automatically club members, and in others membership is a voluntary opt-in. Some clubs bundle golf into the association dues. A golf community buying guide advises getting the structure in writing, including the initiation fee, dues, minimums and what happens to the membership on sale. The model decides almost everything that follows.
How do the dues count? Mandatory club dues belong in the monthly housing expense and in your DTI. Optional dues are a judgment call. Many lenders leave them out unless the contract requires the membership to transfer or you already pay them. Treat that as the general pattern, not a promise. Each lender in the network applies its own reading, so confirm it before submission.
What documents will you need? Expect to pull these from the seller, the HOA or the club:
- the HOA budget, reserve information and delinquency data
- the dues schedule and any food-and-beverage minimums
- assessment history and any pending special assessments
- proof of whether membership transfers with the home, plus any initiation or capital contribution due at closing
Are there stacked assessments? In some communities a master HOA, a club fee and an infrastructure district assessment are billed separately, and none are optional once you own. Add them all up before you run DTI.
Is it a condo, villa or townhome? Attached golf homes draw extra review of association finances, owner-occupancy mix, litigation and special assessments. Through select wholesale programs, ceilings run to 85% on a purchase of a warrantable condo and 80% on a non-warrantable one, inside the size and occupancy ladder below.
What about the appraisal? A club membership bundled into the sale can muddy comparable sales. Ask the appraiser early whether comps with and without membership exist.
One practitioner pattern worth knowing: files stall less on the borrower’s income than on late-surfacing paperwork. A special assessment or a transfer fee nobody mentioned until late in the process changes DTI and sometimes the whole structure. Request the club and HOA package before you submit anything.
How Much Can You Borrow on a Golf Home?
Leverage steps down as the loan gets larger, and it drops again by occupancy. The table shows purchase ceilings through select wholesale programs, subject to full underwriting. Credit requirements rise as leverage rises, and higher tiers want 720 or better.
| Loan size | Primary residence | Second home | Investment property |
|---|---|---|---|
| $300K to $1M | 90% | 85% | 85% |
| $1M to $1.5M | 85% | 80% | 80% |
| $1.5M to $2M | 85% | 80% | 80% |
| $2M to $2.5M | 80% | 80% | 80% |
| $2.5M to $3M | 80% | 75% | 75% |
| $3M to $3.5M | 75% | 65% | 60% |
A primary residence purchase reaches 75% at the top credit tier up to $4,000,000. Past that, the file goes to case-by-case review before submission, and the bank portfolio program’s own ladder takes over: 65% to $5,000,000, 60% to $10,000,000 and 55% to $30,000,000, each on review. Second-home leverage is available for one-unit properties only.
Other parameters, framed as typical:
- Credit: a 660 floor on the portfolio non-QM program, 680 on the bank portfolio program, and 700 above the super-jumbo line.
- Reserves: 3 months up to $500,000, 6 months up to $1,500,000, and 9 months above that. Each additional financed property adds 2 months, up to a 12-month maximum. First-time investors typically need 12.
- Super-jumbo overlays: above $3,500,000 on a primary residence and $3,000,000 on a second home or investment property, expect a 700 credit floor, a clean 0x30x24 housing history, no rural property and a ten-acre maximum. Cash-out proceeds can’t satisfy reserves.
Golf courses and big lots go together. If your property sits on acreage or reads as rural, that overlay matters.
What If Your Deposits Don’t Tell the Whole Story?
Two other paths exist, and retirees buying in golf country use them often. Through select programs, an asset allowance divides your liquid assets by 36, 60 or 84 months and adds the result to your qualifying income. It applies to primary and second homes only, with an 80% ceiling. The 84-month version also stands alone for any loan above $3,500,000.
The second path is assets-only. It uses no DTI test. Your U.S. liquid assets must equal the loan amount plus closing costs, plus sixty months of any net loss on other residential property. Retirement accounts count at 70%, or 80% once you are 59½ or older. Business funds, gifts, most trusts, unvested stock and cryptocurrency never count.
Many buyers qualify on one path and then add the other as a backstop. That might be strong deposits plus an asset allowance that lifts a borderline DTI.
Where the General Rule Breaks
The standard path is clean. These edge cases are where golf community files get complicated.
Mandatory third-party club membership. Agency-style loans can flag these arrangements, especially in condo projects. Portfolio programs are where such files commonly land. That is a reason to ask lenders early, not a reason to walk away.
Equity memberships. They can carry transfer fees, waitlists or refund delays on resale. Whatever you pay at closing for membership also needs a documented source of funds.
A struggling club. Some HOAs have tried to amend their declarations after the fact to make owners fund a failing course. A lender reviewing the HOA’s finances and legal exposure will notice. So should you.
Lumpy or falling deposits. An averaged income number rewards steady deposits. Declining statements drag the average down, and a 24-month window can hurt if the older months were stronger than the recent ones.
Seasonal income. Golf-area businesses often run on a season. A 24-month window usually presents seasonal deposits more fairly than a 12-month one. Run both and see which holds up.
Cash-out on a golf home you own. On the portfolio program, proceeds are unlimited at or below 60% LTV. Above 60% there is a $1,500,000 cash-in-hand cap. Primary residence cash-out tops out at 80% at the smallest sizes and steps down from there. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Bank Statement Loan or DSCR Loan?
Occupancy decides the product. Live in the home or use it as a second home, and the bank statement loan is the natural fit because your income carries the file. Buy it purely to rent, and a DSCR loan usually fits better.
DSCR loans are designed for non-owner-occupied investment properties. Because they are business-purpose investor loans, they are reviewed differently from a standard owner-occupied mortgage; the federal business-purpose exemption in Regulation Z is the rule behind that split. A DSCR file qualifies primarily on property-level rental income covering the payment, subject to lender guidelines. Programs below 1.00 coverage are available through select lenders in the network, but LTV and terms adjust. Lendmire’s complete DSCR loans guide walks through the mechanics.
On a rental golf home, a bank statement loan makes more sense when you want to hold the asset on your own income instead. The club and HOA costs matter for the DSCR math too, because they reduce how far rent covers the full obligation.
A common structure puts a bank statement loan on the home you live in and a DSCR loan on each rental. The reason is scaling. A bank statement loan draws on the same personal income every time, so DTI eventually becomes your ceiling. DSCR judges one property at a time.
Tax treatment can depend on how the funds are used and how the property is held; investors should keep clear records and speak with a qualified tax professional before relying on any deduction.
Your Pre-Application Checklist
Do these in order. Skipping ahead is the usual reason files stall.
1. Decide the statement window. Pull 24 months and compare with the most recent 12. Pick the stronger presentation.
2. Clean the deposits. Flag transfers and one-time credits. Write explanations for anything large before the lender asks.
3. Confirm the expense ratio. If your real overhead is lower than the fixed ratio, ask your accountant for a letter.
4. Get the club and HOA package. Dues schedule, budget, reserves, assessments, and whether membership is mandatory at transfer.
5. Add up the real monthly cost. Mortgage, taxes, insurance, HOA, mandatory club dues and any extra assessments, all in the DTI.
6. Line up reserves and source of funds. Include any initiation fee or capital contribution due at closing.
7. Ask for a program fit check. Occupancy, loan size and club structure determine which program suits the file.
Frequently Asked Questions
Do club dues count in my DTI?
Mandatory dues generally do, because they are part of the housing expense. Optional dues usually don’t count unless the contract requires the membership to transfer or you already pay them. Each lender in the network reads this a little differently, so settle it before you submit.
Does a mandatory membership hurt my approval chances?
It doesn’t disqualify you, but it changes the file. The dues go into DTI, and the lender reviews the club’s structure and ownership. A mandatory arrangement involving a third-party club is the situation most likely to move a file from agency-style financing to a portfolio program.
Can I use business statements for a golf home?
Yes, if you own at least 25% of the business. The lender applies an expense ratio to the deposits, which is 20%, 40% or 50% depending on the business, or an accountant-provided figure. Personal statements are the alternative.
Can I buy a golf community second home on bank statements?
Yes, through select programs, but leverage runs at or below the primary residence ceiling at every size. The gap is small on loans up to $2,500,000 and widens on larger ones. Second homes must be one-unit properties. The size ladder above shows the purchase ceilings by size.
What if my income is seasonal?
A 24-month window usually shows seasonal income more fairly than a 12-month one, because the lender averages across full cycles. Compare both windows. An asset allowance can also back up a strong season followed by a thin one.
Next Step
If you are financing a high-balance property on business or personal bank statements and want to see how the numbers work, Lendmire can help you compare super jumbo bank statement loan options based on your deposits, the property, credit profile, leverage, and your goals. Lendmire is a broker that shops multiple wholesale programs, and its consumer mortgage lending is licensed in 16 states: AL, CA, CO, FL, GA, IN, MI, MT, NM, NC, OH, PA, TN, TX, VA and WA. Nothing here is a commitment to lend.
A golf community home gets underwritten twice, once on you and once on the club, and the buyers who prepare for both rarely get surprised.
Lendmire’s self-employed mortgages page presents both super jumbo programs, bank statement and DSCR, side by side.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income rather than personal income, subject to lender and program guidelines, a fit for self-employed investors and LLC-owned portfolios. Lendmire was recognized as a Scotsman Guide Top Mortgage Workplace in 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. CFPB ATR/QM Compliance Guide
2. Golf Community Homes Buying Guide
3. CFPB Regulation Z §1026.3, Exempt Transactions
This article is part of Lendmire’s super jumbo bank statement loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How a Super Jumbo Bank Statement Second-Home Loan Works · How a Bank Statement Jumbo Loan Works in Aspen · How to Qualify for a Bank Statement Loan for an Estate Home
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.