
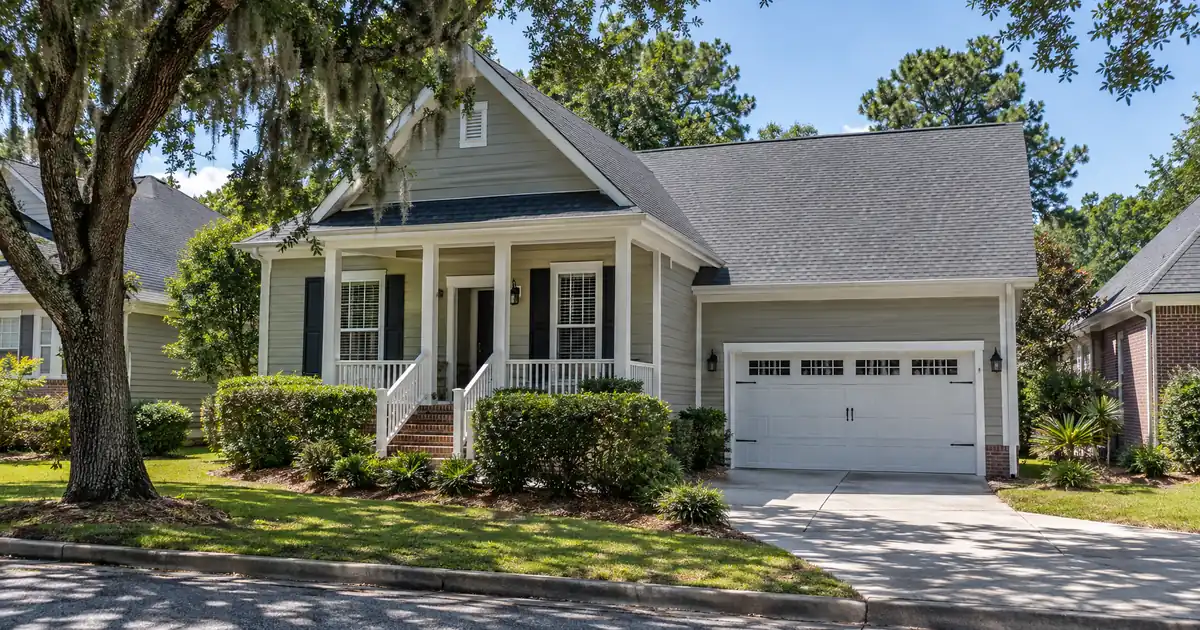
Greer was the fastest-growing city in South Carolina by residents added, and that is exactly why some investors overestimate how much equity they can pull out. Growth headlines feed the assumption that appraisals climb with population. In Greer, the data says otherwise: prices have been roughly flat, rents have slipped, and a cash-out refinance here gets sized by what the appraiser and the rent schedule support today, not by what the growth story implies.
DSCR Cash-Out Calculator
Run the cash-out numbers in Greer, SC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
A cash-out refinance on a Greer, South Carolina rental is underwritten primarily on the property’s rental income measured against its full monthly obligation. With average rents near $1,800 against a citywide value near $353,000, appraised value and the 75 percent LTV ceiling usually constrain proceeds more than credit does.
- Modeled coverage at 75 percent LTV on a newer-build price point lands around 0.90 to 0.95, including taxes and insurance. Redfin shows a February median sale price of $303K, down 8.0 percent year over year.
- BMW employs about 11,000 people at its Spartanburg County plant, surrounded by Greer city limits.
- True multifamily is scarce, so single-family and townhome refinances are the core product.
- Seasoning runs about six months from title recording, with roughly six months of PITIA in reserves.
Greer Market Snapshot
A quick read on the Greer investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | Median value $288,700 (Data USA, Greer SC) |
| Typical rents | $1,888 metro median asking (SFR Analytics) |
| University enrollment | 76,000+ Greenville county students (Move Upstate SC, Greer profile) |
| Population | 50,007 population (Post and Courier) |
| Employment | About 11,000 bmw employees (City of Greer, Doing Business) |
Growth Is Real. Appreciation Is Not Guaranteed.
Greer added 3,412 residents in a single year, a 7.3 percent jump that took the official count to 50,007, per The Post and Courier reporting on new U.S. Census Bureau estimates. The city’s own About Greer page cites about 55,000 residents. Use the Census-based number for underwriting narratives. Either way, the demand base is expanding.
Pricing tells a quieter story. Zillow’s modeled average value is up 1.7 percent year over year, while Redfin’s February median sale price is down 8.0 percent at $303K, on price per square foot that held near $167. The definitions differ, and neither should be averaged with the other. Read the pair as a range: flat to slightly soft. Redfin also logged only 34 sales that month against 82 a year earlier, with homes averaging 92 days on market. Thin comps mean more appraisal variance. (One winter month overstates the seasonality, but the direction matters.)
For an equity-extraction plan, the implication is blunt. A refinance that assumes the value has climbed since purchase is a bet, not a plan. Underwrite to today’s comparable sales.
What Does 75 Percent Leverage Do to Coverage Here?
At the 75 percent LTV cash-out ceiling, Greer rents leave little cushion. Modeled on full PITIA (principal, interest, taxes, and insurance), a newer-build valuation lands near 0.90 to 0.95 coverage. Older, lower-basis product clears 1.00 more easily. Most lenders benchmark DSCR programs at 1.00x, subject to lender guidelines.
Run the numbers on two modeled cases. These are illustrative assumptions built from researched price and rent points, not quotes.
Case one: a newer-build rental valued near $334,000. That figure matches the median listing price on Redfin’s Greer new-construction page, which shows 93 new homes for sale. Assume $1,800 in monthly rent, in line with Zumper’s house average. At 75 percent LTV, coverage including taxes and insurance runs roughly 0.90 to 0.95. Drop to about 65 percent LTV and the number moves to right around 1.00.
Case two: an older workforce house appraising near $288,700. That is the census-derived median property value on Data USA. Same $1,800 rent, same 75 percent LTV. Coverage improves to about 1.05, including taxes and insurance.
The gap between those cases is the whole story. Lower-basis, older stock supports full-leverage cash-out. Premium-priced new construction often does not.
If a file lands under 1.00, options exist that a lender would review: a sub-1.00 program, a lower LTV, or different pricing and more cash reserves. Some lenders review below-baseline scenarios, but those usually demand stronger compensating factors. Eligibility depends on lender guidelines, credit profile, reserves, and property review.
One more datapoint frames the ceiling. Homes.com puts Greer’s price-to-rent ratio at 15.4, and local brokers call the 2 percent rule rarely achievable here. This is a market for the 1.0 to 1.25 range, not for double-digit cash flow.
Tenant Demand: BMW, the Inland Port, and a 24-Minute Commute
Greer’s rental base is industrial, and that is a feature for a refinance file. The City of Greer says BMW employs about 11,000 people and has expanded its footprint into Greer. The SC Department of Commerce reports more than $7 billion invested in BMW’s South Carolina operations. Per Upstate Business Journal, the BMW plant, the Greenville-Spartanburg airport, and Inland Port Greer are not technically inside the city, but Greer’s limits surround them.
The SC Ports Authority runs the Inland Port with 24/7 gates, and the site opened with BMW as its first customer. More is coming: BMW has announced a $200 million press shop that added 200 jobs, per The Post and Courier, and a $700 million battery assembly plant is under construction in nearby Woodruff.
Resident employment is diversified beyond the plant. Per Data USA, manufacturing employs 3,667 residents, health care and social assistance 3,230, and retail 2,138, with an average commute of 24.3 minutes. Prisma Health is expanding Greer Memorial Hospital with a new medical park building.
None of this is a rent-growth guarantee. Rents are flat to down: Zillow shows a $50 year-over-year decline, and RentCafe’s apartment-only figure is down 3.4 percent. What the employer base gives a refinance file is durability. Tenant demand comes from workers, not students (no four-year college sits inside Greer), and RentCafe puts the renter share at 27 percent of households.
Four Pockets, Ranked by Refinance Potential
No verified per-neighborhood rent or price series exists for Greer, so the submarket read here is qualitative. That is a data gap, and it is better named than papered over.
Highway 101 and Highway 14, toward the BMW plant and Inland Port. This is the strongest cash-out corridor for existing owners. It holds most of the new subdivisions and a workforce tenant base tied to major employers. Local brokers describe occupancy as stable here, though that comes from a brokerage blog and should be treated as directional. Property values sit at a middle price band, which is where coverage stays workable.
Downtown Greer, Trade Street, and the older core. Older infill housing and some newer duplex product sit near the historic center. Duplexes are the scarce play here. If an investor already owns one, the refinance case is real because the product is hard to replace. Listing counts show how thin the supply is, and the pricing needs a local check.
Taylors edge and the Wade Hampton corridor. This Greenville-side border area is a value-add candidate. Ranch-style workforce houses and larger lots are the typical product, and some parcels could carry a second dwelling. A value-add refinance here depends on the appraiser finding close comps, which is the exact weakness thin Greer sales volume creates.
The Pelham Road and Eastside corridor, plus Sugar Creek and Seven Oaks. Established subdivisions like Pelham Falls and Silverleaf, and premium new-build neighborhoods, sit at the top of the price range. The higher basis pushes coverage toward the low end at 75 percent LTV. Owners here are usually better served by a lower-leverage cash-out or a rate-and-term structure than by a maximum-proceeds request. Think of these pockets as a contrast to the workforce corridors, not a target.
Townhomes are the other product type worth flagging. Redfin’s Greer listings showed 105 townhouses for sale against a single multifamily unit in one recent month. The Homes.com rental page calls townhouses the more affordable rental option, though it attaches no dollar figure.
The Duplex Story Doesn’t Add Up
Small multifamily in Greer is a scarcity play, not a rent-stacking play. There is not enough true multifamily inventory to build a market study, and the research found no per-unit duplex or fourplex rent series. House rentals run well above apartment averages (Homes.com shows single-family median rent at $1,949 versus $1,573 for large-building apartments on RentCafe), so two smaller units must beat one house’s rent by enough to cover a higher price. Nothing in the data shows they do.
The stronger play might be an existing single-family or townhome hold in the workforce corridor, though investors owning a duplex near downtown could argue the scarcity premium is worth keeping. This one’s a genuine toss-up, and rent rolls will decide it, not the neighborhood.
Working DSCR brokers see a recurring pattern in industrial-workforce markets like this one: the file clears on rent, then stalls on the appraisal. Coverage is calculated off a rent schedule that looks fine, but the value comes back a step below the owner’s expectation because recent sales are sparse. Owners who go in with their own comparable-sales research, and who accept a lower LTV before the appraisal rather than after, tend to have fewer surprises. Ordering a broker price check before formally applying is cheap insurance.
Seasoning, Reserves, and What the Proceeds Actually Do
Cash-out proceeds are only useful if the borrower can redeploy them at a better return than the equity earns sitting in the property. In Greer, that logic favors buying additional workforce houses in the mid-price corridors, since the new-build premium erodes coverage.
Program guidance for cash-out on an investment property is straightforward. The LTV ceiling is 75 percent, and seasoning is about six months of ownership, measured from title recording. Minimum DSCR is 1.00 as a common baseline, credit tiers run from a 620 floor upward, and reserves are typically about six months of PITIA. Loan sizes reach up to $3,000,000 on standard programs, with smaller balances routed through select lenders in the network. These are guideline ranges, not guarantees, and eligibility review depends on lender overlays, credit approval, and property review. Manufactured homes, log homes, and barndominiums fall outside these programs.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Greer?
Qualification centers on the property’s rent compared with its full PITIA, plus credit, reserves, and seasoning. Most programs benchmark at 1.00x coverage with a 620 credit floor, about six months of PITIA in reserves, and roughly six months of ownership. A Greer house renting near $1,800 needs to clear that ratio at the appraised value, all subject to lender guidelines.
DSCR vs. conventional financing
Two common ways to finance an investment property in Greer, SC. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property refinance in Greer, South Carolina?
The property should be an eligible type such as a single-family house, townhome, or small multifamily, held about six months from title recording. Cash-out tops out at 75 percent LTV, and the loan amount and reserves depend on the program. Manufactured homes, log homes, and barndominiums are outside these programs. Greer straddles Greenville and Spartanburg counties, so confirm a property’s county and current local rules, taxes, and insurance with qualified local professionals.
Can a Greer property bought at a lower price still support meaningful cash-out?
Often yes, if the appraisal supports it, because the older workforce stock produces stronger coverage at 75 percent LTV than premium new construction. The catch is that Redfin’s median sale price fell year over year, so appraised value may land below expectations. Proceeds are never a guaranteed figure. They depend on rent used for lender review, PITIA, reserves, and the LTV ceiling.
Does the BMW plant guarantee rising rents in Greer?
No. It supports steady workforce demand, not rent growth. Zillow shows average rents down $50 year over year, even with roughly 11,000 BMW jobs nearby and more investment announced. The employer base helps a file read as stable, but the rent figure is what gets underwritten.
What loan-amount ranges may DSCR lenders review for Greer rental properties?
Standard programs reach up to $3,000,000, and smaller balances route through select lenders in the network. Lendmire is a mortgage broker that arranges these loans through wholesale channels rather than lending directly. Greer’s typical single-family values sit well inside that range.
Before You Order the Appraisal
Greer’s fundamentals, a BMW-anchored workforce and a fast-growing population, are strong enough to support a long hold, and its prices are soft enough that equity extraction should be sized to today’s comps, not last cycle’s peak. If your rental is a lower-basis house in the Highway 101 or Highway 14 corridor, the 75 percent ceiling may work. If it sits in a premium subdivision, a lower LTV may be the smarter ask. Which of those describes the property you own, and what would you do with the proceeds if the appraisal came back a step short?
About Lendmire
Lendmire, NMLS# 2371349, works with Greer, South Carolina investors to place DSCR financing through wholesale lenders reaching 41 markets — 40 states plus Washington, D.C. Unlike some larger non-QM lenders that treat investor loans as a side product, the brokerage is built around this category, and it has been recognized by Scotsman Guide as a 2026 Top Workplace. Investors comparing structures can read the guide “What Is a DSCR Loan” for how DSCR loans work, see the guide “The Refi Options”, or review rate-and-term and cash-out refi details. Lendmire also covers the trade-offs of conventional vs DSCR on investor loans, and the statewide overview sits on the South Carolina DSCR investor loans hub.
One caution on supply. Local commentary suggests new apartment deliveries are concentrated in downtown Greenville and Greer, which is the main competing supply for renters. Older workforce houses face less of that pressure than newer townhomes do. That is commentary, not a vacancy survey, so weigh it lightly.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. $1,800
2. $353,000
3. Redfin: Greer housing market
4. SC Department of Commerce: BMW
7. Move Upstate SC, Greer profile
8. The Post and Courier: Greer population growth
9. City of Greer: Doing Business Here
10. U.S. Census Bureau QuickFacts: Greer city
11. About Greer page
12. Redfin’s Greer new-construction page
13. Zumper’s
14. Homes.com
16. SC Ports Authority: Inland Port Greer
18. Prisma Health: Greer Memorial Hospital
19. RentCafe
20. recognized by Scotsman Guide as a 2026 Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance Greer South Carolina · Cash Out Refinance Investment Property Florence South Carolina · DSCR Cash Out Refinance Irmo South Carolina
Guides: Investment Property Cash-Out Refinance in Greer, SC · Investment Property Cash-Out Refinance in South Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.