
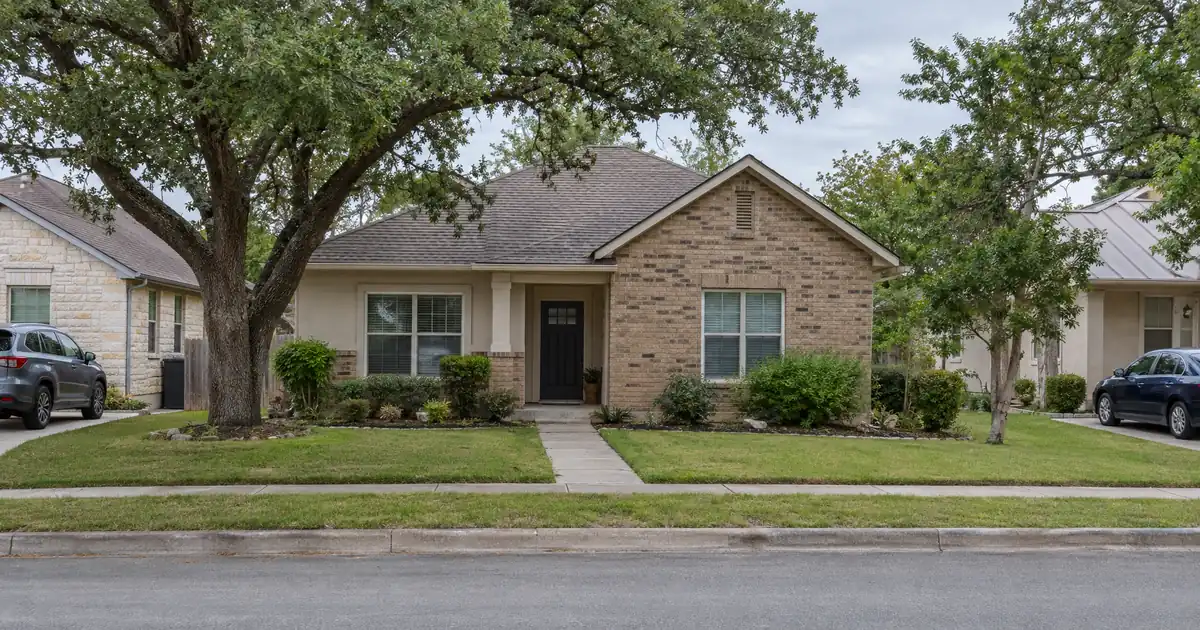
Two Kerrville cash-out files look nothing alike, and the math favors one of them. The first is a single-family house valued near the citywide average of $354,872, renting at the $1,800 average. At the 75 percent LTV ceiling, that file struggles to reach 1.00 coverage once taxes and insurance are counted. The second is a small multifamily building where four two-bedroom doors gross several times what one house does. The fourplex file is the one that can clear the number, and it is also the one Kerrville barely has.
TL;DR: A Kerrville, Texas cash-out refinance on an investment property is underwritten primarily on the property’s rental income measured against its full monthly obligation, and because single-family rents here cover only a fraction of that obligation at 75 percent LTV, proceeds usually depend on a lower LTV or a multi-unit rent roll.
DSCR Cash-Out Calculator
Run the cash-out numbers in Kerrville, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Single-family rent-to-value is thin, so coverage tends to land below 1.00 at the 75 percent cap.
- Small multifamily is scarce but carries the most coverage per dollar of price.
- Thin sales volume means the appraisal, not the headline median, sets your proceeds.
- Hospital, VA and school payrolls anchor tenant demand.
- Cash-out generally requires about six months of ownership from title recording.
Kerrville Market Snapshot
A quick read on the Kerrville investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $1,134 gross (City-Data Kerrville housing) |
| University enrollment | 1,470 total (Schreiner University Fall 2025) |
| Employment | 40 jobs (Kerr EDC) |
Why the House Loses to the Fourplex
Kerrville single-family rentals produce roughly half a percent of value in monthly rent, and that is too little to support 75 percent LTV on a cash-out. The gap closes only with lower leverage or with multi-unit product, where rent per door runs higher relative to price.
Start with the sourced rents. Zumper puts the three-bedroom median near $2,000 and Rentometer’s three-bedroom average at $2,159. Against a house valued in the mid-$300,000s, that is a gross monthly yield of 0.5 to 0.6 percent. Model it with a standard 30-year amortization and Texas-average taxes and insurance, and a house at those rents lands in the low 0.8s at 75 percent LTV and somewhere near 1.0 at roughly 60 percent. These are modeled assumptions, not sourced market data. Coverage also improves in the borrower’s favor at lower balances, so an older, paid-down purchase behaves better than a recent one.
Now the multi-unit side. Zillow shows a two-bedroom near $1,575 and Rentometer shows $1,568. Model four doors at about $1,570 each, or $6,280 gross. On a hypothetical $750,000 fourplex at 75 percent LTV, including taxes and insurance, coverage runs in the low 1.2s. Push the modeled price to about $900,000 and it drifts back toward 1.00. Price per door is the whole game.
| Structure | Modeled rent basis | Coverage at 75% LTV |
|---|---|---|
| Single-family, 3BR | About $2,000 to $2,160 | Low 0.8s to about 0.9 |
| Fourplex at $750,000 | About $6,280 gross | Low 1.2s |
| Fourplex at $900,000 | About $6,280 gross | Near 1.00 |
Here’s the catch: the supply. NeighborhoodScout puts single-family detached homes at 63.18 percent of Kerrville’s units, with duplexes and small converted buildings at only 6.95 percent. An owner who already holds a duplex or fourplex is sitting on the scarcest product in town. An investor still hunting for one should read the comparison of DSCR and conventional financing before committing to a structure.
Appraisals in a Market With Low-Double-Digit Sales
Kerrville’s headline appreciation figures come from only a low double-digit number of sales a month, so proceeds should be sized on conservative comps rather than on any one median. Sources disagree, and the disagreement is the point.
Zillow’s average value is the figure used here: $354,872, down 2.3 percent over the past year. Houzeo reports a lower median sale price of $339,000, essentially flat, with 6.9 months of supply and 109 days on market. Redfin shows a $365,000 median up 17 percent, but that came from only 21 sales, and days on market stretched to 131 from 47 a year earlier. Different methodologies, different samples. Orchard shows more than half of active listings with price cuts.
Read that as a buyer’s market for purchases, and a warning for refinances. The 75 percent cap applies to the appraised value, so a softer appraisal shrinks proceeds proportionally. An owner who bought at a real discount can still extract meaningful equity. An owner counting on Kerrville appreciation to manufacture equity in six months probably can’t. Equity from price growth is not the bet here. Equity from a good entry price and a lower-LTV structure is.
Working DSCR brokers see a recurring pattern in thin, small-town markets like this one: the file clears on rent but shrinks on appraisal, and the borrower’s expected proceeds move more from the valuation than from the coverage number. The stronger files pull comparable sales and a lender rent schedule together before the application goes in. Proceeds then reflect the property’s real income and real comps, not a Zillow estimate.
Who Actually Pays the Rent
Kerrville’s tenant base rests on healthcare and government payrolls, which is steady, non-cyclical demand that holds up better than the for-sale market does. The city’s workforce page lists Peterson Regional Medical Center, South Texas Veterans Health Care System-Kerrville, Kerrville State Hospital, Kerrville ISD, H-E-B, Lowe’s, Walmart, James Avery Craftsman, Home Depot, the City of Kerrville and Kerr County as top employers.
Peterson is the anchor. Its employer profile describes a 124-bed hospital and roughly 1,000 full-time employees, though other sources put the count slightly under that, so “roughly 900 to 1,000” is the safer read. The Kerrville VA Medical Center adds primary care, specialty services, dialysis and hospice. Clinical and support staff at those institutions are the natural long-term tenant pool for a workforce rental.
Two smaller demand sources matter at the margin. Schreiner University reported record enrollment of 1,470 students, up 11 percent, with a first-time freshman class of 434, up 33 percent, and a strategic target of 2,030 students by the end of the decade. And Kerr EDC reports Megaacrete’s $40 million U.S. headquarters near the airport, set to create 40 initial jobs. Forty jobs won’t move a rent roll. Schreiner’s growth might, near campus.
Census-based gross rent of $1,134 reflects existing leases, while the $1,800 average reflects current asking rents, and the gap between them is large. Underwrite to the lender’s rent schedule for your unit type, not to any single citywide average. No reliable rental vacancy figure exists in the research, so treat Zillow’s “HOT” rental designation as directional only.
Submarkets: Where Cash-Out Files Hold Up
The medical corridor and the older workforce neighborhoods carry the best cash-out files, while Riverhill and Comanche Trace are for lifestyle buyers, not DSCR. None of the sources gave neighborhood-level rents, so this is a qualitative read.
Medical corridor. Around Peterson Regional Medical Center and Sidney Baker Street, tenant demand comes from hospital staff, and the hospital moved into its current facility in April 2008. It’s the strongest tenant story in the city. Look here first for a house or small building that can support a rent schedule at moderate LTV.
Greenwood Forest and Starkey Manor. These are older, workforce-oriented neighborhoods, with Greenwood Forest described as cozy homes on large lots near Schreiner Golf Course. Lower entry prices are the appeal, and lower entry prices are what improve rent-to-value. No price data was found, so run the appraisal before assuming anything.
Schreiner corridor and Loop 534 / Olympic Drive. Rooms and small units near campus benefit from enrollment growth. This is also where the homebuilder pipeline lands, which cuts the other way (see the next section).
Downtown and the river corridor. The older stock near the Guadalupe River has character and a much less certain lending profile. Kerr County homes flooded in two consecutive summers, and Redfin estimates 24 percent of properties face severe flood risk over the next 30 years. For a cash-out, flood-zone status can decide how a property is reviewed. Verify current flood maps, insurance and local rental rules with qualified local professionals before you build a refinance plan around any river-adjacent asset.
Skip Riverhill and Comanche Trace for cash flow. Riverhill is a country-club neighborhood of large custom homes, and Comanche Trace is a gated golf community, so both are owner-occupied, high-price and poor on rent-to-value. Redfin shows Comanche Trace listings sitting 167 days. Not a DSCR play.
Lennar Is Building 620 Homes
Kerr EDC says Lennar is developing 620 homes across two projects to address a significant housing shortage, and the city may reimburse up to $27 million in infrastructure costs. An earlier local plan called for 719 homes on land annexed from Schreiner. Six hundred twenty new homes in a city of roughly 25,000 is a big addition. It fills a real shortage. It also puts new-build product in front of the same renters your older stock competes for.
Think it through as a landlord. The stronger play is probably older, well-located rental stock priced at a discount, not competing against new construction on finishes. The counterargument is that a supply gap this large may take years to fill, so rents hold. This one is a toss-up, and it’s a reason not to size a refinance on the assumption that rents keep climbing. Zumper’s 5.9 percent year-over-year rent growth is real, but its sample is only 61 rentals.
Sizing the Cash-Out (Percentages, Not Promises)
Run every proceeds estimate through four constraints: the 75 percent LTV ceiling on cash-outs, the roughly six-month seasoning period from title recording, the 1.00 minimum coverage on rent used for lender review against full PITIA, and about six months of PITIA in reserves. Credit tiers typically start at a 620 floor and improve pricing and leverage as scores climb, subject to lender guidelines. Standard programs generally run up to $3,000,000, and smaller balances route through select lenders in the network. Equity available is never a guaranteed figure. It depends on rent used for lender review, PITIA, reserves and the appraisal.
When a house doesn’t clear 1.00 at 75 percent, the structures a lender may review include a lower LTV cash-out, a sub-1.00 program with reduced leverage and stronger credit, or an interest-only structure. Each involves trade-offs, and qualification remains subject to lender guidelines, credit approval and property review.
Consider the equity recycle pathway. An owner with a fully rented fourplex refinances at or below 75 percent LTV, pulls the proceeds and puts them toward the next acquisition. In Kerrville the next deal is the harder part, because the buyer’s market that helps entry pricing also means the exit and appraisal side stays soft. The equity recycle pathway and rate-and-term and cash-out refi details cover the mechanics, and Lendmire’s primer on DSCR loans covers the basics.
The Diligence Step Before Any Application
Before pursuing anything else, pull three recent closed comparable sales within Kerrville for the specific property type and set them beside a written rent schedule. In a market where monthly sales sit in the low double digits, that single exercise tells you more about achievable proceeds than any median. For property types, pay attention to any duplex or fourplex in the medical corridor, where the tenant story and the scarcity premium overlap. Pair it with a flood-map check on anything near the Guadalupe. Texas DSCR financing has the state-level program framing.
DSCR vs. conventional financing
Two common ways to finance an investment property in Kerrville, TX. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR loan in Kerrville?
Qualification centers on the property’s rent measured against its full monthly obligation, with 1.00 as the standard benchmark. Credit tiers generally start at a 620 floor, and reserves of about six months PITIA are typical. In Kerrville the rent side is the constraint on single-family homes, so lower LTV or multi-unit product often matters more than credit. All of this is subject to lender guidelines.
What are the requirements for an investment property cash-out refinance in Kerrville, Texas?
Expect a 75 percent LTV ceiling, about six months of ownership measured from title recording, a 1.00 minimum coverage and roughly six months of reserves. Standard programs generally run up to $3,000,000. Proceeds depend on the appraisal, rent used for lender review and PITIA, so they are never guaranteed.
What can slow down a Kerrville DSCR cash-out refinance?
Thin comps, a soft appraisal and a flood-zone review on river-adjacent property are the usual friction points. Lendmire arranges DSCR investor loans through lenders where qualification centers on the property’s rental income. Bringing a lender rent schedule and recent comps to the first conversation helps.
Does a property near the Guadalupe River complicate a cash-out?
Yes, it can. Flood-zone status affects how a property is reviewed, and the county’s two recent floods have heightened that scrutiny. Check current flood maps and insurance with qualified local professionals before planning a refinance around any river-adjacent asset.
Is a six-month seasoning period long enough to pull equity in Kerrville?
Seasoning only makes the property eligible; it doesn’t create equity. With appreciation flat to negative in several sources, proceeds depend mostly on the purchase discount and appraised value. An owner who bought well below market has room, while one who paid near average value may find little.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income rather than the borrower’s W-2 history, which suits LLC-titled portfolios and self-employed investors. Every scenario remains subject to program review and program guidelines. Lendmire was recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2025.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Home Values, Kerrville
2. Zillow Rental Manager, Kerrville
3. $1,134
4. Schreiner University Fall 2025
5. Kerr EDC
6. Zumper Kerrville Rent Research
9. Houzeo
10. Redfin
11. Orchard
12. kerrvilletx.gov — Workforce page
14. Kerrville VA Medical Center
15. Texas Tribune, Kerr County Floods
16. a 2026 Scotsman Guide Top Mortgage Workplace
17. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance Kerrville Texas · Cash Out Refinance Investment Property San Antonio Texas · DSCR Cash Out Refinance San Antonio Texas
Guides: Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.