
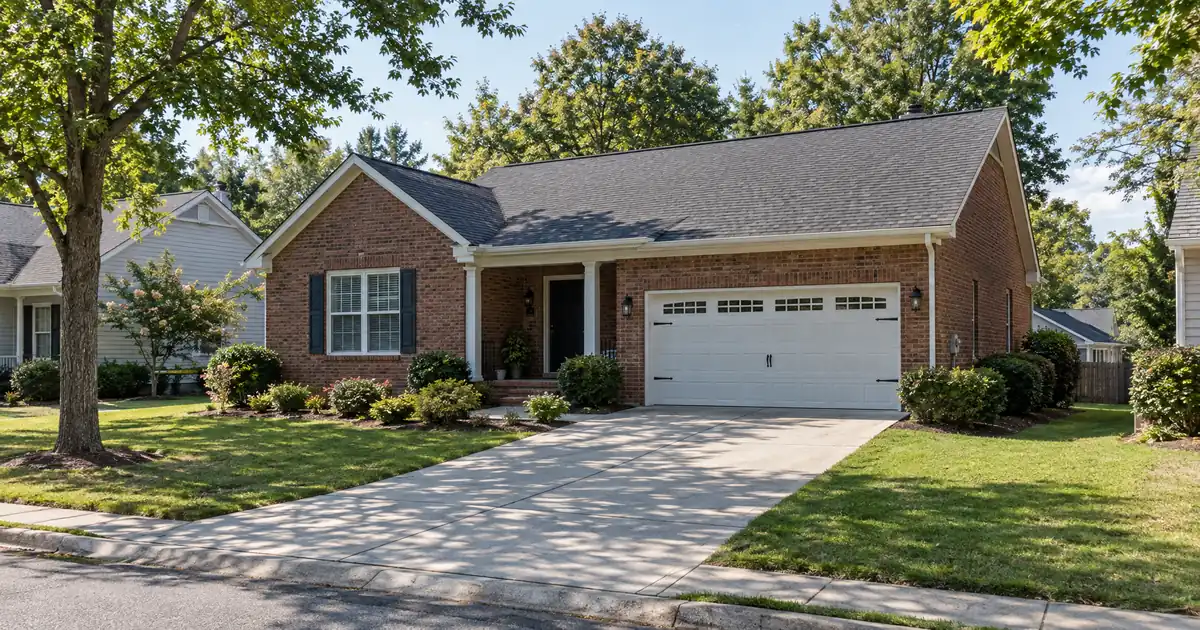
A three-bedroom rental in older Monroe hits the DSCR math like this. Model it at a modest older-stock value (a placeholder for illustration, not a sourced price) with rent of $1,960, the three-bedroom figure Prop:Metrics reports for ZIP 28110. At 75 percent loan-to-value, with taxes and insurance counted in the monthly obligation, coverage lands comfortably above 1.0x. Put the same rent on a house valued far higher and coverage drops well below 1.0x. Same tenant, same lease, very different refinance.
That gap drives every cash-out decision in this market. Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker. Investors in Monroe, North Carolina work with Lendmire to place DSCR financing through wholesale lenders reaching 41 markets, including D.C.
DSCR Cash-Out Calculator
Run the cash-out numbers in Monroe, NC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
TL;DR: A cash-out refinance on a Monroe, North Carolina rental is underwritten primarily on the property’s rental income measured against its full monthly obligation. The sequence runs from seasoning and appraisal, to a rent schedule, to a coverage ratio, and only then to how much equity the loan-to-value cap releases.
- Median-priced houses rent near half a percent of value monthly, so cash-out leverage gets tight.
- Older two- and three-bedroom stock and small multifamily carry the stronger coverage.
- About six months of ownership and a 75 percent LTV ceiling frame every cash-out.
- Redfin shows the median sale price down 2.6 percent year over year, so the appraisal sets proceeds.
Monroe Market Snapshot
A quick read on the Monroe investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| University enrollment | 40,000 students (Union County Chamber, UCPS) |
| Employment | About 5,000 employees (Union County Chamber, UCPS) |
How the Equity Math Works, Step by Step
Cash-out proceeds are the smallest of three numbers: what the appraisal supports, what the rent can carry, and what the reserves allow. Each step below removes some of the theoretical equity, and the order matters.
Step one is seasoning. Most programs in the network look for about six months of ownership measured from title recording, so a freshly bought Monroe rental generally can’t be cashed out on day one. Terms vary by lender and borrower.
Step two is the appraisal. It sets the value, and the loan-to-value cap applies to that number. On cash-out, the ceiling is 75 percent. That is lower than the purchase cap, which trips up investors who assume the two match.
Step three is coverage. Divide the monthly rent (from a lease or an appraiser’s rent schedule) by the full monthly obligation: principal, interest, taxes, insurance, and any HOA dues. The standard benchmark is 1.00x, meaning rent covers the payment. Some lenders review lower ratios with compensating factors, but that usually means less leverage or a different structure. Eligibility depends on lender guidelines, credit, reserves, and property review. The guide “What Is a DSCR Loan” covers the mechanics in more detail.
Step four is reserves. Expect about six months of the monthly obligation held in reserve on most files. Credit tiers generally start at a 620 floor, with pricing and leverage improving at higher tiers.
Equity available is therefore not a guaranteed figure. Cash-out refinance details walk through the sequence, and the calculator converts percentages into dollars.
Why Median-Priced Houses Struggle Here
Median-priced single-family rentals in Monroe carry thin rent-to-value, and that is the biggest constraint on cash-out proceeds. Redfin puts the city’s median sale price at $400,000. Prop:Metrics shows $370,000 for ZIP 28110, a different geography and vintage, so treat the two as a range rather than a contradiction.
Rent against that price is about 0.49 to 0.53 percent monthly (illustrative arithmetic across two sources). Apartments.com lists an average house rent of $2,068, which is about 0.52 percent against the $400,000 median. A higher portal figure of $2,250 exists on Homes.com, but underwriting shouldn’t lean on it. Portal averages aren’t appraisals.
Run the numbers on a $400,000 house at $1,960 rent, 75 percent LTV, taxes and insurance included. Coverage falls in the low 0.8s, an assumption-driven model rather than a quote. Not close.
This is where a sub-1.00 file gets a second look, not a rubber stamp. A lender may review a sub-1.00 program, an interest-only structure, or a lower LTV that brings the payment down. Each usually costs something in pricing, reserves, or cash left in the deal, and approval stays subject to lender guidelines, credit, and property review. The bigger question is whether the property belongs in the cash-out plan at all. If the only way to make a house work is a sub-1.00 structure, the submarket may be the problem, not the loan.
Where Coverage Holds: Older Stock and Small Multifamily
The strongest coverage in Monroe sits in older two- and three-bedroom houses and in the scarce duplex. Local commentary from 10 Federal Storage, a business blog and therefore qualitative, says older ranch homes and bungalows start in the low $200,000s. Rents for those units aren’t much lower than rents on newer houses, which is the whole ratio story.
Duplexes first, because scarcity defines them. NeighborhoodScout puts duplexes, converted homes, and small apartment buildings at 8.63 percent of Monroe’s housing units, against 71.17 percent single-family detached. You find these listing by listing, not by screening.
Consider a modeled duplex valued at $450,000 (an assumption), with each side renting at the $1,670 two-bedroom figure. Gross rent is $3,340, and coverage at 75 percent LTV including taxes and insurance comes out around 1.2x. Rents on a real duplex are unit-specific, so underwrite from leases or an appraiser’s schedule. A new-build duplex with three-bedroom sides was listed on Redfin with a listing-agent estimate of $4,100 combined. That is marketing copy, not a lease, though it shows why two doors on one loan can beat the roughly 0.5 percent single-family ratio.
The older core is the likeliest hunting ground. The city’s About Monroe page describes an ongoing downtown revitalization, and Homes.com listings show older duplexes in the Downtown Monroe Historic District with two-bedroom sides. No source confirms how many exist, so treat the core as a search area, not a proven supply.
The stronger play might be the older workforce house over the duplex if a good duplex never appears. Some investors prefer holding out for multifamily, though, and that’s a legitimate call if the timeline allows.
The New-Build Ring: Braemar Village and Its Neighbors
New subdivisions trade at $375,000 to $425,000, according to the same storage-company blog, and the ratio there is the thinnest in the city. Braemar Village is the example the blog names. Rent-to-value at those prices mirrors the median-house problem, so cash-out leverage will be limited.
Supply adds pressure. A May Longleaf Group guide, which is agent marketing, describes active communities from six national builders at once. More builder inventory can hold down resale comps and new-construction rents. Redfin shows days on market at 84, up from 69 a year earlier. Values that soften or flatten mean the appraisal, not assumed appreciation, decides how much equity actually releases.
One counterpoint: Redfin’s median price per square foot is $205, up 10.2 percent. The two figures diverge because the mix of homes selling has shifted. Investors who bought in older, smaller stock may see a cleaner appreciation story than the headline median implies. A current appraisal settles it.
Employers Behind the Rent Roll
Monroe’s rental demand rests on industrial and health employers plus Charlotte commuting, a mix unusual for a Charlotte-ring suburb. The Monroe Office of Economic Development calls the city one of the fastest-growing in the country, and BiggestUSCities cites a population of 37,797, up 38.0 percent over roughly the past quarter century.
The anchors are these:
- ATI Specialty Materials. NC Commerce has described ATI as one of Union County’s largest employers, and the city has approved further annexation tied to roughly $300 million of investment. No sourced headcount exists.
- Atrium Health Union. Atrium Health Union is a 182-bed hospital in Monroe.
- Union County Public Schools. The Union County Chamber lists about 5,000 employees, though the listing is dated.
- South Piedmont Community College. Business NC reports enrollment of about 7,500.
The Monroe Expressway, an 18-mile all-electronic toll road, links Monroe to the Charlotte side of the I-485 loop and has shifted where growth lands. The Monroe Corporate Center sits next to the airport and the college, and it draws workforce tenants from industrial employers.
Working DSCR brokers see a recurring pattern in Charlotte-ring suburbs like this one: the rent looks healthy on a lease, but the coverage number fails once taxes and insurance land in the payment at a median price. The files that hold together tend to combine a modest purchase basis, a documented rent schedule, and reserves that were set aside before the appraisal came back. Working backward from that structure beats reaching for leverage the property can’t carry.
Wingate University sits in the neighboring town, not Monroe. US News lists 3,458 students with 73 percent in college-affiliated housing. That makes the school a small anchor for staff and graduate-student rentals, not a student-rental play.
What Happens to the Proceeds
Cash-out works when the proceeds go somewhere with better coverage than where they came from. Pulling equity from an older Monroe house to buy a duplex in the same submarket, where the ratio clears 1.20x, is a clean argument. Pulling equity from a house that barely covers to buy a new-build at $400,000 stacks the same thin ratio twice. Not the plan.
If the rental is held in an LLC, program terms apply, subject to lender program eligibility. Personal-name holdings and entity holdings can be treated differently at the table.
For an investor with one or two properties and strong traditional employment income, the guide “Where DSCR and Conventional Diverge” against conventional is worth a look first. Conventional can carry lower cost when the borrower’s traditional personal-income documentation supports the rental income cleanly. DSCR becomes the practical path when portfolio count, self-employment income, or entity ownership make the personal-income file messy. The investment property refinance options cover the rate-and-term alternative when the goal is restructuring rather than extraction. For a state-level view, see North Carolina DSCR investor loans.
DSCR vs. conventional financing
Two common ways to finance an investment property in Monroe, NC. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
To test a specific Monroe property against the ratio, see how the DSCR math pencils or call Lendmire at 828-256-2183. Property tax, insurance, and local rental rules vary, so confirm them with qualified local professionals before committing.
Frequently Asked Questions
How much equity can I pull from a Monroe rental?
It depends on the appraisal, the rent, and the reserves. The 75 percent LTV ceiling caps the total loan, existing debt comes off the top, and coverage has to clear the lender’s minimum on the rent schedule. Proceeds are not a guaranteed figure, and guidelines vary by lender.
Does a flat market hurt a cash-out here?
Yes, in one specific way. With Redfin showing prices down 2.6 percent year over year and days on market at 84, the appraisal may come in near purchase price. Investors relying on assumed appreciation can find the released equity smaller than planned.
Can I refinance a new-subdivision house right after buying it?
Seasoning of about six months from title recording generally applies first. Even after that, a $375,000 to $425,000 new-build renting near the median ratio produces thin coverage, so proceeds may be limited.
Do duplexes really pencil better than houses in Monroe?
On modeled numbers, yes. Two-bedroom units at $1,670 each produce coverage around 1.2x at a modeled $450,000 value, while a median house lands in the low 0.8s. The catch is supply: small multifamily is 8.63 percent of units, and listing rents are estimates until an appraiser confirms them.
Does Wingate University create student-rental demand in Monroe?
Only modestly. Wingate is in a neighboring town, and 73 percent of its students live in college-affiliated housing. It supports staff and graduate-student rentals more than a student-rental business.
The Number That Reframes Monroe
Monroe has 5,020 renter households, according to RentCafe, yet small multifamily makes up only 8.63 percent of its housing units, so the equity that funds your next duplex has to come from a house you already own.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage focused on DSCR investor lending, with programs across 41 markets, including Washington, D.C. Lenders in the network commonly review rental-income coverage rather than personal-income paperwork, which suits LLC-owned and multi-property investors. Terms vary by lender, property, leverage, and program. Lendmire is a 2026 Scotsman Guide Top Workplace and a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Redfin, Monroe housing market
6. NeighborhoodScout, Monroe real estate
7. Redfin
10. Monroe Office of Economic Development
12. NC Commerce
16. RentCafe
17. 2026 Scotsman Guide Top Workplace
18. 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance Monroe North Carolina · Cash Out Refinance Investment Property Greensboro North Carolina · DSCR Cash Out Refinance Rocky Mount North Carolina
Guides: Investment Property Cash-Out Refinance in North Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.