
Redfin puts the St. Simons median sale price at $664K, down 2.9 percent year over year. Zillow’s value index reads $681,128 and up 1.8 percent. Two credible sources, opposite signs. For an investor holding a paid-down rental and eyeing a cash-out refinance, that split is the whole story: the equity is real, but the appraisal is not a given.
The Quick Read: A cash-out refinance on a St Simons Island, Georgia rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with leverage capped at 75 percent of value and roughly six months of ownership required first, subject to lender guidelines.
DSCR Cash-Out Calculator
Run the cash-out numbers in St Simons Island, GA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Single-family at island-average prices models below 1.00x on full PITIA, before any cash-out.
- Mid-island condos near the Frederica and Demere corridor are the most plausible coverage fit.
- Brokerage data shows 7.7 months of supply, per MoveWithMomentum.
- Seasoning runs about six months from title recording.
- Proceeds depend on the appraisal, rent, and reserves, not on assumed appreciation.
St Simons Island Market Snapshot
A quick read on the St Simons Island investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $664K median (Redfin, St. Simons housing) |
| University enrollment | ~3,700 students (College of Coastal Georgia) |
| Employment | ~1,200 federal + ~1,866 contract employees (Federal Law Enforcement) |
Start With the Mid-Island Condo Tier
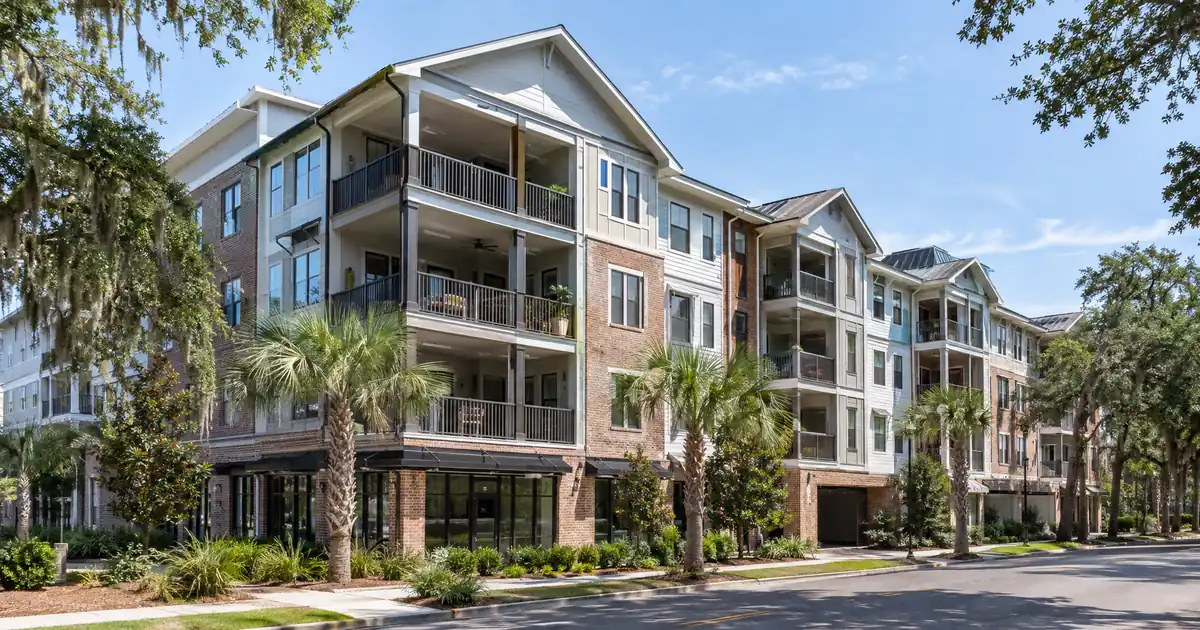
The Frederica–Demere corridor is the strongest collateral on the island for a coverage-driven refinance. Most of the island’s shopping and dining runs along those two roads. The housing stock mixes residential subdivisions with condo complexes such as Shadow Brooke Village and Barnes Plantation. Recent Redfin-listed condo sales show the price band: a two-bedroom near Redfern Village at $385,000 and a three-bedroom in the Blair Road area at $360,000, both cited in the Redfin-based market data.
Why does basis matter so much here? The rent side of the ledger does not scale with price. Sampled three-bedroom townhome and house listings in the mid-island area asked roughly $2,850 to $3,500 per month, per Zillow rentals. Those are listing samples, not medians. A $360K-to-$385K condo and a $690K house can rent for similar money. The condo carries about half the debt.
Run the numbers on a modeled mid-island condo. Assume a $385,000 value, a modeled rent of $2,600 (an assumption, not a sourced comp), and a cash-out at the 75 percent LTV ceiling. Including taxes and insurance on a 30-year amortization, coverage lands around 1.1x before HOA dues. The HOA line is what decides it. A condo that clears 1.10x on paper can slip under 1.00x once monthly dues are added. Pull the dues and confirm the complex’s rental policy before anything else.
Now the contrast case. Take a single-family home at an island-average value that sits well above the mid-island condo in the prior example, with rent at the sampled range of the higher-end listings. On full PITIA at 75 percent LTV, coverage models well below 1.00x, which is not close to qualifying. Because the value is high relative to achievable rent, the numbers do not clear the typical DSCR floor, and this structure would likely need lower leverage or a different program to work.
Sub-1.00 files are not automatically dead. A lender may review a sub-1.00 program, an interest-only structure, or lower leverage, each with tradeoffs in pricing, reserves, or required cash. Trimming leverage toward half of value pulls the top-end rent listing above 1.1x in this model. The price of that fix is obvious: proceeds shrink to a fraction of what a 75 percent cash-out would suggest. Qualification stays subject to lender guidelines, credit approval, and property review.
Sea Palms and the FLETC Tenant Pool
Sea Palms Resort, a golf-condo and townhome community on the east side, is the second-best fit. Listings there explicitly pitch units to federal trainees. One is worded as suited to “long term FLETC or shorter term rental,”.
That demand source is unusual. The Federal Law Enforcement Training Centers campus in Glynco sits on the northwestern edge of Brunswick. According to the Washington Examiner, it hosts about 68,000 students a year from 105 federal agencies, with about 3,000 on campus at any time. FLETC’s own anniversary page cites nearly 1,200 federal employees and an average of 1,866 contract employees (a 2020 vintage, so treat it as directional). Training volume is year-round. It does not follow the beach calendar.
The caveat is a real one. Trainee and instructor demand is institutional, and it depends on federal training budgets. Lenders reviewing a cash-out file want a lease or rent comp that stands on its own. Do not underwrite on a hoped-for premium.
The Workforce Case Behind the Rents
Rents on St. Simons need a tenant base that can pay them. The Golden Isles Development Authority, citing Georgia Department of Labor data, lists accommodation and food services and retail trade as the largest employment industries in Glynn County. Those wages set a ceiling on rents for workforce units.
Healthcare adds a steadier layer. Southeast Georgia Health System employs over 3,000 team members, and the authority’s profile of the system describes a 316-bed hospital with more than 300 physicians, serving six counties. Staff, travel clinicians, and FLETC-linked households support 12-month leases more reliably than seasonal hospitality work does.
One more demand signal. Sea Island Company won county approval for an 84-unit, four-story multifamily development on Sea Island Road to house employees, per First Coast News. A major employer building staff housing tells you workforce demand outruns supply. It also tells you new competing units may sit near Sea Island Road. The brief could not confirm completion status, so check before buying or refinancing nearby.
Where the Appraisal Risk Sits
The equity story splits by price tier. High-end enclaves have thin comps and visible discounts. St. Simons Island Club showed a $1,495,000 median sale price on only three sales, with an 89.7 percent sale-to-list ratio, per Coastal Georgia Real Estate Associates. The same source’s island-wide snapshot showed a $679,000 median and homes selling about 5 percent below list.
Gated luxury like that is a weak fit for a high-LTV cash-out. Appraisers have few comparable sales to lean on, and the price basis crushes coverage anyway. The sub-$700K stock closer to the workforce is the more defensible collateral.
Supply pushes the same direction. MoveWithMomentum counts 294 homes for sale, or 7.7 months of supply, against 456 sales over twelve months. Sold homes took a while to go under contract and closed below list price. That is buyer’s-market territory by the six-month rule. The figure comes from a brokerage platform, so read the direction rather than the decimal. Medians also differ by source, since Redfin, Zillow, and Momentum each reflect different methods and windows.
What does that mean for a refinance? Be honest about it. There is no appreciation tailwind to lean on. The strategic read is to underwrite the cash-out on the original purchase price plus documented improvements, and to treat any appraisal above that as a bonus. An investor who bought below market, say a condo picked up at a negotiated discount, has the best shot at a value that supports the full 75 percent.
What DSCR Files Like This Typically Look Like
DSCR files in markets like this one typically show a wide gap between headline value and rent-supported value. Borrowers anchor on the appraised number, then discover that coverage, not LTV, sets the real loan size. The stronger files arrive with a lease or rent survey in hand, the HOA dues documented, and reserves already seasoned in an account. On coastal files, getting property-level carrying costs priced before the application keeps the coverage number from moving late in review.
The Seasoning Clock and Where the Cash Goes
Most programs want about six months of ownership, measured from title recording, before a cash-out. After that, the ceiling is 75 percent of value, and coverage must still clear the 1.00x baseline, which is common because rent covers the payment at that level. Some lenders may review lower scenarios, but those usually require lower leverage, different pricing, or more cash. Reserves typically run about six months of PITIA, rising to about nine above $1,500,000. Credit tiers generally start at a 620 floor. Loan amounts go up to $3,000,000 on standard programs. All of this is eligibility guidance that varies by borrower, property, and lender, not a promise. For the mechanics, see the guide “The Refi Options” and the investor refinance breakdown.
Here is the tradeoff to weigh. On St. Simons, the proceeds are the thinnest on the highest-value homes and the most usable on condos and townhomes. A flipped strategy might run the other way: use condo proceeds as the down payment on the next coverage-positive asset, perhaps a workforce rental off the island where price-to-rent is friendlier. That last point is an inference, not sourced rent data, and the brief found nothing reliable on duplex, triplex, or fourplex inventory on the island. Do not assume multi-unit supply exists here.
Who Should Skip the Cash-Out
Skip it if the property is an island-average single-family home with no rent uplift. The coverage math fails before leverage even enters the picture. Skip it if the HOA dues eat the condo’s margin. Skip it if the plan depends on an appraisal rising above the price you paid.
The genuine toss-up is the mid-priced condo or townhome with documented rent and modest dues. Coverage near 1.1x works, but barely, and a 7.7-month supply cushion means a soft appraisal is plausible. Weigh a smaller cash-out now against waiting for a cleaner comp set. Investors with a low basis and a real lease are better positioned than those counting on price momentum, and the guide “What Is a DSCR Loan” is worth a read before sizing the ask.
The numbers that frame the island: a median near $664K to $681K, rents in the $2,850 to $3,500 range, and 294 homes chasing buyers who closed only 456 deals in a year.
Frequently Asked Questions
How does rental income affect DSCR refinance eligibility in St Simons Island?
Rental income is the core of the file, since coverage compares rent used for lender review to the full monthly obligation. Lendmire arranges DSCR investor loans, and cash-out files are capped at 75 percent LTV, subject to lender guidelines.
DSCR vs. conventional financing
Two common ways to finance an investment property in St Simons Island, GA. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
How do you qualify for a DSCR loan in St Simons Island?
The property has to show coverage at or near the 1.00x baseline, with credit typically starting at a 620 floor and reserves around six months of PITIA. On St. Simons, that usually means a condo or townhome with lower basis rather than an island-average house. HOA dues count against coverage, and eligibility depends on the lender, borrower, and property.
What are the requirements for an investment property loan in St Simons Island, Georgia?
Expect about six months of title seasoning for a cash-out, a 75 percent LTV ceiling, and reserves sized to PITIA. Manufactured homes, log homes, and barndominiums fall outside these programs, and condos need a warrantable HOA.
Does FLETC demand make a difference for a St. Simons refinance?
It helps the tenant story, not the appraisal. FLETC training volume supports year-round rental interest in Sea Palms and mid-island condos, but lenders underwrite on documented rent. A lease or rent survey carries more weight than a listing’s marketing line.
Is St. Simons in a good position for a high-LTV cash-out right now?
Not at the high end. Brokerage data shows 7.7 months of supply and sales near 95 percent of list, and thin luxury comps add appraisal risk. Sub-$700K condos with documented rent are the more defensible collateral.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349), a non-QM mortgage broker serving investors in 41 markets including Washington, D.C., helps structure DSCR scenarios commonly evaluated around a property’s rental income rather than personal income paperwork, subject to lender guidelines. Recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2025, Lendmire places loans through wholesale investor lenders and is not a direct lender.
For broader investor-financing rules and property-type coverage across the state, see Georgia DSCR loans.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin, St. Simons housing market
2. Zillow Home Value Index, Saint Simons Island
3. MoveWithMomentum, St. Simons listings
5. fletc.gov — Federal Law Enforcement Training Centers 50th Anniversary
7. Federal Law Enforcement Training Centers
9. Golden Isles Development Authority, Wages and Employment
10. Southeast Georgia Health System
11. goldenislesdev.com — Southeast Georgia Health System
12. First Coast News
13. Coastal Georgia Real Estate Associates
14. a 2026 Scotsman Guide Top Mortgage Workplace
15. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Guides: Investment Property Cash-Out Refinance in Georgia
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.