
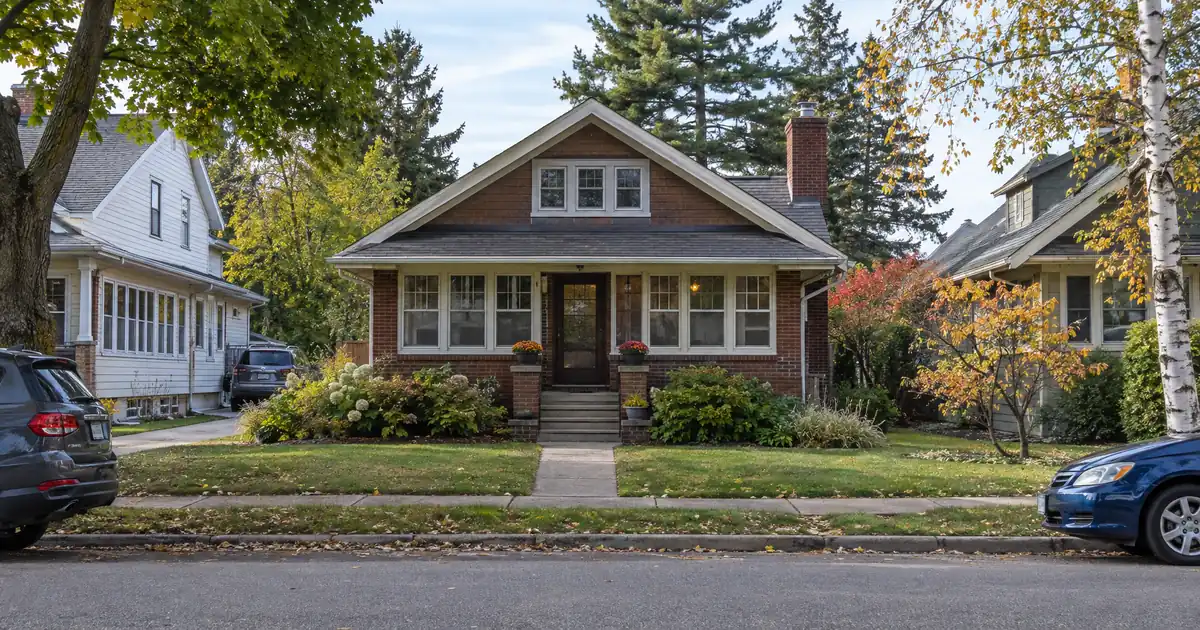
Walk the blocks around the University of Wisconsin–Stevens Point and you’ll see older Craftsman-style houses next to freshly updated rentals, and that mix is where most of the equity in this market sits. According to U.S. News, 54 percent of UWSP students live off campus, so the tenant pool is steady. The catch is that campus-area houses are often leased by the room on the academic calendar, and a cash-out refinance underwrites on the rent a lender’s appraiser will support, not on the rent you hope to collect. Stevens Point, Wisconsin investors can have DSCR scenarios reviewed through lender programs that Lendmire (NMLS# 2371349) helps place across 41 markets, including Washington, D.C. Lendmire is a DSCR-focused mortgage broker, and this piece covers pulling equity out of a property you already own.
DSCR Cash-Out Calculator
Run the cash-out numbers in Stevens Point, WI
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A cash-out refinance in Stevens Point, Wisconsin fits the investor who already holds a small multifamily or workforce rental and wants capital for the next deal. It is underwritten primarily on the property’s rental income measured against its full monthly obligation, subject to lender guidelines.
- Cash-out LTV tops out at 75 percent. Seasoning is about six months of ownership from title recording.
- Zillow puts the typical home value at $241,506, up 4.2 percent year over year.
- About 17.47 percent of housing units are duplexes or small buildings, per NeighborhoodScout.
- Student per-room leases can undercut a standard 12-month rent schedule at appraisal.
Stevens Point Market Snapshot
A quick read on the Stevens Point investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | 16 sales (Redfin housing market) |
| University enrollment | Total enrollment +3.5% (UWSP fall 2025 enrollment news) |
| Vacancy | 4.8% rental (Wikipedia (Census-derived)) |
Campus Core: Strong Demand, Awkward Underwrite
The campus-adjacent core is the strongest demand pocket in the city, and the hardest to document. UWSP enrolls roughly 8,000 to 8,500 students depending on the source (the Universities of Wisconsin profile lists 8,152, while U.S. News lists 8,522). Its most recent enrollment release reported the largest first-year class in 40 years, 2,021 students across three campuses, with total enrollment up 3.5 percent. That is a non-cyclical renter base sitting next to aging housing stock.
Off-campus listings near UWSP, Mid-State Technical College, and downtown show per-person pricing, such as a four-bedroom at $425 per person. Treat those as anecdotes, not a market median. A room-by-room lease structure can look great on a spreadsheet and thin on an appraisal rent schedule. Lenders generally want a market rent opinion that supports the lease structure, and a house rented to four students on staggered leases may get valued as a single-family rental instead.
This is a genuine toss-up for cash-out purposes. The campus core offers the most demand and the messiest documentation. Investors who convert a student house to a standard 12-month lease may find the file cleaner, though rent may land lower than the per-room total. Investors who keep per-room leases should expect the appraisal to be the swing factor.
Six Months, 75 Percent, and What’s Actually Left
The cash-out ceiling is 75 percent of value, and that is a hard cap on these programs. Seasoning runs about six months of ownership, measured from title recording. Reserves typically run around six months of PITIA, and credit tiers generally step up from a 620 floor, all subject to lender guidelines. See pulling equity with a DSCR cash-out for how those pieces fit together.
Here’s the part investors skip: the equity you can access is a function of the appraisal, not your purchase story. Stevens Point sales volume is thin, so comps are limited. Zillow shows a modest, believable 4.2 percent annual gain. Redfin once showed a median sale price near $284,000 on only 16 sales, a sample too small to call a trend. Sizing a refinance on an assumed double-digit appreciation lift is the wrong move. Lean toward flat-to-low-single-digit growth, and treat any bump beyond that as a bonus.
Value-add buyers face a second wrinkle. A city housing study by MSA Professional Services described an overabundance of low-quality homes that owners aren’t improving. If the plan is to buy a tired duplex, renovate, and refinance, the after-repair value needs a conservative estimate, because condition drives appraisal risk in an older stock.
Run the Numbers on a Duplex
The math below uses modeled assumptions, not sourced market figures: a duplex valued at $300,000, refinanced at 75 percent LTV, with a 30-year term and full PITIA including taxes and insurance. Rents use listing-aggregator averages from ApartmentFinder, which shows $1,052 for a two-bedroom and $1,395 for a three-bedroom.
| Rent structure | Modeled gross rent | Approx. coverage |
|---|---|---|
| Two 2BR units | $2,104 | About 1.05x |
| Two 3BR units | $2,790 | About 1.35x |
| Two 2BR at lower comps | $1,978 | Near 1.00x |
The bottom row uses the $989 two-bedroom figure from Apartments.com. The spread between rows is the whole story. A three-bedroom-heavy duplex clears the 1.00x baseline with cushion, while a two-bedroom version sits near the line. If a scenario slips below 1.00x, a lender may review options such as a sub-1.00 program or reduced leverage, with eligibility depending on credit, reserves, and property review.
DSCR files in markets like this one typically look the same on paper: a small building with two to four units, a handful of long-term leases, and rents that land below the marketing averages once the appraiser’s schedule comes in. The cleanest files from a documentation standpoint arrive with signed leases, entity documents, title, and current insurance quotes already assembled. The gap between an advertised rent and a supported rent is where most cash-out sizing surprises come from.
Investors with a single rental, strong traditional employment income, and a clean tax return may find conventional financing cheaper, so the guide “Where DSCR and Conventional Diverge” is worth reading first. DSCR usually earns its place for entity-held or self-employed borrowers, and for anyone stacking multiple financed properties. DSCR programs anchor on the property itself. LLC-titled properties are reviewed subject to lender program eligibility.
Small Buildings Are the Collateral
Small-building stock is what makes this a workable cash-out market. NeighborhoodScout puts single-family detached at 50.05 percent of units, large apartment complexes at 26.18 percent, and duplexes, converted homes, and small buildings at 17.47 percent. RentCafe reports that 49 percent of residents rent and 77 percent of rentals sit in complexes under 50 units, so this is a small-landlord town. About one in six units is a candidate for two-to-four-unit collateral, though that figure is a third-party estimate worth checking against the MLS.
The house-versus-apartment gap matters too. Zumper’s outlier data shows houses about $500 per month above apartments, which is why a fully leased small building can stack more gross rent than a single-family home. Apartments.com shows a lower range, so underwrite to the low end.
Sentry Insurance sits under all of this. Its headquarters renovation announcement describes an 800,000-square-foot project over roughly 40 months, and the company’s careers page cites about 2,500 local associates. Sentry and UWSP top the Portage County Business Council list of major employers. Add Aspirus, a system of 18 hospitals and nearly 14,000 team members that runs the Stevens Point hospital, and you get a tight cluster of employers that favors in-city rentals.
Plover and the North Side
Workforce single-family is the quieter play. Plover, the county’s second-largest municipality, draws food-processing and manufacturing tenants tied to employers like Monogram Foods and Basic American Foods. Source descriptions also say the more affordable homes in Stevens Point itself sit toward the north, while the desirable areas skew southeast, including Park Ridge. Neither claim comes with verified dollar figures, so these are directional only.
A three-bedroom workforce house at the ApartmentFinder rent of $1,395 is a single-unit story. It rarely produces the coverage cushion a duplex does, so it fits best as a hold with modest cash-out ambitions.
Downtown: Watch the Rent Ceiling
Downtown and the riverfront carry a supply risk. North Side Yard added 159 units, studios through two-bedrooms, near the Wisconsin River trail, and Oaks on Maria is a new apartment community scheduled to open. New-build apartments cap rents on older small multifamily nearby. Check the pipeline near any target before you set the refinance rent (this is the step people skip).
What Doesn’t Pencil
The Clark Street–Main Street Historic District east of downtown is owner-occupant territory with historic homes. It is likely thin for DSCR yield, though no price data supports a firm call. Skip it for cash-flow refinances.
Student-only room rentals also don’t suit standard 12-month rent schedules, as covered above. Manufactured homes, log homes, and barndominiums fall outside these programs entirely.
Budget for taxes and insurance, which vary by property. Verify current local rental rules, taxes, and insurance with qualified local professionals. For refinance mechanics beyond cash-out, look into the investor refinance options available, and Wisconsin DSCR investor loans covers the state picture. When you’re ready, run the numbers with Lendmire or call 828-256-2183.
Stevens Point vs. the Neighbors
Wausau and Wisconsin Rapids generally lack a four-year anchor of UWSP’s scale (that comparison is a framing, not a sourced ranking). Right now the math favors Stevens Point for a cash-out on a small building: a growing university, a headquarters-scale insurer, and a hospital system produce steadier tenant demand. Keep the duplex, size to the low-end rent, and don’t lean on appreciation.
DSCR vs. conventional financing
Two common ways to finance an investment property in Stevens Point, WI. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR loan in Stevens Point, Wisconsin?
Qualification centers on the property’s rent compared with its full monthly obligation, with 1.00x a common baseline. Pricing and available terms vary by lender, borrower profile, property type, and full underwriting review. Eligibility depends on lender guidelines, credit profile, and how the qualification works for your specific property.
What are the requirements for an investment property cash-out refinance in Stevens Point?
Expect a 75 percent LTV ceiling, about six months of ownership from title recording, and rent that supports the coverage number. Loan sizes run up to $3,000,000 on standard programs. The cash you can pull depends on appraisal, reserves, and coverage, not a set figure.
Will student per-room leases work for a Stevens Point DSCR refinance?
Sometimes, but they add risk. Appraisers want a market rent supporting the lease structure, and per-room totals can exceed what a 12-month schedule would show.
Can an LLC-owned Stevens Point rental be reviewed for DSCR financing?
Yes, subject to lender program eligibility. Lendmire arranges DSCR investor loans and a common feature is that review centers on property rental income rather than personal income.
Does Stevens Point’s thin sales volume affect cash-out sizing?
Yes, it can. With few closed sales, comps are limited and appraisals can come in conservative. Size the refinance to a flat-to-modest appreciation assumption and don’t count on a double-digit value lift.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income rather than personal income, subject to lender and program guidelines, which suits self-employed investors and LLC-owned portfolios. Lendmire was recognized as a 2025 Scotsman Guide Top Workplace and a top-ranked workplace in 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Home Values, Stevens Point
2. NeighborhoodScout, Stevens Point
3. Redfin
8. Sentry Insurance headquarters renovation
9. jobs.sentry.com — Locations Stevens Point
10. Portage County Business Council
12. a 2025 Scotsman Guide Top Workplace
13. Scotsman Guide — Top Workplaces 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance Stevens Point Wisconsin · DSCR Cash Out Refinance Oshkosh Wisconsin · Cash Out Refinance Investment Property in Oshkosh WI
Guides: Investment Property Cash-Out Refinance in Wisconsin
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.