
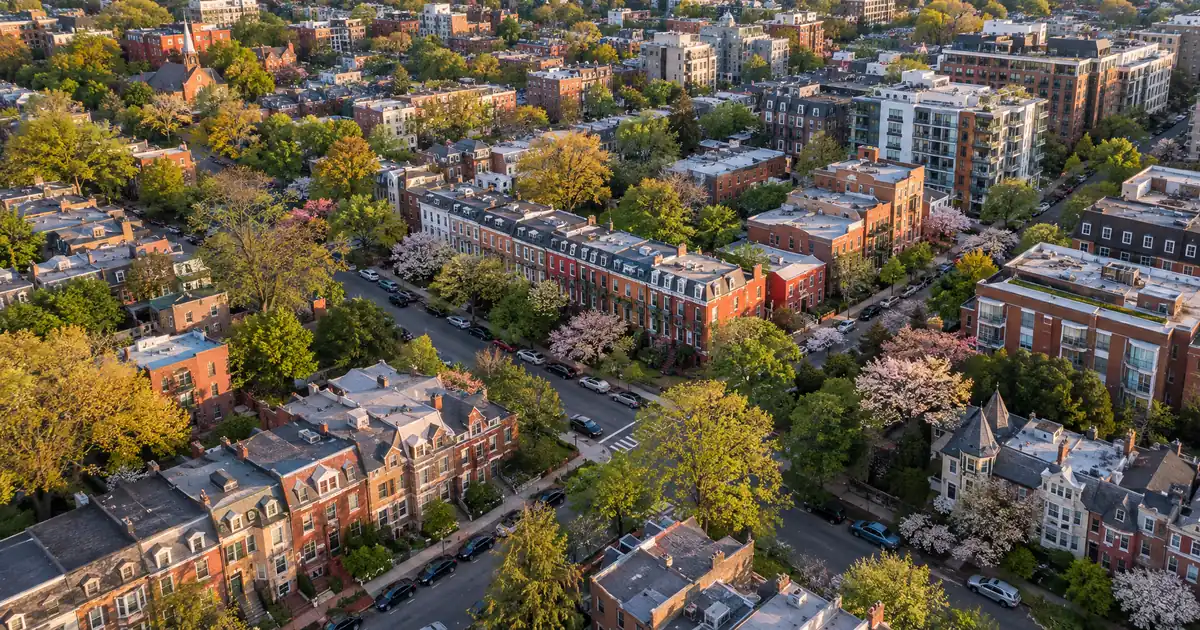
An out-of-state owner scanning a cash out refinance investment property play in Washington, District of Columbia, sees a city that looks expensive and stable at once. Redfin shows a three-month median price of $684K, essentially flat year over year, with homes sitting about 57 days. That headline reads like a market where equity is easy to pull. What the headline hides is the gap between rowhouses that carry a second income stream and single-unit houses that don’t come close to covering a new, larger loan. Here’s where that gap sits, and what to ask before ordering an appraisal.
DSCR Cash-Out Calculator
Run the cash-out numbers in Washington, US
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A cash-out refinance on a Washington, District of Columbia rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with the loan capped at 75 percent of appraised value, about six months of title seasoning, and reserves documented, all subject to lender guidelines.
- Petworth rowhouses with a separate basement unit can stack roughly $5,100 in modeled monthly asking rent.
- Single-unit rowhouses near $600K and up are the tightest coverage files in the city.
- Observed District rents fell 4.4 percent, so size proceeds to today’s rent.
- Appraisal risk rises east of the river, where comps are thinner.
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker with investor loan programs across 41 markets, Washington, D.C. included. It arranges these files through wholesale lending channels, and lenders make the eligibility decisions. Investors can reach the team at 828-256-2183 to talk through a specific rowhouse.
Washington Market Snapshot
A quick read on the Washington investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | 1,821 sales (Redfin DC housing market) |
| Typical rents | Petworth ~$1,707 (Nomadic Real Estate DC) |
| University enrollment | ~2,796 new students (Howard Magazine) |
| Employment | 8.9% health-care jobs (possibly stale) (dmped.dc.gov — Higher Education and Healthcare) |
| Vacancy | 4.70% (Matthews Q2 2026 DC Multifamily) |
Underwrite Today’s Rent, Not Next Year’s
Rents in the District are softer, not stronger, and the cash-out should be sized to that reality. Brookings found observed rents fell most in the District, by 4.4 percent, ahead of Arlington County at 3.6 percent. RentCafe puts average apartment rent at $2,447, down 3.38 percent year over year.
Two cautions come with those figures. RentCafe’s numbers are apartment averages from larger buildings, so they don’t map to rowhouse rents. And the regional picture from Matthews (regional, not District-only) shows employment contracting 2.9 percent in the prior year, with vacancy at 4.70 percent and average rent near $2,227.
Federal employment is the swing variable. The city itself added 2,335 residents in its latest estimate, reaching 693,645, per the DC Office of Planning. That’s a stable base, not a surge.
The practical rule for a refinance: don’t reach coverage by assuming rent growth. If the file only clears 1.00 with a rent bump baked in, the file is telling the investor to borrow less.
The Petworth Stack
The best cash-out candidates in the District are rowhouses that already hold two legal rental units. Petworth is the clearest example. RentHop’s listing data shows asking rents near $1,839 for a 1BR, $2,750 for a 2BR, and $3,300 for a 3BR. Redfin shows an average Petworth house price of $764K, up 7.2 percent year over year, though other aggregators show the neighborhood moving the other way. Treat the direction as unsettled.
Run the numbers on a hypothetical rowhouse valued around $764K. Model a 3BR upper unit at $3,300 and a 1BR English basement at about $1,800, which comes to roughly $5,100 a month. Those are modeled assumptions built from asking rents, not leases. Refinanced at 75 percent LTV and measured against full PITIA (principal, interest, taxes, and insurance), that stack lands around 1.1x. Haircut the asking rents by 10 percent and the number drifts toward 1.0x, which is the standard baseline many programs build around.
Compare that with the same house rented as a single 4BR unit. Even at the 3BR asking rent alone, coverage falls well under 1.0x.
The basement unit only helps if a lender and appraiser can count it. A separate Certificate of Occupancy is what makes the second unit real for underwriting purposes, so confirm it before anything else. RentCafe reports that 65 percent of Petworth apartments sit in complexes under 50 units and just 3 percent are single-family rentals, which suggests small-scale rentals are the norm there and tenants are used to the format.
Tenant demand in Petworth leans on teachers, healthcare workers, and mid-career professionals, per Nomadic Real Estate, and the Green Line plus a walkable Georgia Avenue support it.
Where Single-Unit Rowhouses Run Out of Room
Single-unit rowhouses above roughly $600K are where a cash-out most often stalls. RentalCalcs models a Petworth or Brookland rowhouse at that price with renovated rents at a net cap rate near 3.8 to 4.5 percent. That is a modeled estimate, not observed data. A yield in that band generally doesn’t cover full PITIA on a refinance at 75 percent LTV, even before reserves.
Brookland is a good example. Speicher Group puts it near $790,000, nearly double its price a decade ago. The tenant mix is real: Catholic University of America is nearby, and MedStar Washington Hospital Center draws healthcare renters. But appreciation in Brookland has outrun rent, which is the classic sign of an appreciation-led asset rather than a cash-flow-led one.
Capitol Hill and Georgetown are tighter still. Capitol Hill townhomes clear seven figures, and RentalCalcs says a $1.3M detached Georgetown house yields under 4 percent gross. For those owners, the refinance depends on the appraisal, not the rent roll.
If a single-unit file lands under 1.00 on long-term rent alone, the options a lender would review include a sub-1.00 program, interest-only restructuring, or a lower loan amount. All of them come with tradeoffs, and eligibility depends on lender guidelines, credit approval, and property review. A sub-1.00 structure is defensible when the property has a genuine appreciation story or a clear path to adding a unit. It’s a warning sign when it’s the only way a $600K-plus single-unit house works at any neighborhood the investor is considering.
Columbia Heights and the Roommate Market
Columbia Heights is the cautionary tale for anyone assuming a dense, transit-rich neighborhood guarantees a clean appraisal. Redfin shows an average house price of $598K, down 14.6 percent year over year, with homes taking about 98 days to sell.
That’s a soft comp environment. An owner who bought before the softness might find the appraisal doesn’t support the proceeds expected. Rent signals are stronger in the urban core than in outer neighborhoods, since young professionals and roommate households form the tenant base. But the refinance still hinges on comps, not tenant quality.
East of the River: Better Coverage, Thinner Comps
Anacostia and the surrounding Southeast neighborhoods are where coverage math improves and appraisal risk grows. Speicher Group puts a Victorian in Anacostia near $485,000. RentalCalcs models a rowhouse bought below $500K at 6.5 to 7 percent gross yield with market-rate tenants and steady occupancy. That is a modeled figure, and the tradeoffs are longer holds and heavier management.
The cash-out thesis differs from Petworth’s. Lower basis means rent covers debt service with more cushion, so the coverage number rarely limits the loan. The appraisal does. Local investor-agent marketing describes Wards 7 and 8 as places that “frequently produce below-market entry points,” and that same quality means fewer recent comparable sales and a narrower buyer pool. A conservative approach targets a loan comfortably below the 75 percent ceiling.
Seasoning, the 75 Percent Cap, and Reserves
Cash-out eligibility rests on a handful of guardrails. Most programs look for about six months of ownership measured from title recording, and the ceiling for a cash-out is 75 percent LTV, lower than the purchase limit. Credit tiers generally start at a 620 floor and step up through 660, 680, and 700, with better tiers typically improving leverage and terms. Reserves generally run about six months of PITIA, and roughly nine months on balances above $1,500,000. Loan amounts on standard programs go up to $3,000,000, subject to lender guidelines. How much equity is actually available depends on rent used for lender review, PITIA, reserves, and that 75 percent ceiling. It is never a guaranteed figure.
The investor’s own holding structure matters too. LLC-titled rowhouses are common here, subject to lender program eligibility. For entity-owned portfolios and self-employed owners whose traditional personal-income documentation doesn’t show rental income cleanly, Lendmire’s DSCR guide explains why underwriting on property income can be the cleaner path. Conventional financing may still be the better call for an owner with one rental and strong traditional employment income who wants a lower cost of capital and doesn’t need the entity structure. The key differences come down to how many financed properties the investor holds and whether personal income documents the deal well.
One pattern shows up repeatedly on files from dense, high-basis markets like this one. The cleaner files tend to arrive with a lease or rent schedule for each unit, the certificate of occupancy already in hand, and a realistic view of the appraiser’s likely comps. The common friction point is a second unit that exists physically but not on paper, which leaves rent used for lender review a fraction of what the owner expected.
For a broader look at structuring the exit and the use of proceeds, see the guide “The Refi Options” and Lendmire’s refi programs.
Values Have Held. Comps May Not.
Metro-wide, values have held better than the headlines suggest. The Richmond Fed found 19 percent of DC-metro listings had price cuts, against 21 percent nationally, and the gap has narrowed from 5 points to 2. Metro median list prices are down about 2 percent since two years earlier, while median sale prices are up 12 percent.
Neighborhood detail matters more than the metro average. The Center for Washington Area Studies found neighborhoods with an above-median federal-worker share were more likely to see more homes listed for sale between two consecutive years. That’s a hint that comps in federal-heavy areas may soften first.
This one’s a genuine toss-up. Metro numbers argue for confidence in an appraisal-based cash-out, while the neighborhood numbers argue for a value cushion. Building that cushion into the target LTV, and expecting longer marketing times on comparable sales, is the reasonable middle path.
Class C Is Holding Better Than Luxury
Workforce-priced product is the safer rent assumption in the District. Chase, citing Moody’s data, reports luxury multifamily vacancy at 11.9 percent against 7.9 percent for B and C class. Northmarq found that the region’s most affordable submarkets were the main exception to broad vacancy increases, and they still posted rent gains.
Supply helps at the margin. Matthews shows units under construction at 13,143, or 1.86 percent of inventory, against a 5.35 percent peak. Navy Yard and Capitol Hill South is the named oversupply pocket, with vacancy in the 6 percent band per Marcus & Millichap. Tenants there have concession-heavy alternatives, so don’t count on a high rent near the new towers.
Demand Anchors
Hospitals first. MedStar Health runs 300+ care locations, including 10 hospitals, and MedStar Washington Hospital Center is the largest hospital in the city. Howard University received a record 36,393 applications for fall enrollment, per Howard Magazine. Add DMPED‘s count of more than 180 embassies and foreign councils, plus the World Bank, IMF, and Inter-American Development Bank, and the tenant profile is unusually diverse for a single jurisdiction.
None of that guarantees rent growth. It does support occupancy, which is what a lender ultimately cares about.
DSCR vs. conventional financing
Two common ways to finance an investment property in Washington, DC. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What Would Break the Pattern
Three indicators matter over the next 6 to 24 months. First, federal employment: if the contraction deepens, expect rents to soften further and appraisers to lean on weaker comps. Second, the delivery pipeline: a thin slate supports rent floors outside the new-tower corridors, but a rebound in construction would change that. Third, listing pressure in federal-heavy neighborhoods, which is where value softness would show up first.
The math favors two-unit rowhouses today, but an investor planning to hold through a further federal downturn should stress-test coverage at a rent 10 percent below asking. Verify current local rental rules, taxes, and insurance with qualified local professionals before committing.
The Asymmetry Is Two Legal Units on One Rowhouse
The most underpriced setup in the District, relative to its rent and demand fundamentals, is the Petworth rowhouse with a separately permitted basement unit. It carries roughly 1.5 times the rent of a comparable single-unit house on the same lot, sits near the Green Line and major hospital and university employers, and can be refinanced at 75 percent LTV without needing rent growth to clear 1.0x.
Frequently Asked Questions
How do you qualify for a cash-out refinance on a DSCR loan in Washington, DC?
The property’s rent used for lender review has to cover its full monthly obligation (principal, interest, taxes, insurance, and any HOA dues), with 1.00 the common baseline. Pricing and available terms vary by lender, borrower profile, property type, and full underwriting review. Eligibility depends on lender guidelines, credit approval, and property review.
What are the requirements for an investment property loan in Washington, DC, if the rowhouse has a basement unit?
The second unit has to be documented and countable, which usually means a separate Certificate of Occupancy and a lease or market rent schedule for each unit. Without that paperwork, rent used for program review may reflect only the main unit, which can leave coverage under 1.00. Confirm the paperwork early.
Can a single-unit Capitol Hill or Georgetown house work for a DSCR cash-out?
Rarely at standard coverage. High-priced Hill and Georgetown product yields under 4 percent gross in the priciest tiers, so the refinance depends more on the appraisal than the rent. Investors sometimes review a lower loan amount or a sub-1.00 structure, though both reduce proceeds and come with tradeoffs.
Does the 75 percent cap create appraisal risk east of the river?
Yes, because comps are thinner in Wards 7 and 8. A house priced well can still appraise light if few similar sales closed recently, and the 75 percent cap applies to appraised value, not purchase price. Targeting a loan below the ceiling protects the file.
How does DSCR eligibility review differ from a bank’s approach in Washington?
Lendmire arranges DSCR investor loans and lenders review the file primarily on the property’s rental income rather than traditional personal-income documentation. That can suit LLC-titled portfolios and self-employed owners, though all scenarios remain subject to the lender’s review and program guidelines.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income rather than the borrower’s W-2 history, which makes it a practical fit for LLC-titled portfolios and self-employed investors. All scenarios remain subject to financing review and program guidelines. The firm has been recognized by Scotsman Guide as a 2026 Top Workplace and recognized by Scotsman Guide in 2025 as a Top Mortgage Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin: Washington, DC housing market
4. dmped.dc.gov — Higher Education and Healthcare
5. Matthews: DC multifamily market report
6. Brookings: DMV housing market on the precipice
7. RentCafe
9. Redfin
10. RentCafe
11. Speicher Group
12. Redfin
13. Richmond Fed: DC metro housing update
14. Center for Washington Area Studies
15. Northmarq: DC multifamily report
16. medstarhealth.org — Facts and Figures
17. DMPED: sectors
18. recognized by Scotsman Guide as a 2026 Top Workplace
19. recognized by Scotsman Guide in 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Loans in Washington DC: Investor Financing for Capitol Hill, Columbia Heights, Petworth & Real Estate Investors · DSCR Loans in Bellingham, Washington: Investor Financing for Fairhaven, Barkley, the Whatcom County Rental Market & Real Estate Investors · DSCR Loans Washington DC: Investor Financing for Capitol Hill, Northern Virginia, Maryland, and Real Estate Investors
Guides: Investment Property Cash-Out Refinance in Washington, D.C.
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.