How To Finance An Estate On Acreage With A Super Jumbo Bank Statement Loan
A super jumbo bank statement loan solves the first problem by qualifying on deposits instead of tax returns.

A super jumbo bank statement loan solves the first problem by qualifying on deposits instead of tax returns.
Twenty-Acre Property Qualify For A Super Jumbo — Usually not as a single twenty-acre collateral parcel.
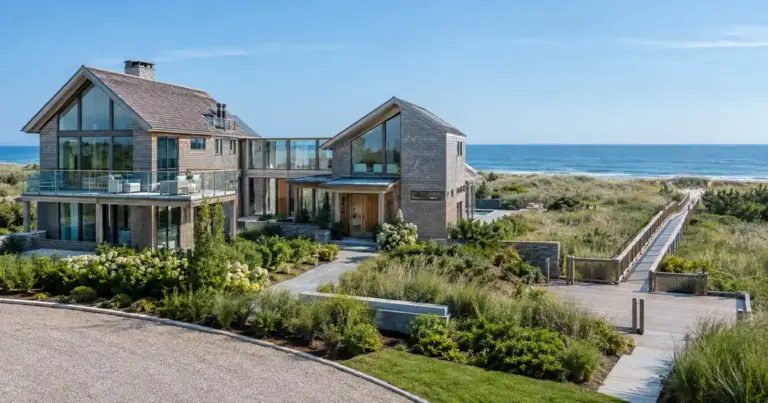
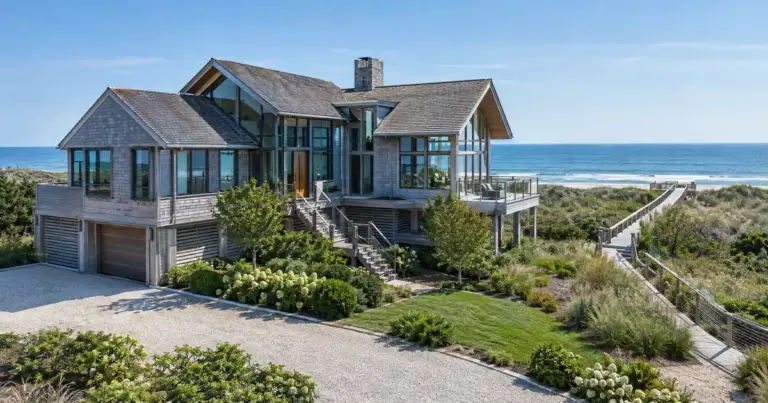
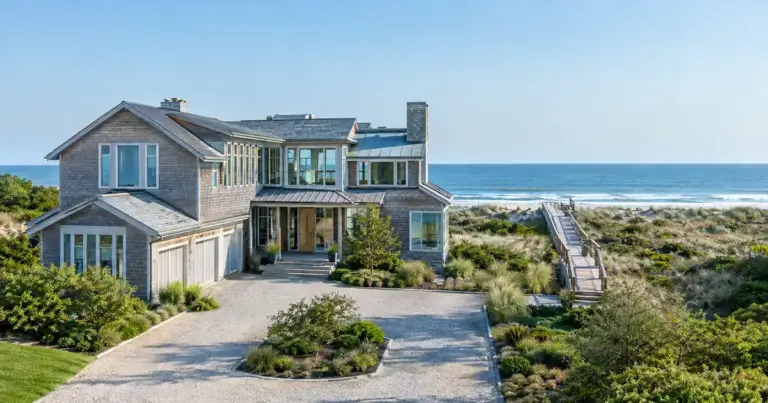
Finance An Estate On Acreage With A Super — Buying a large estate on acreage usually means stepping outside conventional lending entirely.
Twenty-acre Estate Qualify For A Super Jumbo — Generally, no — not with the full twenty acres counted as collateral.
Does One Declining Year End A CPA P&L Loan Application — No.
Can A Minority Owner Qualify For A Super Jumbo Bank Statement Loan — Yes, but the math changes below 25% ownership.
At a Glance: Asset-based borrowers navigate a second-home appraisal by treating it purely as a value check—no rent schedule, no coverage-ratio math—while
Can An HOA With Pending Litigation Still Close A Bank Statement Condo Loan — Usually, yes.
How A Luxury Second-home Loan Appraisal Is Read By The Desk Reviewer — A desk reviewer never visits the property.
Can An IRA Or 401(k) Satisfy Reserves On A Bank Statement Second Home Loan — Yes, but not at full face value.
Business Under Two Years Old Support — Yes, in many cases, but “two years” is an industry habit, not a federal rule.
Use Retirement Accounts For Reserves — Retirement funds usually count toward reserves at a discount, not full value.
Young Shopify Or Amazon Business Qualify — Generally, no — not on a true P&L-only basis.
Most programs apply a haircut — a discount that reflects taxes, early-withdrawal penalties, and limited access to the money.
Above a certain loan size, a second valuation product often gets layered on, and the lower number — never an average — controls how much gets financed.