Super Jumbo Bank Statement Loans In Bar Harbor
Leverage steps down as the loan gets bigger, and every file above $4 million gets a case-by-case look before it’s even submitted.

Leverage steps down as the loan gets bigger, and every file above $4 million gets a case-by-case look before it’s even submitted.
Not every asset counts, and the ones that do often count at a discount.
Terms vary by lender guidelines, property type, leverage, credit profile, and full file review. Nothing here changes based on zip code.
Financing A Second Home In Camden On Bank Statements: what borrowers need to know about high-net-worth bank-statement financing, from Lendmire.
Bank Statement Loans In Bethesda — A super jumbo bank statement loan qualifies a self-employed borrower using 12 or 24 months of deposits
Above $4,000,000, every file gets reviewed case by case before it goes to a lender at all.
Above roughly $4,000,000, every file gets reviewed case by case before submission.
Lenders decide occupancy first — primary, second home, or investment property — and only then look at how income gets documented.
Asset Depletion Loans In Bethany Beach: Qualifying On Assets Alone — what borrowers need to know, from Lendmire.
The mechanics work the same way for a retiree in Bethesda as anywhere else in the country — location doesn’t change the math.
Size, credit, and cash reserves do more work at this level than almost anything else in the file.
Get the classification right first, then the paperwork gets easy.
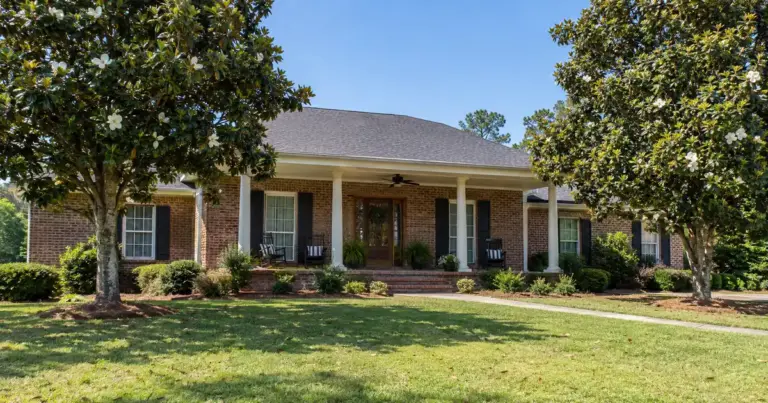
Asset Depletion Mortgages In Alabama — Asset depletion turns liquid holdings into qualifying income instead of tax returns or pay stubs.
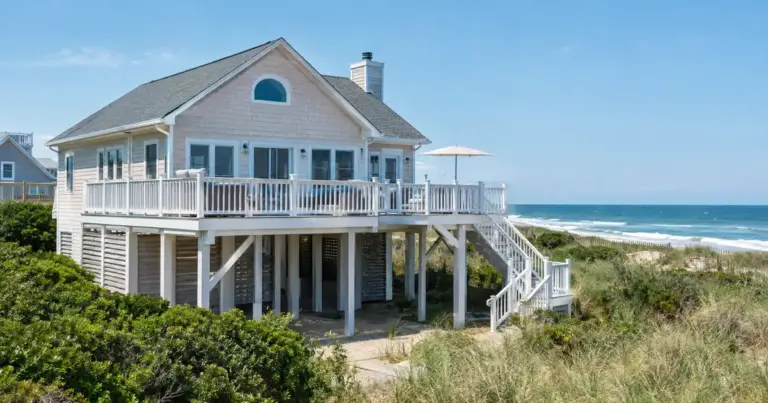
It exists for people who have real wealth but thin tax-return income: retirees, business owners, recent business sellers. Nothing gets sold or spent.
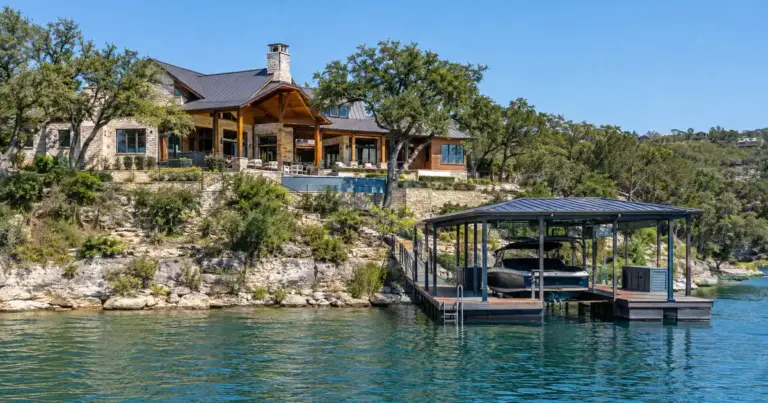
The two products solve different problems, and mixing them up is the single most common way a self-employed buyer’s file stalls mid-transaction.