Asset Depletion Mortgages In Bonita Springs: Assets, Not Income
A lender takes eligible accounts, applies a divisor, and produces a monthly number that stands in for a paycheck.

A lender takes eligible accounts, applies a divisor, and produces a monthly number that stands in for a paycheck.
Bank statement lending lets a self-employed buyer qualify on 12 or 24 months of deposits instead of tax returns.
Asset Depletion Mortgages In Fort Lauderdale: Assets, Not Income: what borrowers need to know about high-net-worth bank-statement financing, from Lendmire.
The occupancy label a buyer signs at closing determines which loan family even applies, long before credit score or down payment enter the conversation.
Asset Depletion Mortgages In Winter Park — These loans let a borrower qualify on liquid assets instead of tax returns or pay stubs.
Asset Qualifier Mortgages In Windermere — these loans let a retiree qualify using liquid assets instead of a paycheck.
A lender turns your account balances into a monthly income figure, then measures that figure against the proposed housing payment.
A lender takes a portion of your checking, brokerage, and retirement balances and turns it into a hypothetical monthly income figure.
The size of the purchase, your credit profile, and how the property will actually be used all shape which leverage tier and documentation path apply.
It’s a real, fully underwritten non-QM product — not a shortcut around verification.
A lender totals eligible assets, applies haircuts by asset type, subtracts funds needed for the deal, and divides what’s left by a set number of months.
Leverage and pricing shift with loan size, occupancy type, and credit score.
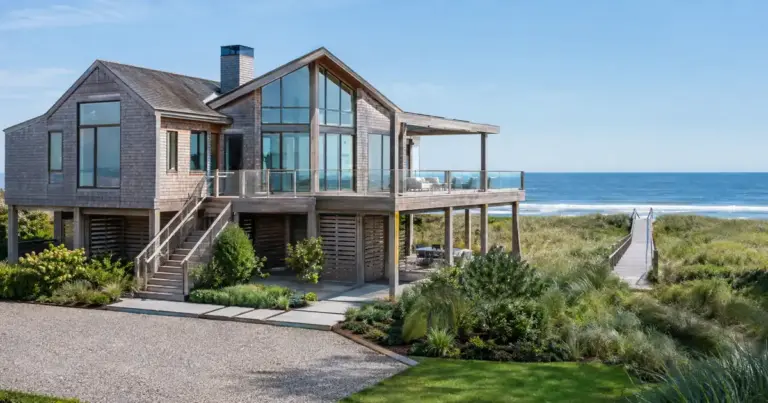
Every file above $4,000,000 gets a case-by-case review before it’s submitted, and leverage steps down in stages as the loan amount rises.
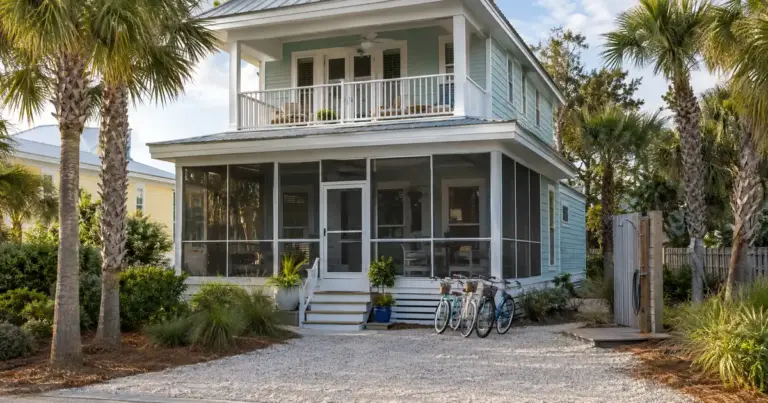
The property’s occupancy — second home versus rental — changes the leverage and credit floor you’ll be offered.
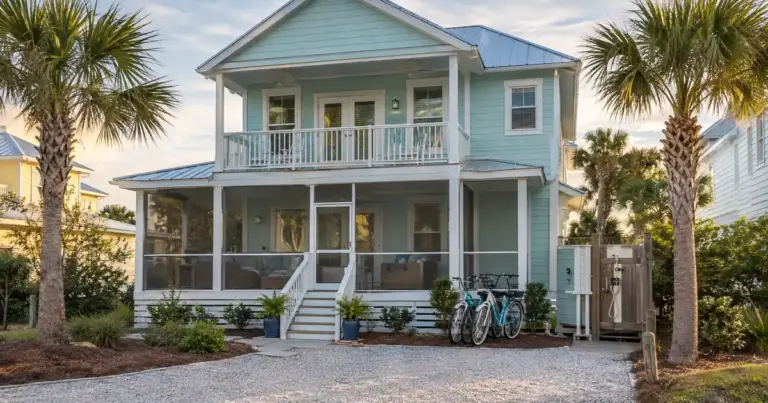
Occupancy, not the borrower’s overall investor status, decides whether that path even applies.