Asset Depletion Loans In Clearwater Beach: Qualifying On Assets Alone
A lender divides eligible assets by a set number of months, and the result stands in for monthly income on the loan application.

A lender divides eligible assets by a set number of months, and the result stands in for monthly income on the loan application.
There’s no federal definition of “super jumbo” — every lender in this space draws that line differently.
The property type — second home versus investment property — decides which loan program even applies.
Qualification runs on bank deposits or liquid assets instead of W-2s and tax returns.
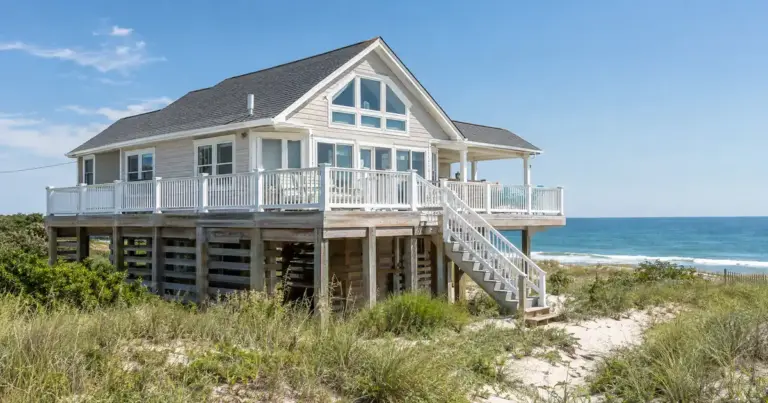
It exists so an asset-rich, income-light borrower can qualify without W-2s or tax returns.
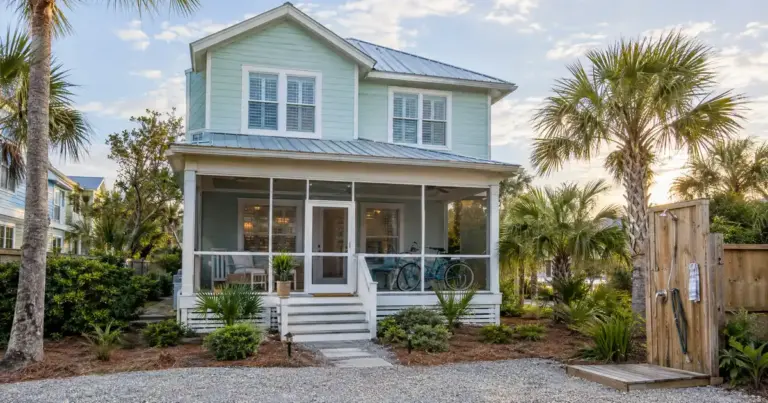
This matters more for business owners than for W-2 buyers.
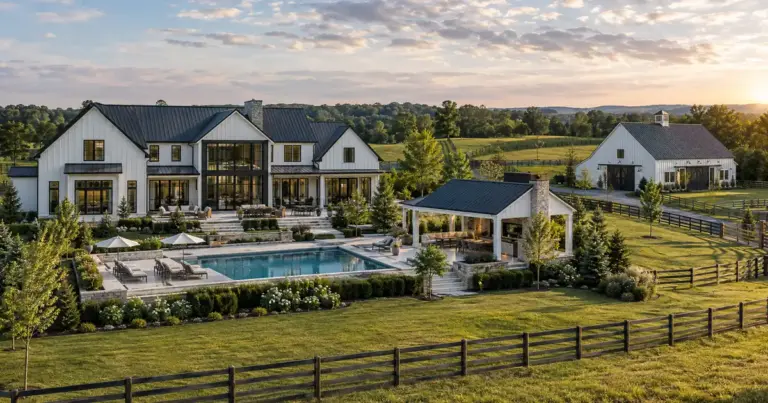
Asset Depletion Loans In Destin — An asset depletion loan lets a borrower qualify using liquid assets instead of a paycheck.
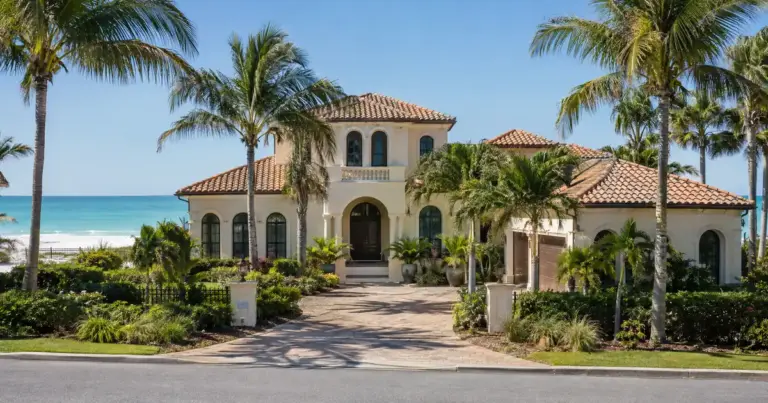
Asset Qualifier Mortgages In Siesta Key — A retiree buying a home in a waterfront market doesn’t need a paycheck to qualify.
The property still has to qualify as a true second home — one-unit, personally used part of the year, not handed to a rental pool.
Bank statement financing solves this by qualifying the borrower’s own cash flow instead of tax returns.
Leverage steps down as the loan gets bigger, reserves step up, and above roughly $3.5-4 million almost everything gets reviewed file by file.
Qualification always runs through full underwriting, subject to lender guidelines — there’s no guaranteed approval just because the assets are there.
It works well for self-employed buyers whose returns understate real income.
It works almost exclusively for a primary residence or second home, not a rental purchase.
Documentation is one decision and occupancy is a separate one — a lender looks at both independently before pricing the file.