Do P&L Loan Reserves Scale With The Size Of The Loan?
P&L Loan Reserves Scale With The Size Of The Loan — Yes, reserve requirements generally step up as the loan amount grows.

P&L Loan Reserves Scale With The Size Of The Loan — Yes, reserve requirements generally step up as the loan amount grows.
Asset Depletion Mortgage Counts Undistributed K-1 Income — It doesn’t.
Ownership of at least 25% is typically required to use those statements at all, and money you move into your own personal account counts in full.
A 24-month lookback usually wins when income is steady or seasonal, because it proves a longer track record to underwriting.
Neither window is “safer” by default.
Can One Declining Year Of Deposits Kill A Bank Statement Loan? — No, one declining year doesn’t automatically sink a bank statement loan.
Expense Factor Replace A CPA Letter — No. The expense factor is a lender’s automatic assumption about your business costs.
Bank statement loans sidestep the K-1 entirely and qualify you off deposits into a business or personal account instead.
That reset date isn’t a rate tweak — it’s a switch from an interest-only payment to a fully amortizing one over whatever term is left.
Meet Reserves By Loan Size — On a super jumbo purchase, reserves climb in steps as the loan gets bigger — not in a straight line.
Sizing, down payment, and documentation all shift once the property carries a condotel label, so the planning has to start there, not at the offer stage.
How To Structure Interest-only On A Bank Statement Resort Loan: what borrowers need to know about high-net-worth bank-statement financing, from Lendmire.
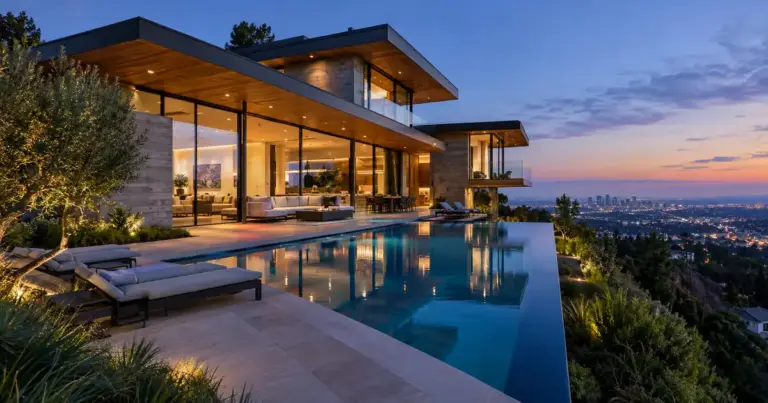
Can A Second Home Buyer Get Full Financing On Asset Depletion: what borrowers need to know about high-net-worth bank-statement financing, from Lendmire.
Plan Reserves On An Asset Depletion Second Home — Reserves come out of the asset pool before the income math runs, not after.
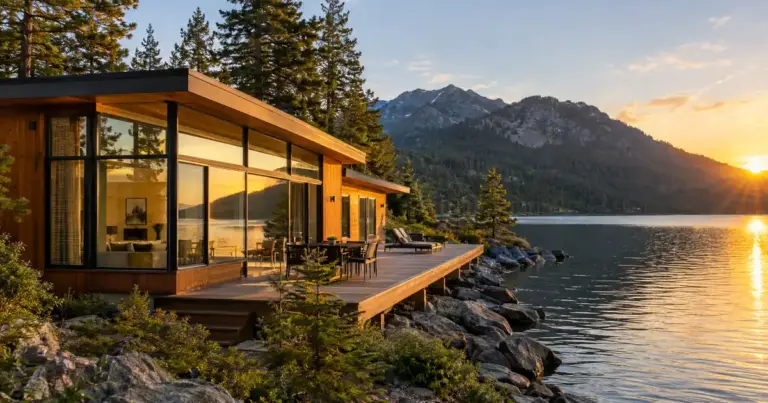
Use A Bank Statement Loan — Yes, you can use a bank statement loan to buy or refinance a second home.