Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island
Jersey Shore Vacation Rental Loans — These are DSCR loans built around a property’s rental income instead of your W-2 or tax returns.

Jersey Shore Vacation Rental Loans — These are DSCR loans built around a property’s rental income instead of your W-2 or tax returns.
Shore towns and city condos get treated very differently underneath the same DSCR math.
Neither “jumbo” nor “super jumbo” is a federal category. There’s no agency line that draws it.
Big banks and agency lenders won’t touch them, because Fannie Mae specifically excludes hotel-operated projects from its buying rules.
This is the mechanism behind most DSCR loans on Airbnb and Vrbo properties, and it decides how much leverage an investor gets.
On a short-term rental, that can be the difference between a file that dies at 0.94x and one that clears 1.00x.
How To Reconcile Two Appraisals On A Luxury Short-term Rental DSCR Loan — Reconciling two appraisals never means averaging them.
A great booking history doesn’t matter if the HOA won’t allow the rental plan. The questionnaire and the DSCR income calculation run on separate tracks.
The entity needs to be state-chartered, EIN-issued, and documented with an operating agreement before the lender clears the file to close.
Two separate reviews decide the file: a building screen, then a borrower screen. Miss either one and the deal stalls.
Here’s the part most people miss: the building itself is often the harder problem to solve, not the borrower.
Most DSCR programs then apply that figure at a discount — commonly 80% of the projected gross — before it ever touches the coverage ratio.
Several Short-term Rentals Sit on One Blanket DSCR Loan — Yes.
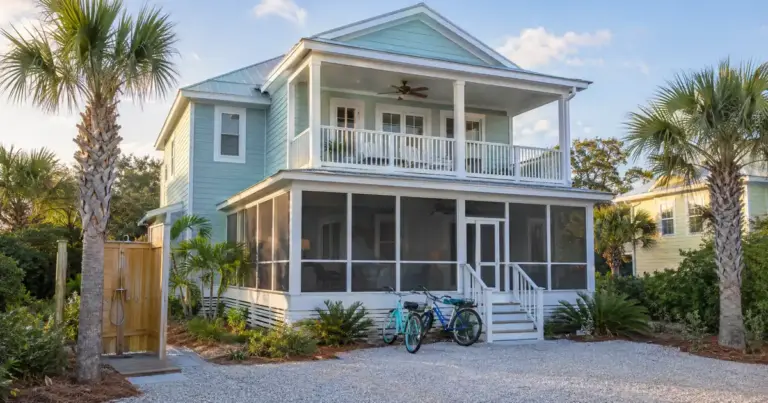
First-Time Rental Owner Get A Short-Term Rental — Mostly yes, but not always through the short-term rental income path itself.
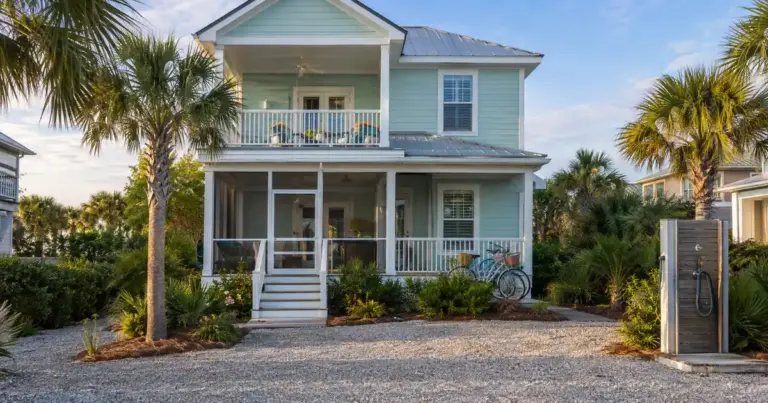
The check happens at closing and again, informally, whenever the loan is serviced, because HOA rules can change during the life of the loan.