DSCR Cash-out Refinance Seasoning: The Six-month Clock From Title Recording
It does not start at the contract date, the rehab finish, or the lease signing.

It does not start at the contract date, the rehab finish, or the lease signing.
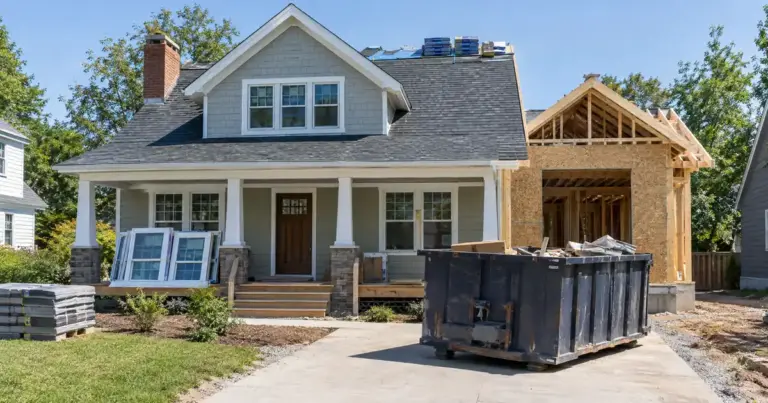
Hard Money Exit Refinance Denied — Usually, the denial is a program mismatch, not a verdict on the deal.
Across the wholesale network, STR cash-out typically tops out around 70% LTV, with a 640+ credit score and about 12 months of hosting history on most files.
DSCR Refinance Loan Amount Limits — The size of a DSCR refinance is capped by two separate tests, and the tighter one wins.
Low Appraisal Rental Refinance Options — It depends on what the refinance was supposed to do.
Refinance Rental After Renovation New Appraised Value — Usually, but only after the lender agrees which value to use.
It removes principal from the monthly obligation, so the same rent divides by a smaller number.
Refinancing A Rental Property With A Second Lien In Place: Subordination Or Payoff: what investors need to know about DSCR financing, from Lendmire.
One path keeps the coverage test and trims the loan size. The other, the no-ratio path, sets the test aside and qualifies you on credit and equity.
It lifts your coverage number during the first decade because the payment is smaller. It does not add a dollar of rent.
On an occupied property, most programs use the lower of the two. If your lease sits below market, the lease sets the rent in the coverage math.
The loan qualifies primarily on property-level rental income covering the payment, subject to lender guidelines.
A refinance doesn’t convert your old mortgage.
Some programs let net proceeds count and some require separately held, seasoned funds.
Before the switch, the file runs on lease rent or market rent.