How To Refinance A Jumbo DSCR Loan After Transferring Title To An LLC
That decision affects seasoning, leverage, and how much documentation lands on your desk before closing.

That decision affects seasoning, leverage, and how much documentation lands on your desk before closing.
Does A Rehabbed Rental Need Seasoning Before A DSCR Refinance — Yes, in almost every case.
The lender looks at rent versus payment instead of your Schedule C.
The loan qualifies on the property’s rent, not your personal tax returns, and jumbo DSCR programs can size well above agency conforming limits.
DSCR refinances are business-purpose loans reviewed differently from a standard owner-occupied mortgage.
Does Higher Rent Raise Leverage On A Jumbo DSCR Refinance — No, not directly.
Expense Factor Change On A Payout Seller’s — No.
The new loan amount matches roughly what you still owe, not what the property is worth today.
The property qualifies on its rent, not your paycheck.
Clearing one does not automatically clear the other.
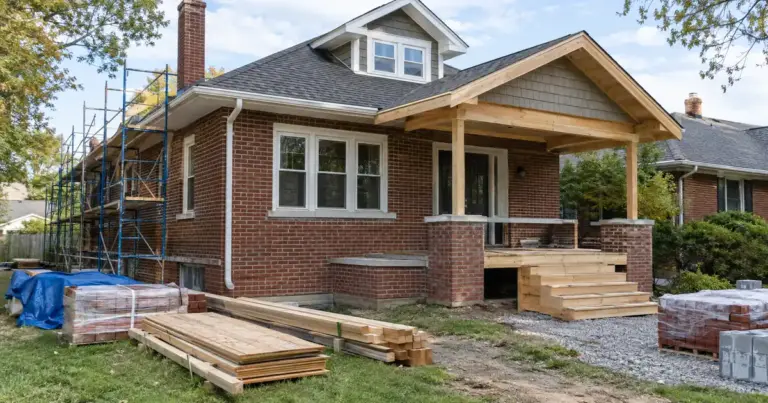
Founder Refinance A Rehab Into A DSCR Loan — Sometimes, but not automatically.
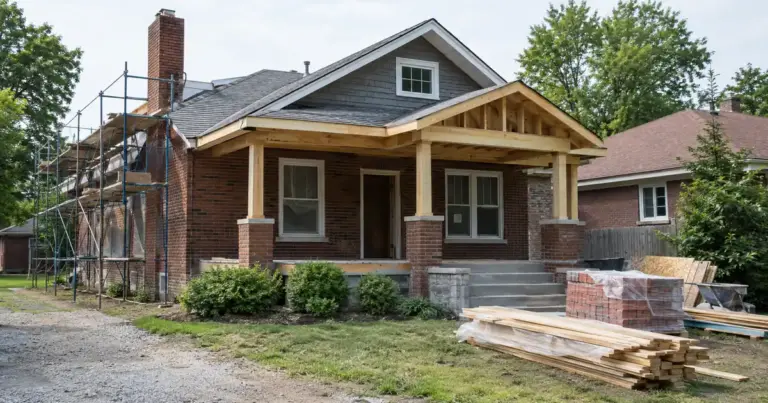
The bridge loan and the DSCR loan are two separate underwriting events, so passing one never guarantees the other.
– Seasoning starts on your original deed-recording date, not the day the rehab finished or the tenant signed.
The rehab dollars don’t automatically convert into loan proceeds; the refinance path chosen determines whether the after-repair value counts at all.
Does A Rehabbed Rental Need Seasoning Before A Jumbo DSCR Refinance — Yes, almost always.