Financing A Luxury Condo With Bank Statements: Complete Guide
A strong deposit history can still get denied if the building is non-warrantable, under-reserved, or a condotel.

A strong deposit history can still get denied if the building is non-warrantable, under-reserved, or a condotel.
The math strips out non-income transfers, applies an expense ratio, and divides by the statement period to find qualifying income.
Loan sizes through select wholesale programs run from $300,000 to $30,000,000, with leverage stepping down as the price climbs.
Getting that classification wrong is the single most common way a lake house deal falls apart late in underwriting.
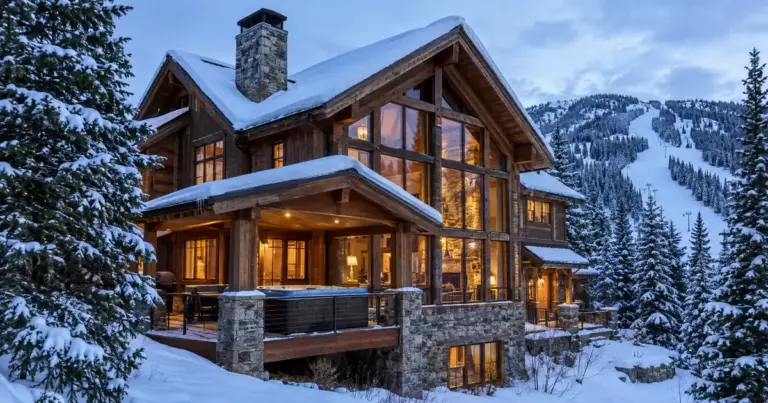
Financing A Ski Chalet With Bank Statements — A ski chalet purchased with bank statement income involves two separate decisions, not one.
Leverage steps down as the loan size climbs, and every file above $4,000,000 goes through case-by-case review before it’s even submitted.
Above roughly $4,000,000, every file gets individual underwriter review before it’s even submitted.
A DSCR loan qualifies the property’s rent, not your personal debts, so a yacht loan payment generally never enters the math.
A W-2 underwriter wants two years of stable, documented income.
Program size runs from $300,000 to $30,000,000 across two wholesale channels, with leverage that steps down as the loan gets larger.
A rental-property loan underwritten on the property’s own income generally never sees the jet at all.
Loans through select programs in Lendmire’s wholesale network run from $300,000 to $30,000,000, structured across two size ladders.
High Net Worth Mortgage Guide For Business Owners — Business owners whose tax returns understate real cash flow can still qualify
– Athlete pay — salary, signing bonus, endorsements, NIL income — rarely fits a conventional two-year tax-return file.
High Net Worth Mortgage Guide For Actors — Qualifying for a large mortgage as a working actor rarely runs through a standard tax-return