
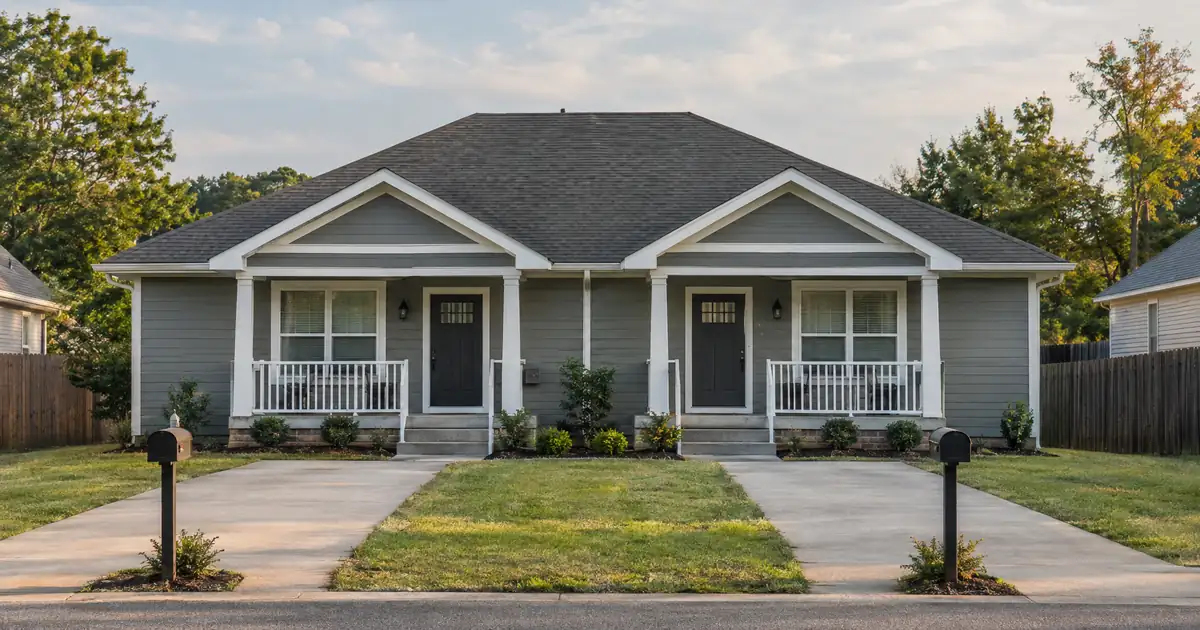
The Quick Read: Yes, when the lender’s program accepts 2-4 unit primary homes and the new loan lands above the conforming limit for your unit count. No federal rule blocks it. Fannie Mae and Freddie Mac can’t buy jumbo loans, so each jumbo lender sets its own leverage, reserve, appraisal and documentation rules. Approval depends on that lender’s program and your full file, and nothing here is a commitment to lend.
Key Takeaways
- A jumbo is any loan above the conforming limit for your unit count. A fourplex has a higher limit than a single-family home in the same county.
- The test uses the total new loan, including the cash you take out and any costs you finance.
- Jumbo programs are not one rulebook. Some lanes accept 2-4 unit primaries. Some don’t.
- Cash-out leverage is lower than purchase leverage. Unit count usually pulls it lower again.
- The unit you live in generally can’t be counted as rent used for lender review.
What Does “Jumbo” Mean on a Duplex, Triplex or Fourplex?
A loan is jumbo when it starts one dollar above the conforming limit for your county and unit count. FHFA sets those limits each year. Limits rise with each added unit, and high-cost counties get higher ceilings than the baseline.
Here’s the catch. The same property can sit on both sides of the line. A cash-out that is jumbo on a one-unit home may be conforming on a fourplex in the same county. And on one fourplex, a smaller cash-out can stay conforming while a larger one tips into jumbo.
The test is the whole new loan balance. Payoff of the old mortgage, the cash you take, and any financed costs all count. Limits change yearly and vary by county, so this article doesn’t quote dollar limits. Check your county’s table on FHFA’s conforming loan limit page before you size anything.
Why Jumbo Rules Differ From Agency Rules
Agency rules are a reference point. They are not the jumbo rulebook. Fannie Mae publishes one set of caps for everyone. A jumbo lender writes its own.
On a 2-4 unit principal residence, Fannie Mae’s Eligibility Matrix allows lower cash-out leverage than on a one-unit home. The same matrix excludes co-op units and attached condo units from its multi-unit eligibility. That tells you how the market treats the property type: it’s seen as heavier risk than a single-family home.
Across the wholesale jumbo programs Lendmire places files with, the shape is similar but the numbers are their own. The headline lane reaches 90% leverage on its best-fit transactions, with a 660 decision score and loans up to $5,000,000 on the largest lanes. Cash-out sits at lower leverage than purchase, and the largest lanes carry a cash cap. Several lanes reach 89.99% combined leverage. The rest stop at 80%. Those are the outer edges. A cash-out on a multi-unit primary will usually sit well inside them, and what a specific file gets depends on the lane, the unit count, the credit profile and the full file review.
Two more points about jumbo that people get wrong:
- Jumbo doesn’t mean non-QM. Loan size and qualified-mortgage status are separate questions. Ability-to-repay rules apply either way.
- Jumbo doesn’t mean no-doc. A consumer mortgage on your home needs verified repayment ability.
Lendmire’s jumbo cash-out refinance program page lays out the lanes. Lendmire is a mortgage broker licensed for consumer lending in 16 states. It arranges these loans through wholesale lenders and does not lend itself.
What Does the Lender Test on a Multi-Unit Cash-Out?
The lender tests leverage, credit, debt-to-income, reserves, seasoning, occupancy and the appraisal. Each one can cap the loan on its own. The lowest cap wins.
| Test | What it checks | What to prepare |
|---|---|---|
| Leverage | New loan against appraised value | Recent mortgage statement, payoff figure |
| Credit | Decision score and payment history | Credit explanations for any late pays |
| Debt-to-income | Total debts against income | Pay stubs or income documents, debt list |
| Reserves | Months of full payment in liquid assets | Two months of asset statements |
| Seasoning | How long you’ve owned and held the loan | Settlement statement, deed |
| Occupancy | That you live in one unit | License, bills, tax records at that address |
| Appraisal | Value and market rents | Access to all units, lease copies |
On the ratio test, the fixed jumbo lanes stop at 50%. The adjustable lanes stop at 45%, and the interest-only lanes at 43%. Those are ceilings, not targets.
Reserves are counted in months of the full payment, and they rise with the loan amount. Cash you pull out of this refinance generally doesn’t count toward them. A borrower who plans to use the proceeds and leave nothing in the bank is the one who gets stuck here.
Seasoning is lender policy, not federal law. Lenders generally want the current first mortgage in place for a set period and want time on title. Exceptions for inheritance, legal awards or delayed financing vary by program. If you bought recently, ask about this first.
How Is Rent From the Other Units Treated?
Rent from the unit you live in generally can’t be used to qualify. Under Fannie Mae’s rental income policy, a 2-4 unit principal residence means you occupy one of the units, and the occupied unit doesn’t produce rent used for lender review. Narrow exceptions exist, like boarder income.
Rent from the other units is a different story, but jumbo lenders vary. Some count a portion of it with documentation. Some count less. Some count none and review the loan against the borrower’s own income alone. Ask before you assume.
Whatever the lender counts, it will want a clean paper trail. A typical per-unit checklist:
| Item | Why it matters |
|---|---|
| Signed, current leases | Shows who pays what |
| Bank statements with rent deposits | Confirms rent is actually collected |
| Tax return with rental schedule (if history exists) | Shows reported rental income |
| Appraisal rent schedule | Gives market rents for each unit |
| Proof you occupy one unit | Supports primary-residence status |
Gaps here cause most of the preventable delays on multi-unit files. A lease that expired, a deposit that goes to a different account, or a missing unit’s rent history each force a follow-up request.
How Big Is the Cash-Out? A Sizing Walk-Through
Cash-out is a subtraction problem with a lender-set cap on the front end. No dollar figures are needed to see how it works.
1. Start with the appraised value of the whole property.
2. Apply the lane’s maximum cash-out leverage for your unit count. This gives the largest allowable new loan.
3. Subtract the payoff of your current first mortgage.
4. Subtract any costs you finance into the loan.
5. What’s left is the most cash you could take. Some lanes also cap the cash itself. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
The lower number binds. Say your leverage cap leaves a lot of room, but the lane has a cash cap. The cash cap sets your proceeds. Or say the cash cap is generous, but your appraisal comes in low. Then the value sets the limit.
Picture a homeowner who lives in a fourplex and has owned it for years. They’re at a modest share of value on the current mortgage. Run the steps above, and a good deal of equity may be usable. Now picture a duplex owner who bought recently. The seasoning and a lower appraised value both squeeze the number. Same product, very different results.
Appraisal matters more on 2-4 units than on a single-family home. These properties are appraised on a small residential income property form that includes market rents. Agency appraisal waivers generally aren’t available on 2-4 unit properties, and jumbo lanes require a full appraisal. Above a lane’s threshold amount, they may require two. If value comes in low, an appraisal reconsideration request with recent comparable sales is the standard next step.
Can You Carry the New Payment If a Unit Sits Empty?
A cash-out replaces your whole first mortgage with a larger balance. Before you apply, stress-test it. Remove one unit’s rent entirely and see whether your household budget still carries the full payment, taxes and insurance.
Lenders include the full payment on your primary residence as an obligation. They won’t give you a pass because the building has tenants. If your plan depends on the rent from other units to make the payment work, the plan is more fragile than the file looks. Jumbo lenders see that, and so should you.
Also expect the loan to cost more than a conforming loan. The CFPB notes that a jumbo may cost more than a conforming loan. Pricing is set by the lender and shown on your Loan Estimate.
Jumbo Cash-Out vs. Other Ways to Pull Equity
| Option | Fits when | Watch for |
|---|---|---|
| Jumbo cash-out | New balance exceeds the limit | Lender-specific overlays |
| Conforming cash-out | New balance fits under the limit | Lower leverage on 2-4 units |
| Second lien or HELOC | Current first mortgage is worth keeping | A second payment, separate approval |
| Keep current loan | Equity isn’t needed right now | Nothing to fund |
On a multi-unit, the conforming route can win when the numbers fit. Higher limits for 2-4 units mean more owners land under the line than they expect. The tradeoff is a lower leverage cap for the unit count.
Honestly, this is a toss-up for many owners. A second lien keeps a first mortgage you may like. A full cash-out resets everything. The right answer depends on the balance, the cash you need and what each lender will allow. Lendmire can help you compare the programs and the equity each one reaches.
Where the General Rule Breaks
- You move out. Once you don’t occupy a unit, the property isn’t a primary home. Different occupancy carries different, lane-specific leverage.
- The lender excludes 2-4 units. Some jumbo lanes don’t take them at all. A different lane may.
- The appraisal comes in low. Value sets the ceiling no matter what your equity looked like.
- You bought or inherited recently. Seasoning and title rules apply, with exceptions that vary.
- The property is a condo. Non-warrantable condominiums are accepted on two lanes, not all of them.
- A first-lien jumbo is priced high. Under CFPB’s higher-priced mortgage test, a first-lien jumbo can be classed as higher-priced when its APR runs 2.5 percentage points or more above the benchmark, which triggers added consumer protections.
Tax treatment can depend on your situation; borrowers should speak with a qualified tax professional before relying on any deduction or credit.
Key Terms Defined
Conforming loan limit: The maximum loan size Fannie Mae and Freddie Mac can buy, set each year by FHFA by unit count and county. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Jumbo loan: A mortgage above the conforming limit for that property and county.
Cash-out refinance: A new, larger mortgage that pays off the old one and gives you the difference as cash.
Seasoning: The length of time you’ve owned the property or held the current loan.
Reserves: Liquid savings, counted in months of the full payment, kept after closing.
Combined loan-to-value (CLTV): All loans on the property combined, divided by its appraised value.
Step-by-Step: Preparing a Multi-Unit Jumbo Cash-Out
1. Look up your county’s conforming limit for your unit count.
2. Estimate your property’s value and your current payoff.
3. Gather leases, rent deposit records and proof of occupancy for all units.
4. Pull two months of asset statements to show reserves.
5. Ask your broker which lanes accept 2-4 unit primaries and what each one’s cash cap and leverage are.
6. Ask how each lender counts rent from the other units.
7. Review the Loan Estimate line by line against any alternative.
Every parameter above is subject to lender guidelines and a full file review.
Frequently Asked Questions
Can I use rent from my other units to qualify?
It depends on the lender. Rent from the unit you live in generally can’t be used. Rent from the others may count in part, in full or not at all. Current leases and deposit records make any rent easier to document.
Do I need two appraisals?
Possibly. A full appraisal on the income property form is standard. Above a lane’s threshold amount, a second appraisal may be required. Expect the appraiser to need access to every unit.
Can the cash I take out count toward my reserves?
Generally no. Reserves are measured in months of the full payment and rise with the loan amount. Plan to keep liquid savings outside the proceeds.
What if I recently bought the home?
Seasoning and time-on-title rules may apply. They are lender policy rather than federal law, and exceptions for inheritance or delayed financing vary by program. Ask before you order an appraisal.
Is a jumbo cash-out the same as a non-QM loan?
No. Size and QM status are separate. Ability-to-repay rules apply to jumbo and non-QM loans alike, so you’ll still document income, assets and credit.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
Lendmire, NMLS# 2371349, is a mortgage brokerage with consumer lending licenses in 16 states. FHA, VA, conventional and jumbo purchase and refinance loans are arranged through wholesale lending partners, and each application is reviewed individually by the lender. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
For the program’s current guidelines, see jumbo loan programs.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. FHFA – 2026 conforming loan limit announcement
2. FHFA – Conforming Loan Limits
3. Fannie Mae Eligibility Matrix
4. Fannie Mae Selling Guide – Rental income
5. CFPB – What is a jumbo loan?
6. CFPB’s higher-priced mortgage test
This article is part of Lendmire’s Jumbo Loans series — every loan program’s qualification details, guidelines, and scenarios live on the loan options page.
Related reading: Can Jumbo Cash-Out Funds Be the Down Payment on a Second Home? · How Much a Jumbo Second-Home Cash-Out Releases Next to a Primary Home · Does a Second Home Need Two Appraisals on a Jumbo Cash-Out?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.