
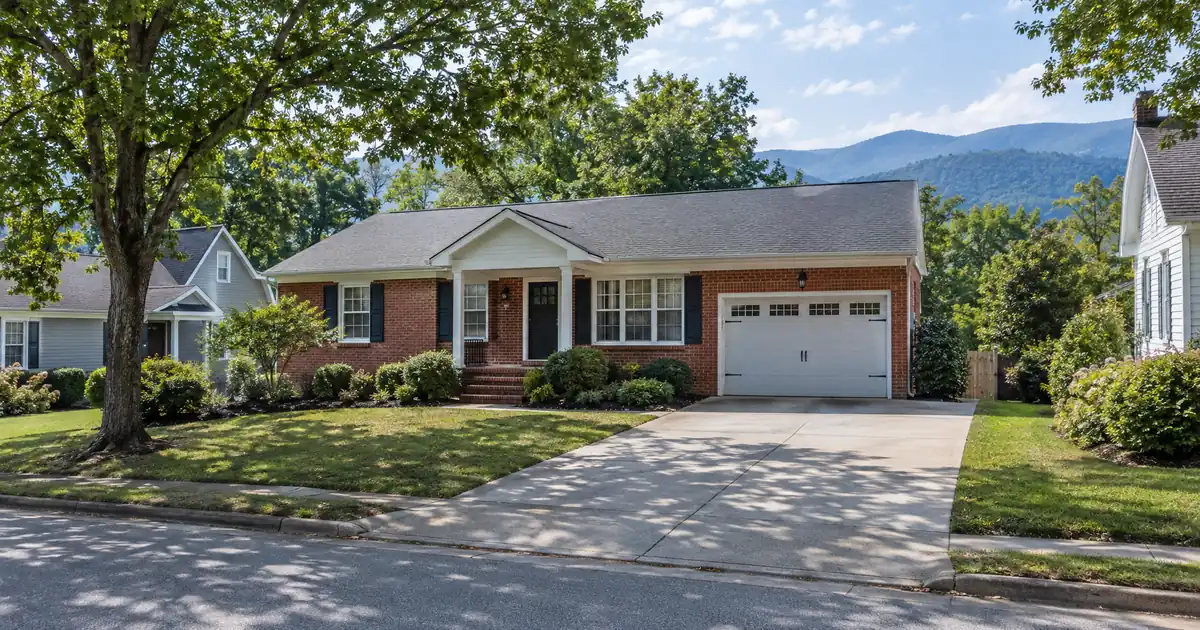
Most Brevard investors assume rent is the constraint on a cash-out refinance. Rent is only half of it. The bigger question is what an appraiser will say the building is worth after a run-up that has stopped running, and the 75% ceiling applies to that number, not to what you paid or what the building was worth at the peak.
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker. Through Lendmire’s DSCR program footprint — 41 markets, including Washington, D.C. — lenders may review qualifying rental income subject to program guidelines for Brevard, North Carolina investors. Most of what follows is about how that review plays out in a town of under 8,000 people where sale prices are high, rents are workforce-level, and inventory is thin.
DSCR Cash-Out Calculator
Run the cash-out numbers in Brevard, NC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
A DSCR cash-out refinance on a Brevard, North Carolina investment property is underwritten primarily on the rental income the building produces measured against its full monthly obligation, with proceeds capped by a 75% loan-to-value ceiling on the appraised value, subject to lender guidelines, seasoning, and reserves.
- Redfin puts the median sale price near $474K, down 7.9% year over year.
- Duplex-to-fourplex buildings carry the coverage; typical single-family sits below 1.00x.
- Seasoning runs about 6 months from title recording.
- Proceeds depend on the appraisal, not the purchase price.
- Ecusta Trail progress is the local catalyst to track.
Brevard Market Snapshot
A quick read on the Brevard investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $472,004 median value (NeighborhoodScout, Brevard) |
| Typical rents | $1,500 rents (Brevard NewsBeat, dire housing) |
| Employment | 3,000+ mill jobs (Wikipedia, Transylvania County) |
| Vacancy | 0.1% (Brevard NewsBeat, dire housing) |
The Appraisal Is the Bottleneck
Cash-out proceeds in Brevard are limited by appraised value first and rent second. Redfin’s August median sale price was $474K, down 7.9% year over year, with 49 days on market. Zillow uses a different method and shows an average home value of $464,538, down 2.0%. Both point the same way: flat to soft.
Softness in the for-sale market changes how the appraisal comes back. County inventory sits at 7.6 months, and Movoto reports Brevard homes averaging 103 days on market versus 91 a year earlier. Appraisers in that kind of market lean on closed comps and skip the hopeful ones. Picture an investor who bought at the peak and refinances into a market where the best recent sales sit lower. The 75% cap applies to the lower number. Proceeds shrink even though the rent never moved.
Plan on the current appraised value, not the peak. That is the only underwriting assumption that survives contact with the appraisal.
Sources conflict here, which is normal for a market with thin monthly volume. Movoto’s listing-based median runs well above the other two, likely because it covers a broader geography. Treat any single median as noisy and expect the appraiser to work from comps in the subject’s own submarket.
Why Coverage Falls Apart on Single-Family
Single-family at typical Brevard prices does not clear 1.00x on rent alone. The modeled math shows why. DSCR is monthly rent divided by the full monthly obligation: principal, interest, taxes, insurance, and any HOA dues.
Run the numbers on a house valued near the $474K median at 75% LTV. Assume a $2,300 rent, which is a modeled input, because the last posted Zillow house-rent median is dated and rests on only 11 listings. Coverage including taxes and insurance lands around 0.8x. That is sub-1.00 territory. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Most standard programs are built around a 1.00x benchmark. Some lenders will look below it, but usually with lower leverage, different pricing, larger reserves, or a stronger credit profile. The paths a lender may review on a file like this include a sub-1.00 program, an interest-only structure, or a smaller cash-out request. Any of those is subject to lender guidelines, credit approval, and property review. None is a given.
The workforce ceiling makes the ceiling on rent visible. The city’s workforce-housing analysis, reported by Brevard NewsBeat, puts workforce-level rent or home payments at a maximum of $1,669 a month, and half of Transylvania’s workers are in industries averaging under $40,000 a year. The HUD fair market rent for a two-bedroom in Transylvania County is $1,128, and that is a floor, not market rent. A $474K house does not rent into that band.
Where the Number Works: Small Multifamily
Two-to-four-unit buildings are the best fit for a DSCR cash-out in Brevard. Stacked rents cover one mortgage, and the price per door is far below the single-family median. NeighborhoodScout shows single-family detached homes at 63.20% of Brevard’s housing units, duplexes and small converted buildings at 16.61%, and large complexes at 15.85%. Small multi-unit is roughly one unit in six. Real, but a minority slice.
The pricing gap is what stands out. Redfin’s multifamily feed showed one multi-family listing in Brevard, a Rosman duplex, at a median list price near $302K. Two units at the HUD $1,128 floor gross $2,256 a month. Modeled at 75% LTV against that value, coverage including taxes and insurance comes out around 1.2x. Bump each unit to the $1,500 market-rate two-bedroom median from an older Bowen study and it clears 1.5x. That study likely dates to a few years back and counted subsidized units in a 0.1% county vacancy figure. Take it as directional. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
The listing is in Rosman, not the city core, and one listing is a snapshot, not a trend. Comps for these buildings are thin, and thin comps mean the appraiser has fewer sales to work with. Good multi-unit files in a market like this carry a short comp packet: recent nearby sales, unit mix, and lease evidence for every door.
The demand side supports it. Buildable lots are scarce because of floodplains, steep slopes, limited utilities, and public land. That favors existing small buildings. A local builder is developing 18 apartments off Caldwell Street, so small-scale rental product is feasible here. It is also new supply to watch.
Working DSCR brokers see a recurring pattern in second-home-driven mountain markets: the rent-to-value gap looks worst on paper at the median and disappears at the small-building level. The files that struggle carry a peak-era basis and a single-family rent. The files that clear tend to be older duplexes or fourplexes with lease evidence on every unit and a comp set from the same immediate area.
Submarkets That Pencil
The strongest submarkets are the ones where tenants already live and work. No neighborhood-level price or rent series exists for Brevard, so the descriptions below are qualitative.
Downtown and the historic core. Demand comes from hospitality, arts, and festival workers. The area is a National Register Historic District with galleries, restaurants, and retail, per a PracticeLink facility profile. Small buildings here are scarce, and scarcity supports the appraisal.
The hospital corridor. Transylvania Regional Hospital is a 25-bed, full-service facility and the county’s largest employer, and it sits between downtown and the Pisgah National Forest entrance. Data USA lists health care as the top resident employment sector at 1,907 workers, with retail close behind at 1,905 and construction at 1,490. Healthcare workers, including travelers, keep 1-to-2-bedroom units occupied.
Caldwell Street and the near-town corridor. Workforce renters, and the site of the 18-unit project. Rent ceilings are the workforce numbers above, so underwrite conservatively.
Brevard College area. The campus sits at the northern edge of downtown and enrolls about 900 students, including 60+ graduate students. Not a student-housing play. Faculty and staff demand is a modest support.
Rosman Highway and the Ecusta Trail corridor. Rosman is a separate town, and Penrose, Pisgah Forest, Etowah, and Horse Shoe run along the trail. These areas may pick up outdoor-recreation tenants. That is inference, not a measured rent effect.
Not a reason to pay up. Just a reason to keep these submarkets on the list.
Seasoning, Leverage, and What the Proceeds Do
The mechanics on a cash-out refinance are straightforward. The friction is the seasoning requirement and the documentation behind it. Programs in the network typically look for about 6 months of ownership, measured from title recording, and the settlement statement is the document that proves it. Files that assume the requirement away get kicked back. Leverage on a cash-out tops out at 75% LTV. Most files also carry about 6 months of PITIA in reserves (higher on larger balances), and credit tiers start at a 620 floor. Reserves documentation is the second place files stall, so bank and account statements should be organized before submission. All of this is subject to lender guidelines. The cash-out qualification details cover the full requirements, and the DSCR fundamentals explain how coverage is calculated.
Proceeds are not a guaranteed figure. They depend on rent used for lender review, PITIA, reserves, and the 75% ceiling applied to the appraisal. LLC-titled properties can be eligible, subject to lender program eligibility, so entity documents, operating agreements, and any lease evidence should be assembled in advance.
Where do the proceeds go? Two directions make sense. The first is a down payment on a second small building, which improves the portfolio’s overall coverage. The second is paying down a higher-cost balance on an existing property. Both are business decisions the borrower makes. Lendmire’s guides to the tradeoffs between conventional and DSCR loans on investor properties and to the refi programs cover this in more depth. Lendmire’s North Carolina DSCR platform carries the state-level detail.
Which Price Band Is Easiest to Refinance?
Buyer activity concentrates in a specific band, which tells you where valuations are easiest to defend. County showings in the $319,000 to $463,000 range rose 50.4% year over year in one monthly report, the fastest-growing segment, while showings under $219,000 fell 28.3%. Those are showing counts, not sales, so read them as directional. Still, properties in the middle band should be easiest to appraise and to sell if the borrower changes plans. Sub-$219K properties may face thinner demand, which is a comps problem for the appraiser too.
Forty percent of homes sold since 2020 went to buyers with mailing addresses outside Transylvania County. That demand is what pushed the basis up. It also means equity here has been appreciation-led, not cash-flow-led. Appreciation has stalled. Investors leaning on more of it should size the cash-out with that in mind.
The Next 24 Months: What to Watch
Three indicators will show whether Brevard’s appraisals firm up or slip further.
1. Days on market and months of inventory. The county’s 7.6 months and the city’s 103 days are buyer’s-market readings. If they tighten, appraisals get easier. If they keep lengthening, expect more reconsideration requests.
2. Ecusta Trail progress. The 19.4-mile rail-trail will connect Hendersonville to Brevard, and the first 6 miles are open from Hendersonville to Horse Shoe. Hurricane Helene delayed the opening by six months. Rails to Trails Conservancy says phase two finishes in a few years. Each completed segment is a potential catalyst for trail-adjacent buildings.
3. New rental supply. The 18-unit project and the 80-unit subsidized complex, the first of its kind built in the city in over a decade, show how little stock is being added. Any change in that pace shifts rent comps.
The stronger play here might be an older duplex close to the core, though an investor betting on trail-driven appreciation could argue for the corridor instead. Honestly, it is a toss-up until the appraisal data firms up. Verify current local rental rules, taxes, and insurance with qualified local professionals before underwriting anything.
DSCR vs. conventional financing
Two common ways to finance an investment property in Brevard, NC. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
What property types work best for DSCR cash-out in Brevard?
Duplexes, triplexes, and fourplexes near downtown and the hospital corridor carry the strongest coverage, with workforce single-family bought at a low basis a distant second. Lendmire arranges DSCR investor loans and a key program feature for this file type is the 75% LTV ceiling on cash-out, subject to lender guidelines.
How do you qualify for a DSCR cash-out refinance in Brevard, North Carolina?
The property’s rent has to cover its full monthly obligation, with 1.00x as the common benchmark, and the loan has to fit within 75% of appraised value. Lenders also look at credit (a 620 floor, with better tiers at 660, 680, and 700), reserves of about 6 months PITIA, and roughly 6 months of ownership. Qualification is subject to lender guidelines and property review.
What are the requirements for an investment property loan in Brevard, NC?
Expect a signed lease or rent schedule, entity documents if the property is held in an LLC, an appraisal, insurance evidence, and reserves documentation. Manufactured homes, log homes, and barndominiums fall outside the network’s DSCR programs, which matters in mountain markets. Loan sizes run up to $3,000,000 on standard programs. You can request a quote to see how a specific property fits.
Can a Brevard single-family rental still support a cash-out?
Sometimes, but not on rent alone at the median price. Coverage often lands below 1.00x including taxes and insurance, so the file usually needs a lower basis, a smaller cash-out, or a structure a lender reviews for sub-1.00 coverage. Eligibility depends on credit, reserves, and the appraisal.
Does the 40% out-of-county buyer share help or hurt a refinance?
It helped build equity, but it does not guarantee future appraisals. The demand supported prices through a big run-up, and prices have since softened. Appraisers will work from recent closed sales, so the current comp set matters more than the earlier trend.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C., through wholesale and investor-lending channels. DSCR loans are evaluated by the lender on rental income rather than personal income, subject to lender guidelines, which suits LLC-owned portfolios, self-employed investors, and operators scaling beyond conventional loan caps. Recognized as a 2025 Scotsman Guide Top Mortgage Workplace and a 2026 Scotsman Guide Top Mortgage Workplace. Reach the team at 828-256-2183.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin, Brevard housing market
3. Bowen study
4. Wikipedia, Transylvania County
5. Zillow, Brevard home values
6. ruizreport.com — @zac Transylvania NC
7. Movoto, Brevard market trends
10. City of Brevard, Affordable Housing
11. one multi-family listing in Brevard, a Rosman duplex, at a median list price near $302K
12. 18 apartments off Caldwell Street
13. PracticeLink facility profile
14. Mission Health, Transylvania Regional Hospital
16. Brevard College Student Profile
17. billyharrisnc.com — April Market Report Transylvania County
18. buyers with mailing addresses outside Transylvania County
19. Ecusta Trail
20. Wlos.com — Local Ecusta Trail Greenway Officially Opens After
21. Rails to Trails Conservancy
22. Brevardnewsbeat.com — Brevard Pledges As Much As
23. a 2025 Scotsman Guide Top Mortgage Workplace
24. a 2026 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Brevard, North Carolina · DSCR Loans In Brevard / Hendersonville, NC · DSCR Cash Out Refinance in Harrisburg, North Carolina: Pulling Equity From a Thin-Rental Suburb
Guides: Investment Property Cash-Out Refinance in North Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.