
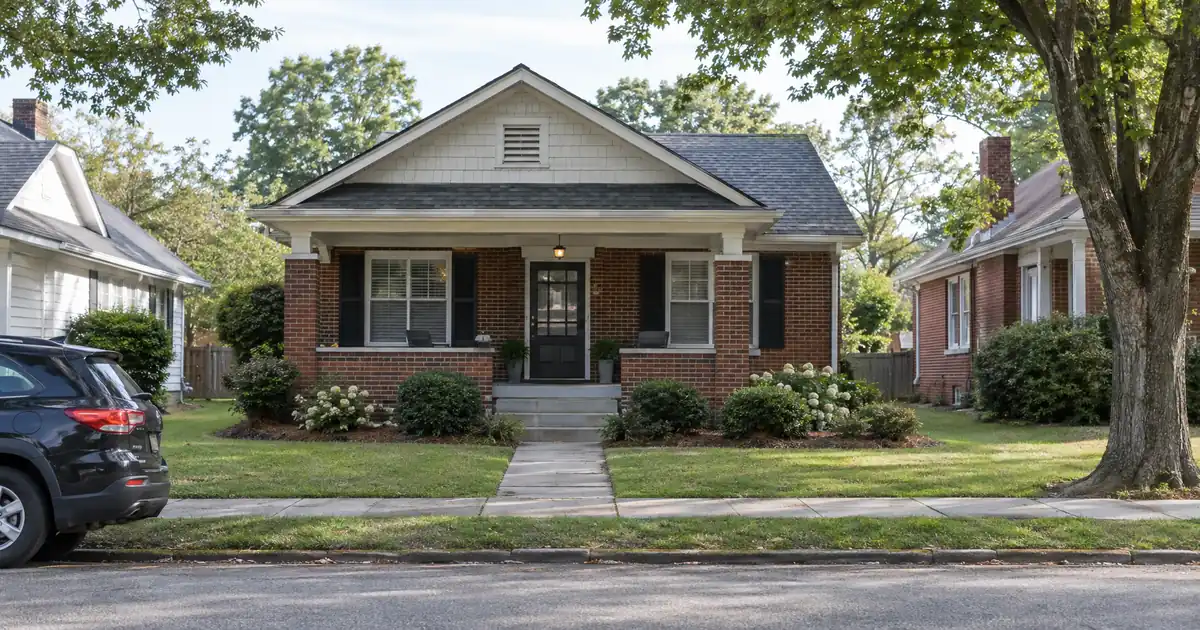
An out-of-state investor scrolling Goldsboro listings sees a typical home value of $178,983, up 7.3 percent over the past year, per Zillow. The next thing they notice is a rent-to-price ratio most coastal markets can’t match. What they miss is that the equity is only worth what the appraisal says it is. This article covers the back end of the deal: pulling equity out of a Goldsboro rental you already own with a DSCR cash out refinance, and how that file holds together at 75 percent LTV. Lendmire, a DSCR-focused mortgage broker, arranges these loans through wholesale lending channels, and lenders review and approve them.
At a Glance: A DSCR cash out refinance in Goldsboro, North Carolina is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the file turns on seasoning, appraisal comps, and lease evidence rather than personal income documents.
DSCR Cash-Out Calculator
Run the cash-out numbers in Goldsboro, NC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out LTV caps at 75 percent, with about 6 months of ownership measured from title recording.
- Goldsboro’s 34,383 residents skew renter-heavy, and an Air Force base anchors demand.
- Older workforce three-bedroom homes carry the cleanest coverage math in the market.
- Small multifamily is thin and priced well above single-family values.
- Appraisal comp selection is the main failure point on Goldsboro files.
Goldsboro Market Snapshot
A quick read on the Goldsboro investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $276,290 median (Homes.com) |
| Typical rents | $1,093 median gross (city-data.com) |
| University enrollment | ~19,000 students (NC State CED) |
| Employment | 9,000+ jobs (Wayne County ACFR (NC Treasurer)) |
Why Goldsboro Equity Is Worth Pulling
Goldsboro is a low-basis market with a durable tenant base, which is what makes the equity-extraction math work. The Zillow figure above puts the typical home near $179,000. Zillow’s rental data shows houses renting from $800 to $2,750, with a median of $1,350. That page cites March for the median, so treat it as directional. Against the typical value, that works out to roughly 0.75 percent rent-to-price, or about a 9 percent gross yield. That is illustrative arithmetic, not a published market statistic.
Pricing sources disagree, and the gap matters at appraisal. Homes.com cites a median of $276,290, but listing medians skew toward newer, larger homes, so that is not the number for an older rental. Use roughly $175,000 to $230,000 as the working band, depending on method, and underwrite on same-vintage comps.
Demand has a hard anchor. Seymour Johnson Air Force Base hosts the 4th Fighter Wing and the 916th Air Refueling Wing. UNC Health Wayne’s community page says more than 4,600 airmen and 6,000 family members live in the community. The 4th Fighter Wing also trains F-15E aircrews, so orders keep rotating through. That gives long-term rentals a renewable tenant pool tied to the base rather than to the local job market. Wayne County’s audit report adds that farming and agribusiness make up 20 percent of county employment. The workforce here is not one-industry.
Owner-occupancy runs around 39 percent per a secondary aggregator, so the renter pool is deep. Median household income in the city is $48,540. Rents sit low in absolute terms, which is why coverage depends on buying and holding at a low basis.
The Equity Math, Step by Step
The cash-out ceiling is 75 percent of appraised value, not the 80 percent used on purchases. Proceeds are what’s left after the existing payoff, reserves, and closing costs. Equity available depends on rent used for lender review, the full monthly obligation, reserves, and that ceiling. It is not a guaranteed cash figure, and the calculator converts the percentages to dollars.
Run the numbers on a modeled case. Say an investor owns an older three-bedroom bought below $179,000, appraising near the typical value. Assume $1,350 in rent used for lender review. At 75 percent LTV, coverage including taxes and insurance lands around 1.2x. That is above the 1.00 benchmark most standard DSCR programs are built around, because the rent covers the obligation at that level. Some lenders review lower ratios, but those files usually need lower leverage, stronger compensating factors, or different pricing. Eligibility depends on lender guidelines, credit profile, reserves, and property review. The inputs are modeled assumptions, not market data.
Rent evidence supports the assumption. Live Zillow house listings show three-bedroom asking rents from roughly $950 to $1,800, though asking rents are not achieved rents. A military-housing guide lists E-5 with dependents BAH at $1,521 per month, described as enough for a solid three-bedroom. That figure was last verified in March, so check it against the DoD lookup before relying on it. Treat it as a rent-level reference point, not a tenant-screening shortcut.
DSCR files in markets like this one typically look like a clean-coverage, thin-balance file. Rent clears 1.00 with room, but the file gets slowed by small-balance routing, comp disputes, and thin documentation, not by the ratio. Lease copies, entity documents, and reserves statements sit in the file before submission. The files that stall are the ones assembling those items after the lender asks.
Where the Coverage Holds (and Where It Doesn’t)
Berkeley Boulevard and Spence Avenue
This is the east-side corridor closest to the base. MyBaseGuide describes the Berkeley Boulevard corridor as apartments and rentals. It lists Princeton Road and US-70 areas as older single-family homes at very low price points. Those older homes are the likeliest place for a high rent-to-price ratio. They are also the likeliest to carry condition problems that pull an appraisal below the value the investor needs. No sourced price or rent bands exist for these pockets, so local comps decide.
US-70 East and the Western ZIP
Along US-70 East, the demand story is the same, but I found no price data. In ZIP 27534, covering the western and southern side near the hospital and college, Zillow listings show three-bedroom asking rents of $1,650 and $1,800. That is higher than comparable bedroom counts in ZIP 27530. UNC Health Wayne is a major employer. The 2010 Wayne County employer list ranks the base first, then the school system, then the hospital. Those counts are stale, so use them for rank order only. Wayne Community College adds a smaller layer of demand, not a university-town student market.
Downtown and Near-Downtown
Downtown carries the lowest price points and the widest condition variance. A small older two-bedroom in ZIP 27530 lists near $1,000 per month. The cash-flow math looks good on paper, but the appraisal and the lender’s property review are where these files get tested. Skip any file where condition is unknown.
Duplexes: The Math Doesn’t Reward Them Yet
Small multifamily is thin. Homes.com showed three multifamily listings priced from $410,000 to $989,000, and some looked like multi-house or acreage parcels rather than classic duplexes. Apartments.com puts the Goldsboro two-bedroom average near $1,102.
Model it: two-bedroom units at about $1,100 each against a $410,000 entry gives roughly 0.54 percent rent-to-price. That is weaker than the single-family ratio. At 75 percent LTV with taxes and insurance, coverage lands below 1.00. That is a modeled result, not a sourced statistic.
A sub-1.00 file still has paths a lender may review. These include a sub-1.00 program, an interest-only structure, or a lower-leverage refinance. All of them are subject to lender guidelines, credit approval, and property review. Honestly, workforce single-family is the better DSCR fit unless the duplex is bought well below the current asking range.
Seasoning, Comps, and the Small-Balance Problem
Three mechanical issues decide most Goldsboro cash-out files.
Seasoning. Cash-out typically requires about 6 months of ownership, measured from title recording and documented by the settlement statement. Files that assume it away get kicked back. Clearing title cleanly on the original purchase matters here.
Appraisal comps. New construction in the area starts around $264,900, and builders have offered incentives of $8,000 to $10,000 on some projects per Homes.com. An appraiser who pulls new-build comps for a 1970s rental overstates value. One who pulls only distressed sales understates it. An appraisal reconsideration request is a routine step, not an emergency. Package same-vintage, same-area sales and condition adjustments. That recovers most of the value when the first pass comes in light.
Balance size. Standard programs run up to $3,000,000, but Goldsboro balances are small. Smaller loans route through select lenders in the network, which affects who reviews the file and what the file needs. Reserves of about 6 months of the full monthly obligation are typical, and credit tiers start at a 620 floor. Eligibility varies by borrower, property, and loan scenario. Manufactured homes, log homes, and barndominiums fall outside these programs.
Supply and Appreciation: The Honest Read
Zillow’s 7.3 percent one-year gain is the only appreciation figure I could source. There is no reliable vacancy or cap-rate source for Goldsboro, and that is worth knowing before underwriting.
On supply, the most recent annual permit count was 118 housing units, down 22.4 percent from the prior year, and all were single-family. There is no sign of a multifamily oversupply wave. A projection cited by Habitat for Humanity says Wayne and Lenoir counties could face a shortage of nearly 9,000 housing units. That is an advocacy-sourced projection, not a fact. Two proposed 84-unit subsidized projects sit on the state housing agency’s application list, unreviewed. They are a watch item for lower-tier rents, nothing more.
The newer apartment communities cap rents on the single-family side. Zillow’s page lists one-bedrooms from $1,350 at new communities. The same page says amenity-rich units are rare in Goldsboro, which hints at a gap for renovated product. Renovation before the refinance can lift both rent and appraisal. Verify current local rental rules, property taxes, and insurance with qualified local professionals before you commit.
How the Proceeds Get Used
The cash out is capital for the next acquisition or a renovation. Equity pulled from a low-basis Goldsboro rental can fund the next purchase, in Wayne County or elsewhere. The guide “The Refi Options” covers the mechanics, and the investment property refinance options lay out the alternatives. For the program basics, start with an overview of how DSCR loans work. To see where this diverges from bank underwriting, read the guide “Where DSCR and Conventional Diverge”.
If the title holds the property in an LLC, that works subject to lender program eligibility. Have the operating agreement and entity documents current before submission.
To put a Goldsboro file in front of the network, review my scenario or call 828-256-2183. Details on Lendmire’s North Carolina DSCR loan programs are on the state page. Program details change and are subject to lender overlays, so confirm current terms before you plan around them.
Frequently Asked Questions
How do you qualify for a DSCR cash out refinance in Goldsboro?
Qualification centers on the property’s rent used for lender review against its full monthly obligation, with a 1.00 baseline common on standard programs. Typical guidance includes about 6 months of ownership from title recording, a credit floor of 620, and about 6 months of reserves. Everything remains subject to lender guidelines, credit approval, and property review.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Goldsboro, NC, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Goldsboro, North Carolina?
Expect a lease or rent-comp evidence, entity documents if the property sits in an LLC, a reserves statement, and an appraisal. On a cash-out, LTV caps at 75 percent. Smaller Goldsboro balances route through select lenders in the network, so confirm program fit early.
Can new-construction sales hurt an older Goldsboro rental’s cash-out appraisal?
Yes. New builds start around $264,900, well above the older rental tier. An appraiser who mixes those comps with older stock can inflate or distort the value. Same-vintage, same-area comps keep the appraisal defensible, and a documented reconsideration packet can correct a light result.
Does Seymour Johnson Air Force Base make Goldsboro rents more stable?
The base supplies a renewable tenant pool, since PCS orders replace departing households with arriving ones. UNC Health Wayne’s page puts more than 4,600 airmen and 6,000 family members in the community. That supports occupancy, but it does not guarantee any single property’s rent or coverage.
If you only take one thing from this piece, it’s this: in Goldsboro, the base supplies the tenants and the appraiser’s comp selection decides how much equity you can actually pull.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a DSCR-focused mortgage brokerage, NMLS# 2371349, placing investor loans across 41 markets, including Washington, D.C. Lenders generally review DSCR eligibility around a property’s rental income rather than personal income documentation. That fits LLC-held rentals, self-employed investors, and portfolios scaling past conventional financed-property limits. Lendmire has been recognized by Scotsman Guide as a 2026 Top Workplace and named a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Home Values, Goldsboro
2. Census Reporter — Goldsboro NC
3. Homes.com, Goldsboro multifamily
5. NC State CED
6. Wayne County Annual Financial Report
7. Zillow Rental Manager, Goldsboro
8. UNC Health Wayne, About Goldsboro and Wayne County
10. E-5 with dependents BAH at $1,521 per month
11. MyBaseGuide, Seymour Johnson AFB
12. UNC Health Wayne
14. Goldsboro two-bedroom average near $1,102
15. Homes.com
16. Wayne and Lenoir counties could face a shortage of nearly 9,000 housing units
17. nchfa.com — Forms Resources
18. recognized by Scotsman Guide as a 2026 Top Workplace
19. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Goldsboro North Carolina · Cash Out Refinance Investment Property in Nags Head, North Carolina: Thin Comps and Tourism Equity · DSCR Cash Out Refinance in Wake Forest, North Carolina: A 2026 Guide to Capital Blvd Rentals
Guides: Investment Property Cash-Out Refinance in Goldsboro, NC · Investment Property Cash-Out Refinance in North Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.