
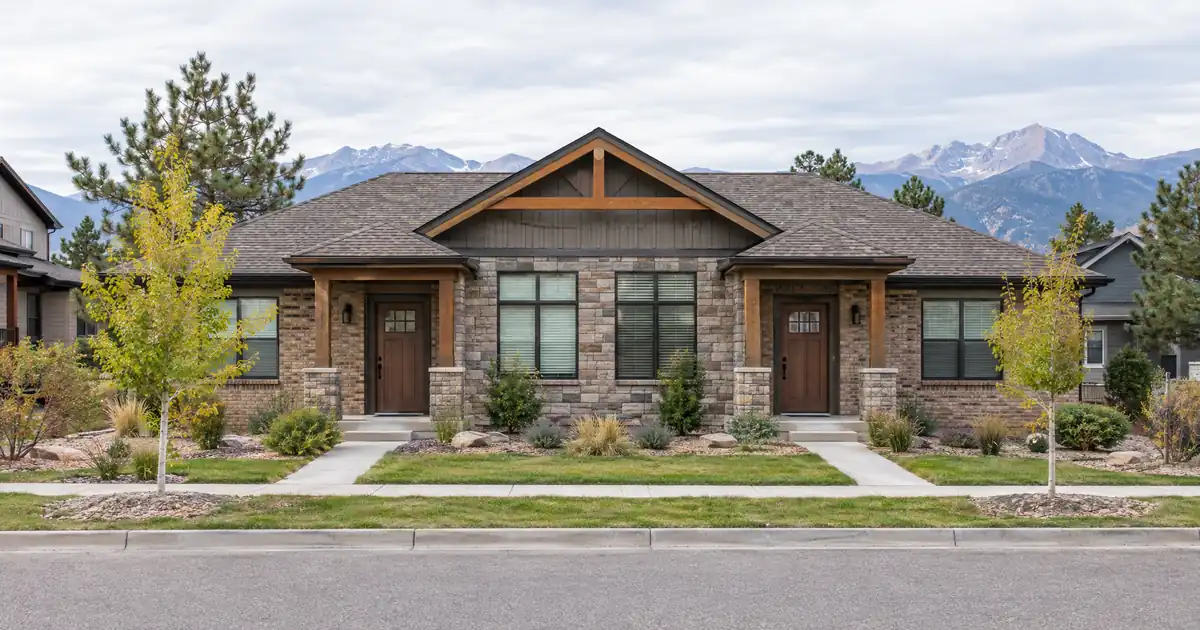
University District lists at a median of about $409,950, per House2Home Colorado’s Realtor.com snapshot, while Rent.com puts the neighborhood’s one-bedroom average at $1,202. Demand is not the problem: 62% of University of Northern Colorado students live off campus. Rent-to-value is the problem, because the price is high against the income. That tension defines a DSCR cash out refinance in Greeley, Colorado. The file works when in-place rent carries the coverage ratio, not when appreciation bails out the appraisal. Lendmire, a DSCR-focused mortgage broker, structures these refinances around that reality.
At a Glance: A DSCR cash-out refinance in Greeley, Colorado is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the file typically turns on in-place rent, the 75% LTV ceiling, and roughly six months of title seasoning rather than the owner’s personal income documentation.
DSCR Cash-Out Calculator
Run the cash-out numbers in Greeley, CO
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Citywide apartment vacancy is 6.3% with average rent down 2.8%, per the City of Greeley.
- Median sale price sits near $445,000 per Movoto.
- Median-priced single-family rentals model below 1.0x including taxes and insurance at 75% LTV.
- Duplex-to-fourplex stock near UNC and City Center is the stronger cash-out fit.
- Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Greeley Market Snapshot
A quick read on the Greeley investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $1,374 avg rent (-2.8%) (City of Greeley Quarterly) |
| Recent appreciation | 5.82% (NeighborhoodScout Greeley) |
| Employment | 51,404 jobs (q2 2025) (City of Greeley Quarterly) |
| Vacancy | 6.3% (City of Greeley Quarterly) |
Appreciation Won’t Fund This Cash-Out
Equity extraction in Greeley rests on low basis and rent, not market gains. Movoto shows a $445,000 median sale price with 44 days on market against 42 a year earlier, and 529 closings against 420. That is the median used throughout this article. Zillow’s typical home value runs lower at $420,464, down 1.6% year over year, reflecting a different methodology that measures a typical home rather than the sold median. Both readings describe a flat-to-soft market.
NeighborhoodScout shows a 5.82% annualized appreciation figure, but that is trailing data, and current readings don’t support extrapolating it. An investor planning a cash-out should treat value gains as upside, not as the funding source.
The leverage arithmetic shows why. Cash-out refinances cap at 75% LTV on typical program guidelines, and most purchase loans run higher. Say an owner bought at 80% leverage and the property appraises at the original price. The new loan cap sits below the existing payoff, so there is no cash-out at all. Value has to rise about 6.7% from the purchase price before the owner even reaches break-even on the payoff. After roughly six months of seasoning measured from title recording, that gain has to come from somewhere: a below-market purchase, a renovation, or rent repositioning. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Stock bought near the peak carries the most risk here. (Appraisers in a market with 44 days on market and softening prices don’t hand out generous values.) The cleaner candidates are owners with a low original basis, long-held properties, or buildings where renovation added rentable income.
The Coverage Math, Property Type by Property Type
Duplexes and low-basis houses clear 1.0x in Greeley. Median-priced single-family rentals generally do not. Coverage here means monthly rent divided by the full monthly obligation: principal, interest, taxes, insurance, and any HOA dues. The 1.00x level is a common program baseline because rent covers the payment at that point. Some lenders review lower ratios with compensating factors, lower leverage, or different pricing, and exact eligibility depends on lender guidelines, credit profile, reserves, and property review. Lendmire’s DSCR guide covers the mechanics.
The table below models coverage at 75% LTV using full PITIA on a standard 30-year amortization. Prices and rents come from the research. The pairings are illustrative assumptions, not sourced deal data. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
| Scenario | Price | Rent | Modeled coverage |
|---|---|---|---|
| Duplex, University District | $409,950 listing median | 2 × $1,325 | ~1.1x |
| House, City Center | $331,000 listing median | $2,132 (3BR) | ~1.1x |
| House, citywide median | $445,000 | $2,132 to $2,367 | 0.8x to 0.9x |
| House, West Greeley | $472,000 | $2,200 | ~0.8x |
| House, Kelly Farm | $596,300 listing median | $2,502 (4+BR) | ~0.7x |
Rents behind the table: Zumper puts the citywide two-bedroom average at $1,325. Rentometer shows $2,132 for three-bedrooms and $2,502 for four-plus. Trulia shows houses at $2,367. Redfin lists a West Greeley median rent of $2,200, though that figure is dated and mixes months. The West Greeley price is Redfin’s $472,000 median from its neighborhood page. Coverage bands are rounded down.
Where a house models below 1.00x, the structures a lender might review include a lower LTV, a sub-1.00 program, or an interest-only option. Qualification stays subject to lender guidelines, credit approval, and property review. Whether any of those beats simply buying a better-fitting asset is a separate question.
A Duplex Near Campus, Run Through the Model
Run the numbers on a duplex owned past seasoning, valued at the University District listing median, with both units renting at the citywide two-bedroom average. Combined rent works out to roughly 0.65% of value per month. At 75% LTV including taxes and insurance, that lands near 1.1x. There is cushion, but not much. A 5% rent shortfall or a modest expense surprise narrows it quickly. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
DSCR files in markets like this one typically look like a split: the cash-out candidate is either a low-basis small multifamily that covers the payment comfortably, or a single-family rental that lands just under the baseline and needs reduced leverage. Borrowers who underwrite using in-place leases, not aspirational rents, tend to see fewer surprises when the appraiser’s rent schedule comes back.
What Sets Greeley Apart: Who Pays the Rent
Tenant demand here is workforce-driven and hard to dislodge. The Livability employer list shows JBS USA and affiliates at 4,619 employees, the University of Northern Colorado at 3,600, and Banner Health’s North Colorado Medical Center at 3,000. Those counts are older, so read them as approximate. The City of Greeley’s quarterly update shows total employment of 51,404, up 1,234 jobs, about 2.5%, year over year. Data USA lists health care (6,247 residents), retail (6,062), and manufacturing (5,873) as the top resident sectors.
That mix (meatpacking, hospital, and a state university within a few miles) produces steady demand without dependence on Denver’s tech cycle. Banner NCMC sits within a system of 30 hospitals in six states. It anchors medical-worker rentals around Central and City Center.
Renter depth supports it too. RentCafe reports 39% of households renting, about 15,459 renter households. Two-bedrooms dominate at 43% of units per Point2Homes, which happens to match duplex and fourplex layouts.
Rent softness is the counterweight. City data shows apartment vacancy at 6.3%, improved by 0.9 points but still elevated, with average rent down 2.8% to $1,374. Weld County averages $1,533 at 7.0% vacancy.
Central, City Center, and the Pockets That Pencil
The lowest-basis neighborhoods offer the best coverage. The same House2Home snapshot shows listing medians of about $331,000 in City Center, $349,500 in North Central, and $395,000 in Central. Those are listing prices, not sales. Downtown sits near the hospital and has added breweries and cafes, per a local brokerage’s description, and Central is close to both UNC and the hospital.
Rent.com’s apartment data supports the direction. Cranford ($895 for a one-bedroom), Arlington ($925), and Westview ($1,000) are the lowest-rent pockets, while Central ($1,255) is among the priciest. One-bedroom rents move about $300 across neighborhoods, yet listing prices swing from roughly $331,000 to $596,300. Rent doesn’t scale with price. That favors the core over the newer subdivisions, though no neighborhood-level two- or three-bedroom rent data exists to confirm it (an inference, not a sourced finding).
Toss-up territory: University District versus City Center. The University District has the stronger tenant pool, but it carries a price premium of roughly 24% over City Center’s listing median. City Center has the better coverage math and the thinner tenant story. An owner already holding either can reasonably cash out; a buyer picking between them should weigh durability against coverage.
Skip Kelly Farm.
Kelly Farm’s listing median near $596,300 against four-bedroom rents around $2,500 models at roughly 0.7x. West Greeley at $472,000 runs near 0.8x. Those are good neighborhoods for owner-occupants and poor candidates for cash-out coverage. Buyers there are paying for newer construction and family appeal, not rental yield. Redfin shows West Greeley’s median down 3.6% year over year with 70.5 days on market, so appraisal risk compounds the thin coverage.
How Deep Is the Small-Multifamily Bench?
Deeper than most Front Range buyers assume. Homes.com showed 26 multifamily listings in ZIP 80631 and about 45 across Greeley, ranging from fourplexes of one-bedroom units to older conversions and a five-unit building. NeighborhoodScout puts duplexes and small buildings at 10.05% of housing units, against 56.49% single-family detached. That is thin in share terms but adequate for finding appraisal comps.
One UNC-area triplex listing illustrates the upside: a 6-bedroom unit at $2,500, a 4-bedroom at $1,795, and a 2-bedroom at $1,140, for a $5,435 rent stack. Large-bedroom units near campus rent well above typical whole-house averages. One listing is an illustration, not a market average, so the appraiser’s rent schedule decides what counts.
Listing-stated cap rates run from nearly 6% on a renovated fourplex to over 7% on a two-unit property, per Redfin’s multifamily listings. Those are seller marketing numbers that may omit reserves and full expenses. Recompute NOI before trusting them. Older buildings also matter: Point2Homes shows 23% of apartment stock built in the 1970s, so capex on aging product can eat into the proceeds.
What Do the Proceeds Actually Fund?
Proceeds are whatever remains of 75% of appraised value after the existing payoff and reserve requirements. That is not a guaranteed figure. Typical program guidance puts reserves near six months of PITIA, with credit tiers running from a 620 floor up through 660, 680, and 700. Loan size can reach $3,000,000 on standard programs, and smaller balances route through select lenders in the network. Higher credit tiers generally support better terms, subject to lender guidelines.
The smart use is a second small-multifamily acquisition at a lower basis, funded by seasoned equity from a property that already covers itself. Investors holding properties in an LLC can refinance in that name, subject to lender program eligibility. Lendmire’s DSCR cash-out refinance and the broader refi programs cover the structure. Owners weighing income-documentation loans can see the guide “Where DSCR and Conventional Diverge”. Colorado-specific program details sit on the Colorado DSCR investor loans page, and investors can talk to Lendmire or call 828-256-2183 to map a file.
Verify current local rental rules, taxes, and insurance with qualified local professionals before underwriting any of it.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Greeley, Colorado?
The property’s rent has to cover its full monthly obligation, with 1.00x the common baseline, and the loan must stay within the 75% LTV cap. Lenders also look at credit tier, reserves, and roughly six months of seasoning from title recording. In Greeley, duplexes and low-basis houses clear that test more readily than median-priced single-family homes. Final eligibility is subject to lender guidelines and property review.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Greeley, CO, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Greeley, Colorado?
Typical guidance includes a 620 credit floor, about six months of PITIA in reserves, and loan amounts up to $3,000,000 on standard programs. The property must be an eligible type, and manufactured homes, log homes, and barndominiums fall outside these DSCR programs. Program terms vary by lender, borrower, and property.
Can a single-family rental in Greeley support a cash-out at the citywide median?
Usually not at full leverage. At a $445,000 median price and $2,132 to $2,367 in house rents, modeled coverage including taxes and insurance runs roughly 0.8x to 0.9x at 75% LTV. Lower leverage, a sub-1.00 program, or a lower-basis property changes that picture, subject to lender review.
Does student demand near UNC help a duplex’s cash-out numbers?
It supports tenant durability, not automatic value. UNC reported 6,597 undergraduates per its enrollment presentation, and most students rent off campus. But coverage still depends on the appraiser’s rent schedule and the listing-median price level in University District.
The Single Best Next Step
Pull the appraiser’s rent schedule, not a listing or aggregator average, on the property you’d refinance. Greeley’s published rents disagree with each other by several hundred dollars, and a lease-backed Form 1007 number will settle whether the coverage clears before anything else gets priced.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
A non-QM mortgage broker (NMLS# 2371349), Lendmire arranges DSCR financing for real estate investors in 41 markets, which means 40 states plus Washington, D.C. Loans are underwritten primarily on property cash flow rather than personal income documentation, a structure that suits self-employed buyers and entity-owned portfolios. Lendmire places loans through wholesale investor lenders and is not a direct lender. Scotsman Guide named it a top-ranked workplace in 2026 after it was recognized by Scotsman Guide in 2025.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Rent.com
2. City of Greeley quarterly economic update, apartments
3. Movoto Greeley market trends
5. City of Greeley quarterly economic update, employment
6. Zumper
7. Rentometer
8. Trulia
9. Redfin
10. Redfin — West Greeley Housing Market
11. Livability: Top Employers in Greeley
13. Greeley Area Chamber: Banner NCMC
14. RentCafe
15. Point2Homes
16. Homes.com
17. Redfin’s multifamily listings
18. UNC enrollment presentation
19. Scotsman Guide — Top Workplaces 2026
20. recognized by Scotsman Guide in 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Greeley, CO · Investment Property Cash-Out Refinance in Colorado
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.